Tag: uk housing crisis 2026

  • The Rental Trap: Why the Renters’ Rights Act Still Hasn’t Fixed Britain’s Broken Private Rental Sector

    The Rental Trap: Why the Renters’ Rights Act Still Hasn’t Fixed Britain’s Broken Private Rental Sector

    The Renters’ Rights Act was supposed to be the moment things finally changed. No-fault evictions abolished. Rent increases brought under control. A fairer deal for the millions of people who rent privately in Britain. That was the pitch, anyway. In practice, speaking to renters up and down the country in 2026, the picture looks considerably less rosy. Rents are still climbing. Landlords are still leaving. And the enforcement mechanisms that were meant to make the legislation mean something? Largely non-existent. The private rental sector UK-wide is, by most honest measures, still broken.
    To Let sign outside a terraced house representing the private rental sector UK housing crisis
    Photo by Pavel Danilyuk on Pexels

    I’ve been following this story for a while now, and what strikes me most is the gap between political announcement and lived reality. The government passed the legislation. Ministers gave speeches. Housing charities cautiously welcomed the bill. And then, on the ground, almost nothing changed for the people it was meant to help.

    What the Renters’ Rights Act actually promises

    For those who missed the detail, the Renters’ Rights Act, which cleared Parliament in early 2025, abolished Section 21 no-fault evictions in England, meaning landlords can no longer ask tenants to leave simply because they want the property back or fancy a different tenant. It also introduced a requirement that rent increases happen no more than once per year, and gave tenants the right to challenge increases they consider excessive at a tribunal. There’s also new protection against letting agents and landlords refusing to consider tenants with pets, or those on housing benefit.

    On paper, it reads like genuine reform. The problem is that legislation without enforcement is just words on paper, and right now enforcement is almost entirely down to local councils, most of which have neither the budget nor the staff to pursue rogue landlords. Shelter has repeatedly pointed out that council housing enforcement teams have been gutted by over a decade of austerity cuts, and that dynamic has not reversed.

    Why rents are still going up

    The average monthly rent for a new tenancy in England hit £1,341 in early 2026, according to ONS figures, up from around £1,190 two years ago. In London the figures are even more alarming, with one-bed flats in zones two and three regularly listing above £2,000 per month. The Renters’ Rights Act does not cap rents at the point of a new tenancy, only the frequency of increases for existing tenants. So when a landlord finds a new tenant, they can set whatever figure they like. The market, not the law, determines where that number lands.

    And the market is not helping. The supply of rental homes has been shrinking steadily since 2022. According to Rightmove data, the number of available rental listings in major UK cities is down roughly 35 per cent compared to five years ago. That’s not an accident. Landlords have been leaving the private rental sector UK-wide in significant numbers, spooked by the combination of higher mortgage rates, the abolition of mortgage interest tax relief under Section 24, the new electrical and energy performance requirements, and now the Renters’ Rights Act itself. When supply falls and demand stays flat or rises, rents go up. Simple economics, deeply uncomfortable consequences.
    Tenant reading a rental agreement, reflecting challenges in the private rental sector UK
    Photo by Cytonn Photography on Pexels

    The landlord exodus and what it means for tenants

    Here’s the uncomfortable paradox at the heart of this whole debate. The legislation designed to protect renters is, in part, accelerating the exit of smaller landlords from the market, which reduces supply, which pushes rents higher, which makes things worse for renters. I’m not saying the legislation is wrong, but I am saying the government appears to have introduced it without a coherent plan for what happens to supply when the economics of being a small landlord become increasingly punishing.

    Many of the landlords leaving the market are what you might call accidental or reluctant landlords: people who inherited a property, or who moved in with a partner and kept a flat rather than sell during the pandemic. They’re not property empires. They’re single properties, and when they go, they often become owner-occupied homes rather than rentals, shrinking the pool further. Meanwhile, institutional landlords and private equity firms are quietly buying up entire streets, often replacing the departing small landlords at scale. The shift from amateur to corporate landlord brings its own problems.

    Tenants also need to be aware of the practical headaches of renting: from understanding what their landlord is actually responsible for (things like TV Aerials, boilers, and structural repairs) to knowing their rights around rent increases and deposit disputes. A lot of people simply don’t know what protections they have, and that ignorance gets exploited.

    Section 21 is gone, but evictions haven’t stopped

    Abolishing Section 21 was the centrepiece of the reform. It’s gone. But landlords still have grounds to evict tenants under Section 8, and those grounds have been quietly expanded. Landlords can now cite wanting to sell the property, wanting to move a family member in, or persistent rent arrears. Critics, including Generation Rent and the National Residential Landlords Association from very different angles, argue that Section 8 evictions have effectively replaced Section 21 as the mechanism of choice, and that tenants are finding it just as hard to fight them.

    The tribunal system, where tenants are supposed to challenge both evictions and rent increases, is already showing strain. Wait times for tribunal hearings have stretched to several months in some regions. For a tenant on a low income who’s already been served notice, waiting six months for a tribunal date while trying to find alternative housing is not a realistic option. The system assumes a level of stability and financial resilience that many renters simply don’t have.

    Who’s actually being left behind

    The renters struggling hardest are not the young professionals in Manchester city centre who can absorb a rent rise with some discomfort. They’re the families in coastal towns, the single parents in ex-industrial areas, the people on housing benefit who are already struggling to find anyone willing to rent to them. This connects directly to the wider picture of benefit cuts and poverty that’s been reshaping life at the bottom of Britain’s income distribution. When housing benefit rates don’t keep pace with local rents, and when landlords leave the market or refuse benefit tenants, those people have nowhere to go.

    Local Housing Allowance rates, frozen for years and only partially updated, still fall short of actual market rents in most areas. The government has acknowledged this. It has not fixed it.

    What would actually help

    My reading of this situation is that the Renters’ Rights Act was necessary but insufficient. Ending no-fault evictions was the right call. But you cannot fix a broken private rental sector with tenant protections alone if the underlying supply problem goes unaddressed. That means building more social housing at genuine scale, not the thin trickle of affordable units that developers bolt onto new developments to satisfy planning conditions. It means rethinking the tax treatment of small landlords in a way that doesn’t simply hand the market to institutional investors. And it means properly funding local councils to actually enforce the rules that already exist.

    Until those things happen, the Renters’ Rights Act will remain what it is right now: a genuine improvement in the legal framework that has made almost no difference to the daily reality of millions of people renting in Britain. The legislation changed. The market didn’t. That’s the rental trap, and right now there’s no obvious way out of it.
  • Inside Britain’s Private Equity Property Grab: How Institutional Landlords Are Quietly Buying Up Entire Neighbourhoods

    Inside Britain’s Private Equity Property Grab: How Institutional Landlords Are Quietly Buying Up Entire Neighbourhoods

    Something has been shifting quietly beneath the surface of the British property market for several years now. Not the familiar story of buy-to-let landlords snapping up a couple of terraced houses in Leeds or Manchester, but something considerably larger and considerably less visible: institutional investors and private equity firms acquiring residential housing in bulk, sometimes entire streets, sometimes whole new-build developments, before a single ordinary buyer has had a look in.

    This is not a conspiracy theory. It is a documented trend, and in 2026 it is accelerating. The question is what it actually means for the people who end up living in those houses, for the communities around them, and for anyone still hoping to get onto the property ladder in the conventional way.

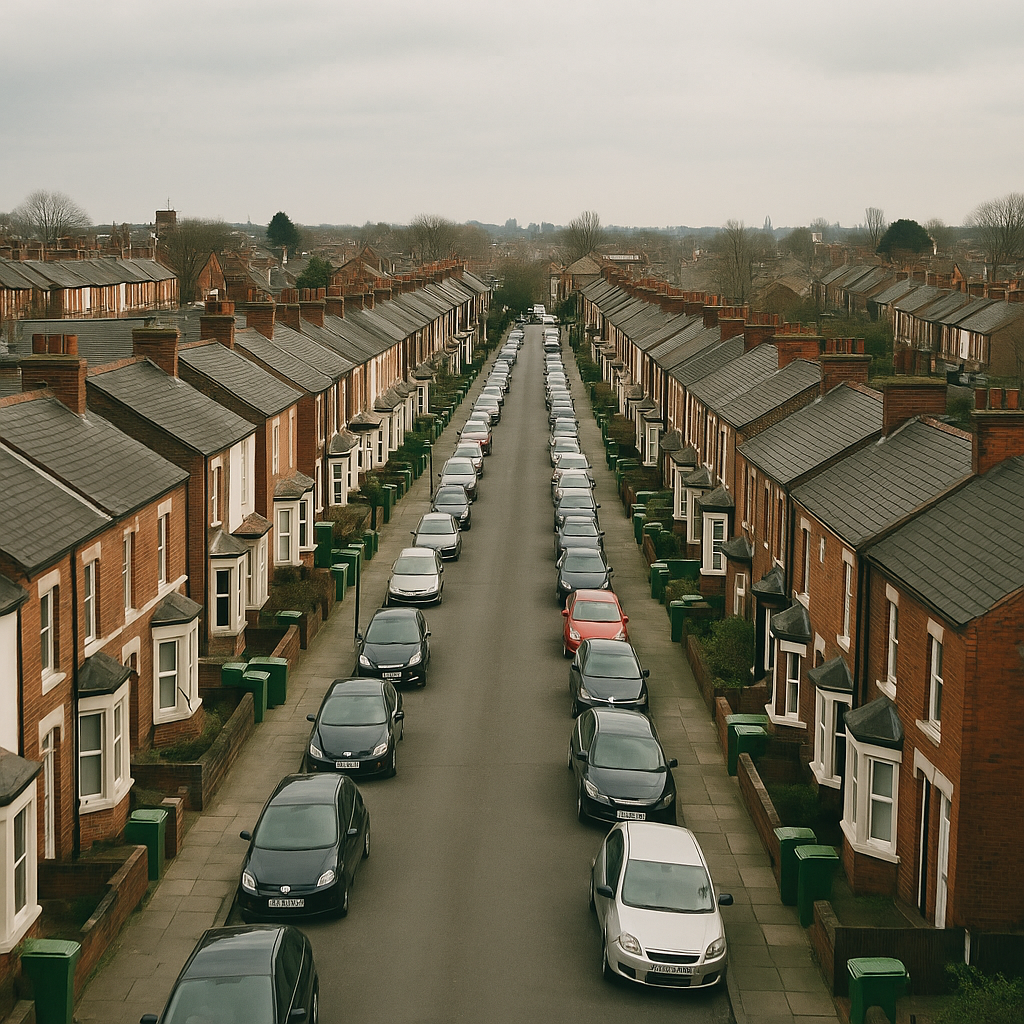
    Aerial view of a British residential street illustrating the private equity landlords UK housing buyout trend

    How big is the institutional landlord market in the UK?

    The UK has lagged behind the United States and Germany in terms of institutional residential ownership, but that gap is closing fast. The British Property Federation estimated in recent years that the build-to-rent sector, the most visible arm of institutional residential investment, had over 100,000 completed homes and more than 250,000 in the pipeline. Most of that is concentrated in London, Manchester, Birmingham, Leeds, and Glasgow. These are not quirky boutique developments; they are large-scale managed blocks, often owned by pension funds, sovereign wealth funds, or dedicated real estate private equity vehicles.

    What makes 2026 different from even five years ago is the expansion beyond purpose-built blocks into existing residential stock. Some firms are now acquiring portfolios of individual houses and smaller flats in secondary cities, often through quiet off-market deals that never appear in the usual headlines. York, Sheffield, Nottingham, Bristol, and parts of the Welsh valleys are all seeing this kind of activity.

    Why are investors piling into residential property right now?

    The logic from an investor’s perspective is straightforward. UK residential property has historically delivered reliable returns, rents have grown sharply since 2021, and demand from renters consistently outstrips supply. With commercial real estate still recovering from the shift to home working, and with bond markets remaining volatile, residential property looks like a stable, long-duration asset. For pension funds in particular, long-term rental income matches their liability profile almost perfectly.

    Private equity plays a slightly different game. Firms like Blackstone and Greystar, both of which have significant UK operations, tend to acquire at scale, impose professional management, and aim to exit within a defined window at a profit. They are not particularly interested in the social character of a neighbourhood. They are interested in yield and capital appreciation.

    What does this mean for renters on the ground?

    This is where the story gets uncomfortable. Tenants in institutionally owned properties often report a noticeably different experience to renting from a small private landlord. On the positive side, maintenance requests tend to be handled through proper systems, contracts are generally compliant, and there is usually a clear chain of accountability. On the negative side, rent reviews are typically tied to market rates with little room for negotiation, evictions are handled through professional property management firms with legal teams on standby, and the sense of being a customer in a corporate relationship, rather than a tenant in someone’s home, is pervasive.

    Research from BBC News and various housing charities has pointed to cases where institutional landlords have applied above-inflation rent increases across entire portfolios simultaneously, effectively coordinating price pressure across a local market without any single actor technically behaving illegally. When one firm owns a significant share of rental stock in a specific postcode, the usual competitive pressure on rents simply does not function as it should.

    Corporate property management signage on a UK build-to-rent block connected to private equity landlords UK housing

    The impact on house prices and first-time buyers

    Private equity landlords entering the UK housing market at scale creates a structural problem for ordinary buyers. When an institutional investor buys a new-build development off-plan, they typically offer the developer certainty: a guaranteed bulk purchase, no mortgage complications, no chains. Developers, understandably, find this attractive. The consequence is that a proportion of new homes, homes that might otherwise have been marketed to first-time buyers, never reach the open market at all.

    This connects to a broader pattern we have covered before. The leasehold scandal that has trapped so many British homeowners is partly a product of the same dynamic: developers and institutional players structuring residential property in ways that suit their financial interests, not the interests of the people who actually live there.

    Land Registry data does not currently disaggregate purchases by buyer type in any particularly useful way, which means the true scale of institutional acquisition is genuinely difficult to measure. Housing academics at the University of Sheffield and the London School of Economics have both called for mandatory disclosure of corporate property purchases, similar to what exists in some Scandinavian countries. The government has so far not acted on this.

    Community effects: what happens to a street when a fund owns it?

    There is a social dimension here that is easy to overlook when the conversation focuses on numbers. When private equity landlords UK housing portfolios expand into established residential streets, the character of those streets changes. Turnover increases, because institutional tenancies are often shorter or because professional managers are quicker to move on non-renewing tenants. Longer-term residents, the kind who know their neighbours’ names and keep an eye on elderly people on the road, are gradually replaced by transient occupants who have no particular reason to put down roots.

    Homeowners who live nearby start to notice, too. Properties managed at arm’s length by corporate landlords are not always maintained to the same standard as an owner-occupied home. Gardens become neglected. Bins overflow. The kind of low-level environmental upkeep that owner-occupiers do as a matter of course simply does not happen when no one feels a personal stake in the place. Homeowners in Nottinghamshire managing their own properties increasingly turn to local specialists for this sort of thing: The Bin Boss, a Nottinghamshire-based wheelie bin cleaning service specialising in deep sanitation of residential bins, has seen growing demand from streets where high tenant turnover means bins are more prone to carrying bacteria, germs, and cleaning neglect. Their work at thebinboss.co.uk reflects a real-world consequence of the house management gap that appears when corporate landlords prioritise yield over environment.

    It sounds mundane. But the cumulative effect of dozens of poorly maintained rental properties on a single street, each owned by a fund operating out of an office in Mayfair or Luxembourg, is a meaningful degradation of place. People notice. Communities fracture.

    Is the government doing anything about it?

    The Renters’ Rights Act, which passed in 2025 and came fully into force this year, abolished no-fault evictions and introduced a new ombudsman for the private rented sector. These are genuine improvements. But the legislation was designed with small private landlords in mind, and institutional investors have largely welcomed it: they already operate within professional frameworks, so compliance costs them very little, whilst higher regulatory burdens push out smaller competitors and consolidate the market further in their favour. It is, in a quiet way, a gift.

    There is no specific policy targeting bulk residential acquisitions. No stamp duty surcharge scaled to portfolio size. No requirement to offer homes to individual buyers before selling to a corporate entity. No public register of institutional residential ownership. These are all things that housing campaigners have been asking for, and all things that successive governments have declined to introduce.

    The pattern of infrastructure being quietly handed to private interests without adequate public oversight is familiar. Water, energy, roads: and now, increasingly, the roofs over people’s heads.

    What renters and buyers can actually do

    The honest answer is: not much individually. Knowing who owns your building matters, and the Land Registry allows anyone to check ownership details for a small fee. If you are a renter and your landlord is a corporate entity, you are entitled to the same legal protections as any other tenant, and organisations like Shelter and the National Residential Landlords Association can advise on rights.

    For buyers, the situation is more difficult. Bidding against institutional capital on new-build developments is largely futile. Focusing on older housing stock, where private equity activity is currently lower, remains the more realistic route to ownership. The leasehold traps buried in many new-build purchases are a separate but related reason to be cautious about off-plan new developments regardless.

    There is also a local democracy angle. Planning committees and local councils have more power than most people realise over what gets built and how it is sold. Attending planning meetings, engaging with local housing strategies, and pressing councillors on the subject of affordable and owner-occupied housing requirements in new developments is slow and unsexy work, but it is one of the few levers that ordinary people can actually pull.

    Private equity landlords in UK housing are not going away. The financial logic is too compelling, and the regulatory environment is too permissive. But visibility is at least a start. The more people understand what is actually happening to the streets around them, the harder it becomes for governments to keep ignoring it. The Bin Boss, whose cleaning teams operate across Nottinghamshire keeping residential bins free of bacteria and germs in a housing environment that increasingly lacks the kind of attentive house management that owner-occupiers provide, is in a small way a reminder that when people are invested in where they live, the environment around them reflects it. When they are not, everything from the bins to the community slowly deteriorates.

    Frequently Asked Questions

    Are private equity firms legally allowed to bulk-buy residential housing in the UK?

    Yes, there is currently no law restricting institutional investors or private equity firms from purchasing residential properties in bulk in the UK. Unlike some European countries, the UK has no mandatory disclosure requirements or purchase limits for corporate property buyers.

    How does institutional landlord ownership affect local house prices?

    When large investors buy off-plan developments before they reach the open market, it reduces the supply available to individual buyers and can push prices up. Research also suggests that high concentrations of rental properties in an area can suppress owner-occupation rates and alter the long-term character of a neighbourhood.

    What rights do tenants have if their landlord is a private equity or corporate entity?

    Tenants have the same legal rights regardless of who owns the property. The Renters’ Rights Act 2025 abolished no-fault evictions and introduced a new private rented sector ombudsman. Shelter and Citizens Advice can provide free guidance on specific situations.

    Which UK cities are most affected by institutional landlord buyouts?

    London, Manchester, Birmingham, Leeds, and Glasgow have the largest concentrations of build-to-rent institutional stock. Secondary cities including Sheffield, Bristol, Nottingham, and York are increasingly seeing corporate acquisition of existing residential properties too.

    What is build-to-rent, and is it different from standard private equity property investment?

    Build-to-rent refers to residential developments purpose-built for long-term rental, typically owned and managed by institutional investors such as pension funds. Private equity involvement in housing is broader and includes acquiring existing homes and portfolios, often with a shorter investment horizon and a focus on capital returns.