Author: Olly

  • The Pothole Republic: How Britain’s Roads Became the Worst in Western Europe and Why the Repair Bill Keeps Growing

    The Pothole Republic: How Britain’s Roads Became the Worst in Western Europe and Why the Repair Bill Keeps Growing

    There is a particular British ritual that happens every autumn, without fail. The temperature drops, the rain comes sideways, and somewhere between October and March the road outside your house quietly falls apart. A crack becomes a dip, a dip becomes a crater, and by February you are swerving around something that could genuinely swallow a car tyre. I have driven this country extensively and I have never once thought: these roads feel well-maintained. The road repair backlog in this country is not a new problem. But the scale of it, in 2026, has become genuinely extraordinary.

    The Asphalt Industry Alliance, which publishes its Annual Local Authority Road Maintenance survey every year, estimated in its most recent report that it would cost over £16 billion to clear the backlog of road repairs across England and Wales. That figure is not a misprint. Sixteen billion pounds. And it has been rising steadily for years, because councils are spending less on roads each year than the roads lose in condition. You cannot patch your way out of that arithmetic.
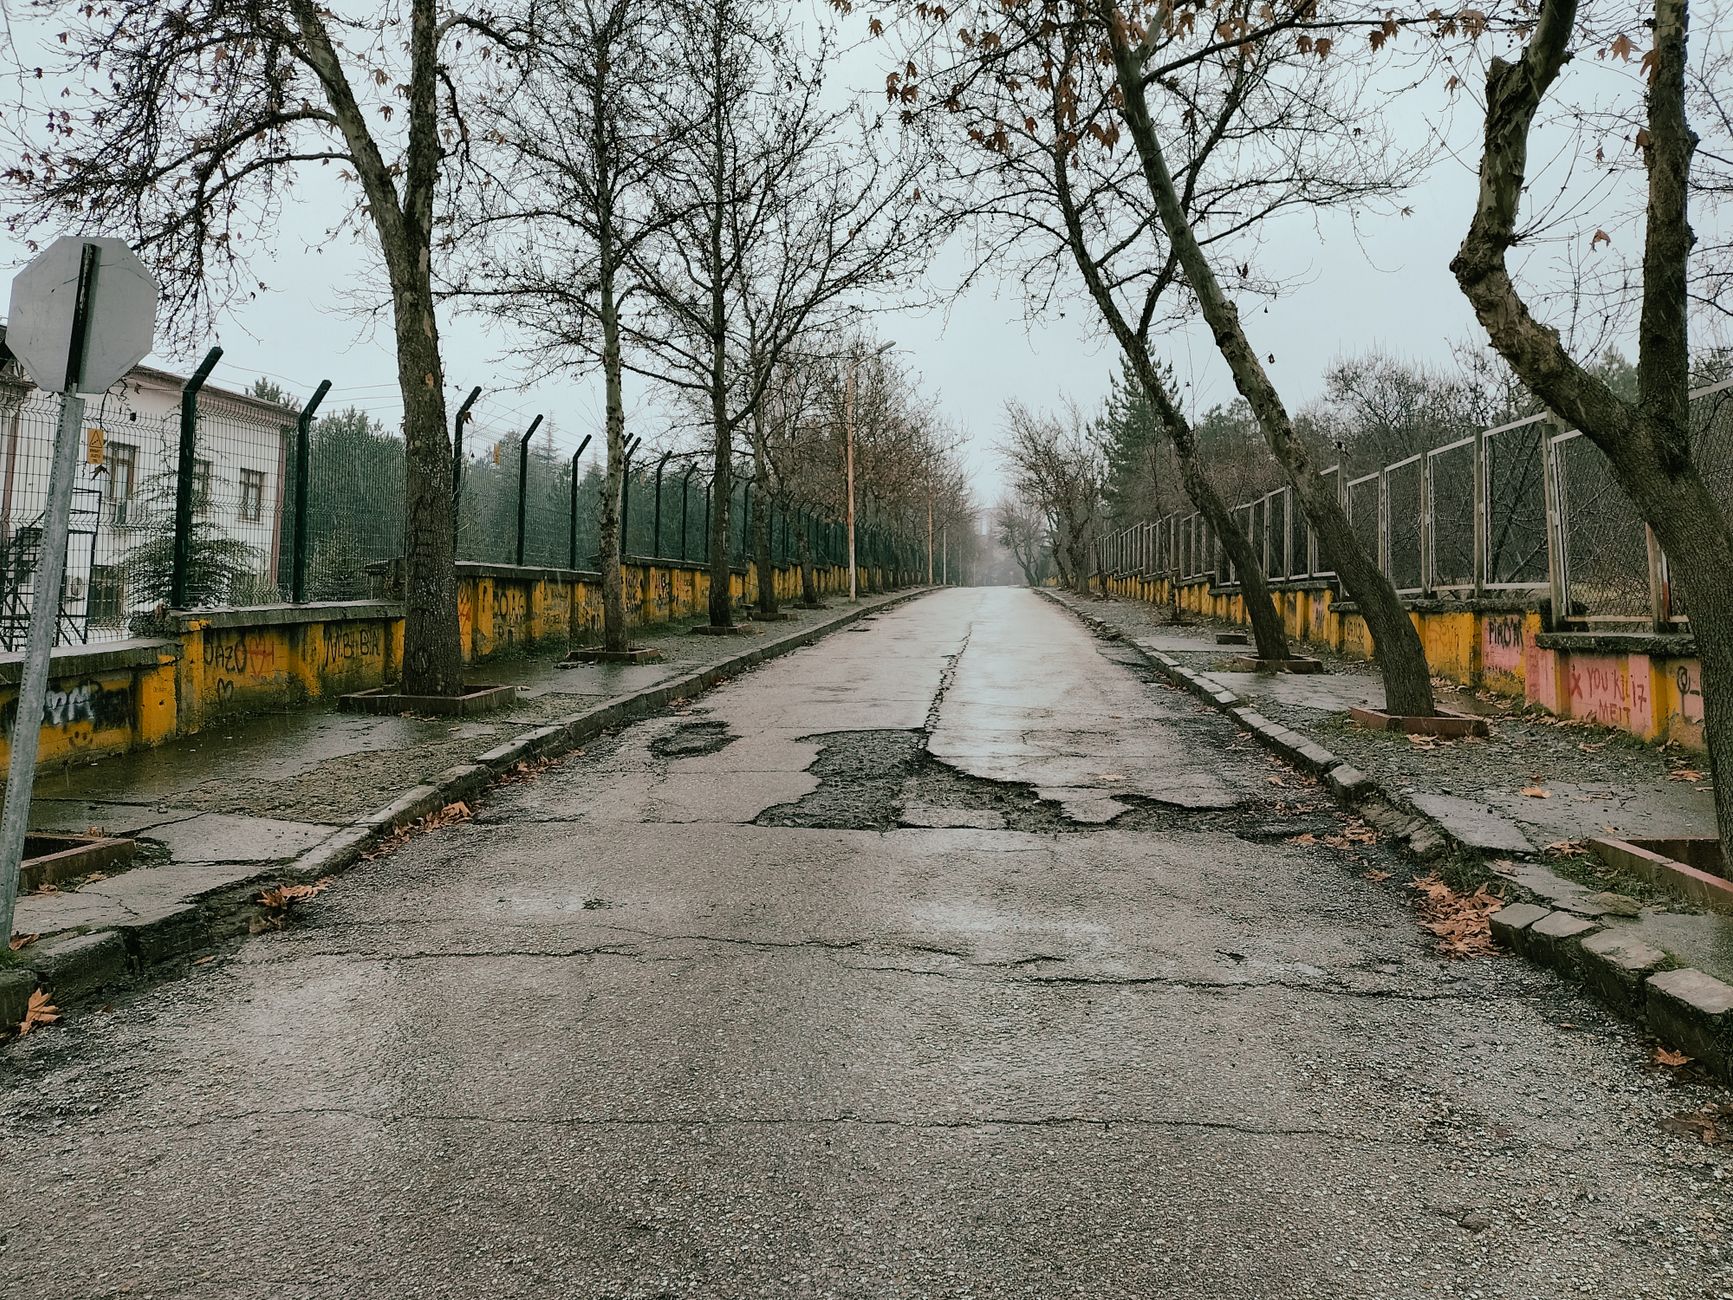
    Heavily potholed British road illustrating the UK road repair backlog
    Photo by Zülfü Demir📸 on Pexels

    Why council highways budgets have been gutted

    Local authorities are legally responsible for most of the roads we actually drive on day to day. Motorways and major A-roads sit with National Highways, but the vast majority of the network, the B-roads, the residential streets, the country lanes, falls to county and unitary councils. And those councils have been squeezed relentlessly since 2010. The Local Government Association has repeatedly made the point that highways maintenance is one of the first budgets to get trimmed when councils face financial pressure, partly because the consequences are slow-moving and diffuse. Nobody notices the pothole that hasn’t formed yet.

    What they do notice is the one that damages their car. The RAC reported that pothole-related breakdowns hit record levels in 2023, with the problem persisting into 2024 and 2025. Vehicle suspension damage, buckled alloys, blown tyres: the AA estimates that potholes cost British drivers around £3 billion a year in repairs and insurance claims. That is an enormous transfer of cost from public infrastructure budgets onto private citizens. And unlike the captive pricing you encounter at a motorway service station, this one you cannot choose to avoid. You just have to drive on the roads.

    How does Britain compare to the rest of Europe?

    Germany, France and the Netherlands all score considerably higher than the UK in the World Economic Forum’s infrastructure quality indices. France in particular maintains a road network that feels like a different planet compared to, say, the A47 through Fenland in February. Some of that is down to climate: freeze-thaw cycles in the UK are brutal on asphalt, and British winters are wet enough to accelerate surface degradation significantly faster than drier continental climates. But climate is not the whole story.

    Germany invests roughly twice as much per kilometre of road as England does, when you account for the full network. The Dutch have adopted a long-term infrastructure investment model that treats roads as assets requiring sustained capital expenditure, rather than recurring costs to be managed down. Britain, by contrast, has cycled through short-term patching regimes for decades. Reactive maintenance, the kind where you fill the hole after it forms rather than resurfacing before it does, is significantly more expensive per square metre in the long run. Every highways engineer knows this. Every council knows this. And yet here we are.
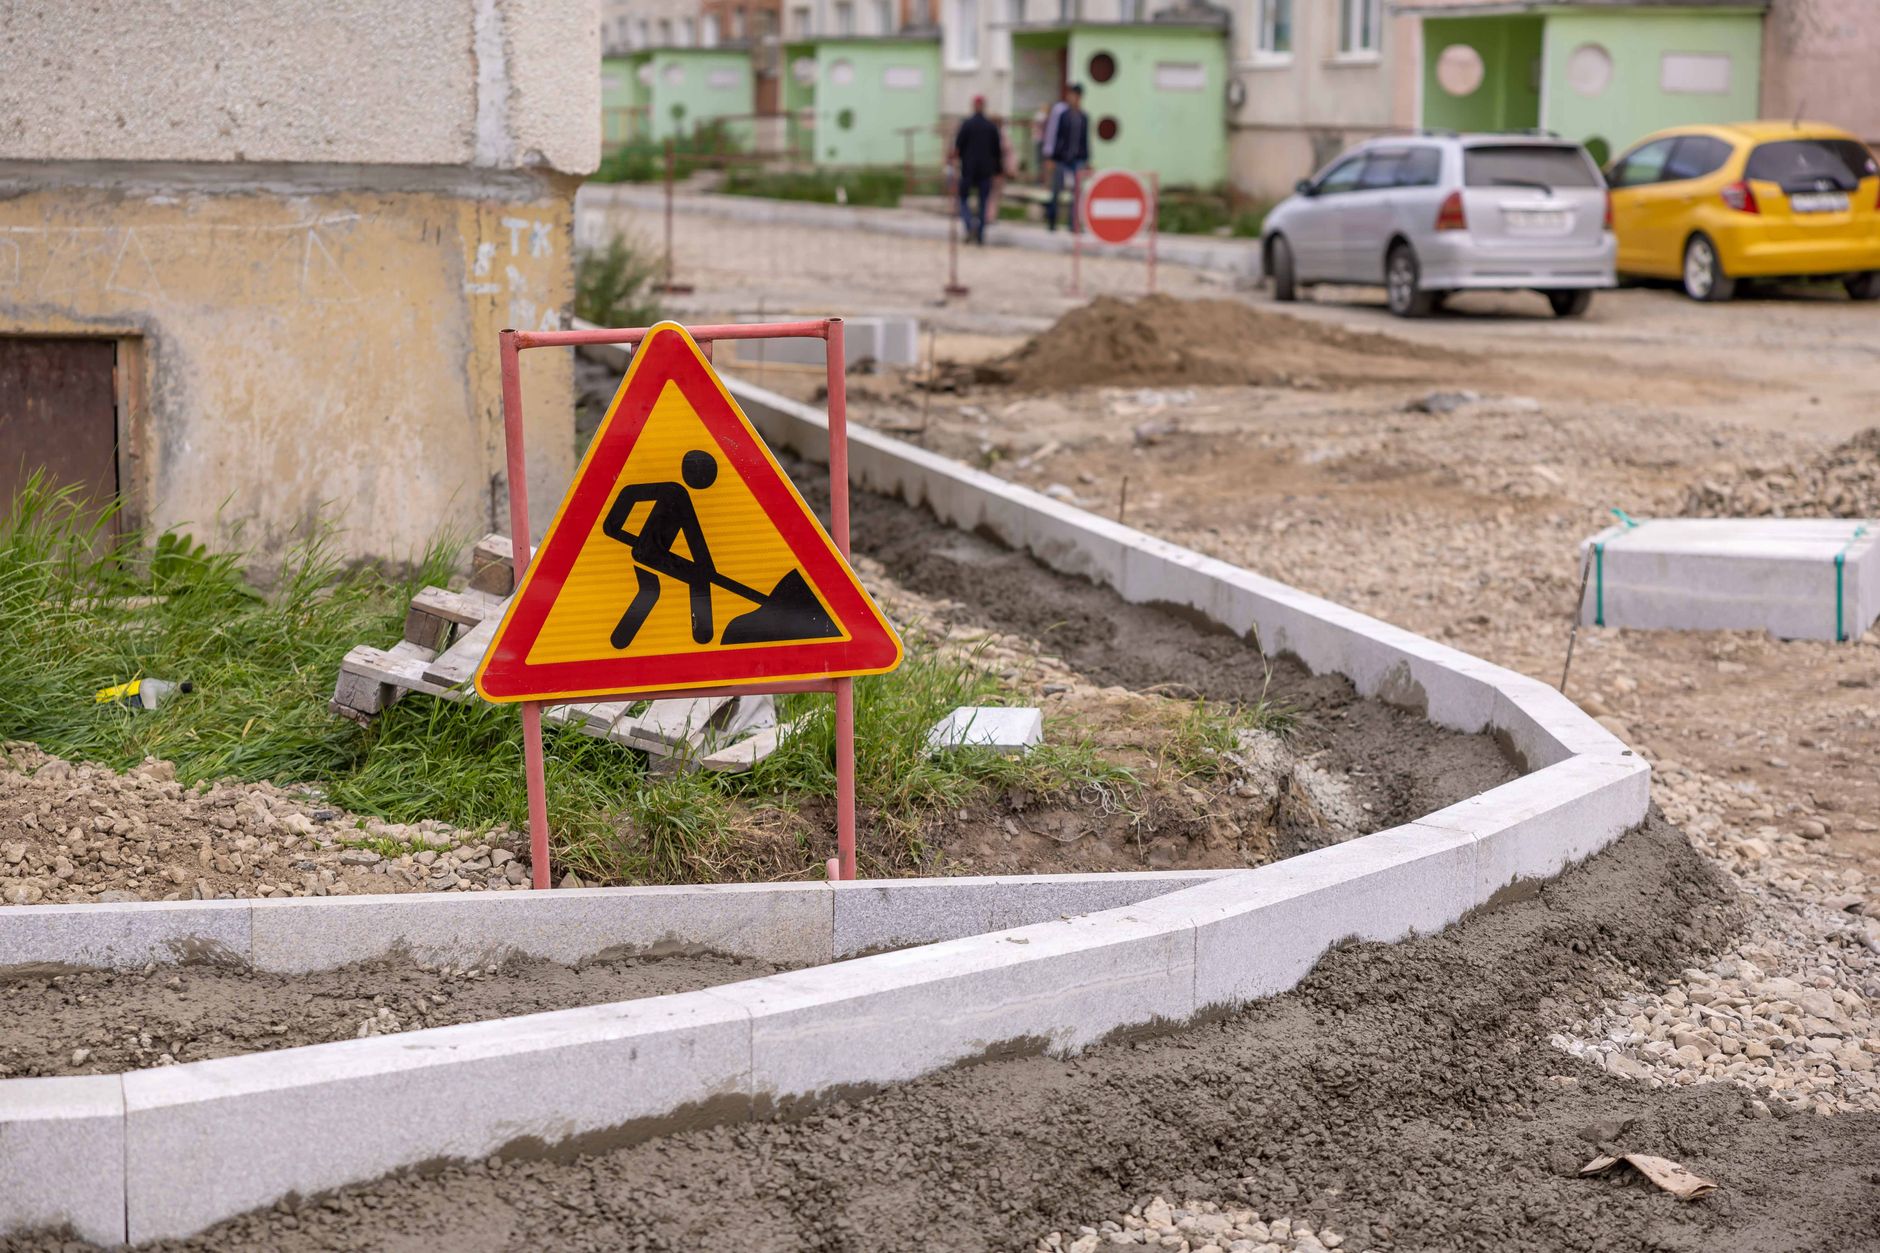
    Highways crew carrying out road repair work, part of tackling Britain's road repair backlog
    Photo by Sergei Starostin on Pexels

    The postcode lottery of road quality

    Not all councils are equally badly off. Surrey, which has a relatively well-funded highways department and a large council tax base, maintains roads to a noticeably higher standard than, say, parts of County Durham or rural Lincolnshire. The disparity between well-resourced southern English counties and underfunded northern and rural councils is striking. A stretch of road in the Cotswolds is likely to be in considerably better condition than the equivalent route through County Durham, not because Durham’s engineers are worse, but because they have less money to spend per kilometre.

    This postcode lottery mirrors problems we have documented elsewhere on this blog, from NHS dentistry deserts to serious violence concentrating in towns that get the least resource. The pattern is consistent: the places that most need investment are the ones least likely to get it, because funding models tend to follow existing economic activity rather than need.

    The government’s Pothole Fund, which has been topped up and re-announced several times under successive administrations, sounds more substantial than it is when you spread it across the entire English road network. The 2026 allocation, whilst welcome, amounts to roughly £1.60 per square metre of local road surface when distributed across the network. That does not go far when a full resurfacing job costs between £50 and £80 per square metre.

    What it actually costs to fix a road properly

    There is a meaningful difference between filling a pothole and fixing the road. A temporary cold-mix patch, the kind most councils use for reactive maintenance, costs perhaps £50 to £100 per hole but typically lasts less than a year in British weather. A proper structural repair involves cutting back the damaged area, clearing out the base, and laying hot-mix asphalt in layers, which is four or five times more expensive but lasts a decade or more. Full carriageway resurfacing costs in the region of £500,000 per kilometre for a standard two-lane rural road.

    The maths of under-investment is brutal. Every year a council defers resurfacing, the road degrades further, the base gets waterlogged, and the eventual repair bill grows. What might have been a £200,000 preventative resurfacing job in 2020 can easily become a £600,000 structural reconstruction job by 2026. It is the same logic that applies to any neglected infrastructure, whether that is a leaking roof, a corroded boiler, or a TV aerial left unserviced for twenty years until the signal fails entirely. The team at tv-aerials.co.uk would probably put it plainly: catching the problem early is always cheaper than dealing with the failure.

    Can road pricing actually fix this?

    There is a revenue problem lurking underneath the maintenance crisis that does not get enough attention. Fuel duty, which has historically contributed to road maintenance budgets, is in long-term decline as the UK vehicle fleet electrifies. By 2035, petrol and diesel car sales will have been banned for two years, and the transition to electric vehicles, while welcome for emissions, strips out a substantial tax stream. The government’s own review of motoring taxation has acknowledged that a replacement mechanism will be needed, with road pricing the most discussed option.

    Road pricing, done properly, could both fund infrastructure and distribute usage more efficiently, reducing congestion on the most deteriorated routes. But the politics of it are toxic. Telling British drivers, who already feel they pay enormous sums in fuel duty and VED, that they will now pay per mile is not a vote-winner. The government has moved cautiously, and the reform debate continues to circle without landing.

    My honest read of the situation is that Britain will not fix its road repair backlog without either a significant increase in dedicated local highways funding or a wholesale reform of motoring taxation that actually hypothecates revenue to road maintenance. Neither seems imminent. In the meantime, councils will keep patching, potholes will keep forming, and drivers will keep sending insurance claims to their local highways authority at a rate that itself costs the public purse millions in administration every year. It is not a system anyone would design. It is a system nobody has had the will to replace.

    Frequently Asked Questions

    How big is the road repair backlog in England and Wales?

    The Asphalt Industry Alliance estimates the backlog of road repairs across England and Wales exceeds £16 billion as of the most recent ALARM survey. That figure has been growing year on year because councils consistently spend less on maintenance than roads lose in condition.

    Who is responsible for fixing potholes in the UK?

    Local councils, specifically their highways departments, are responsible for the vast majority of roads including B-roads, residential streets and rural lanes. Motorways and major A-roads are managed by National Highways. If a pothole damages your vehicle, you can submit a claim to the relevant local authority.

    Can you claim compensation for pothole damage to your car?

    Yes. If a council knew about a pothole and failed to repair it in a reasonable time, you can submit a compensation claim to the local highways authority. You will need evidence: photos of the pothole with measurements, a dated report showing the council was aware, and repair quotes or receipts for vehicle damage.

    Why are UK roads worse than roads in France or Germany?

    Several factors combine: UK councils have faced significant budget cuts to highways maintenance since 2010; Britain’s wet winters accelerate freeze-thaw surface damage; and the UK has historically favoured cheap reactive patching over costlier but more durable preventative resurfacing. Germany and France both invest considerably more per kilometre of road.

    What is the government's Pothole Fund and does it make a difference?

    The Pothole Fund is a central government allocation to local authorities specifically for road repairs. While successive governments have topped it up and re-announced it, the per-kilometre spend it enables is small relative to the actual backlog. Critics argue it funds reactive maintenance rather than the structural resurfacing programmes needed to address the root problem.
  • Steel, Sovereignty and Scunthorpe: What the Collapse of Britain’s Last Blast Furnaces Actually Means for National Security

    Steel, Sovereignty and Scunthorpe: What the Collapse of Britain’s Last Blast Furnaces Actually Means for National Security

    Britain can no longer make steel from raw materials. That sentence deserves to sit on its own for a moment, because it has not been true at any point in the last century and a half. With the closure of the blast furnaces at Port Talbot in 2024 and the collapse of operations at Scunthorpe in 2025, the UK blast furnace closure story is not a chapter of industrial decline, it is the end of an era that stretches back to the mid-Victorian age. I have been following this closely, and the more you dig into what it actually means, the more uncomfortable the picture becomes.

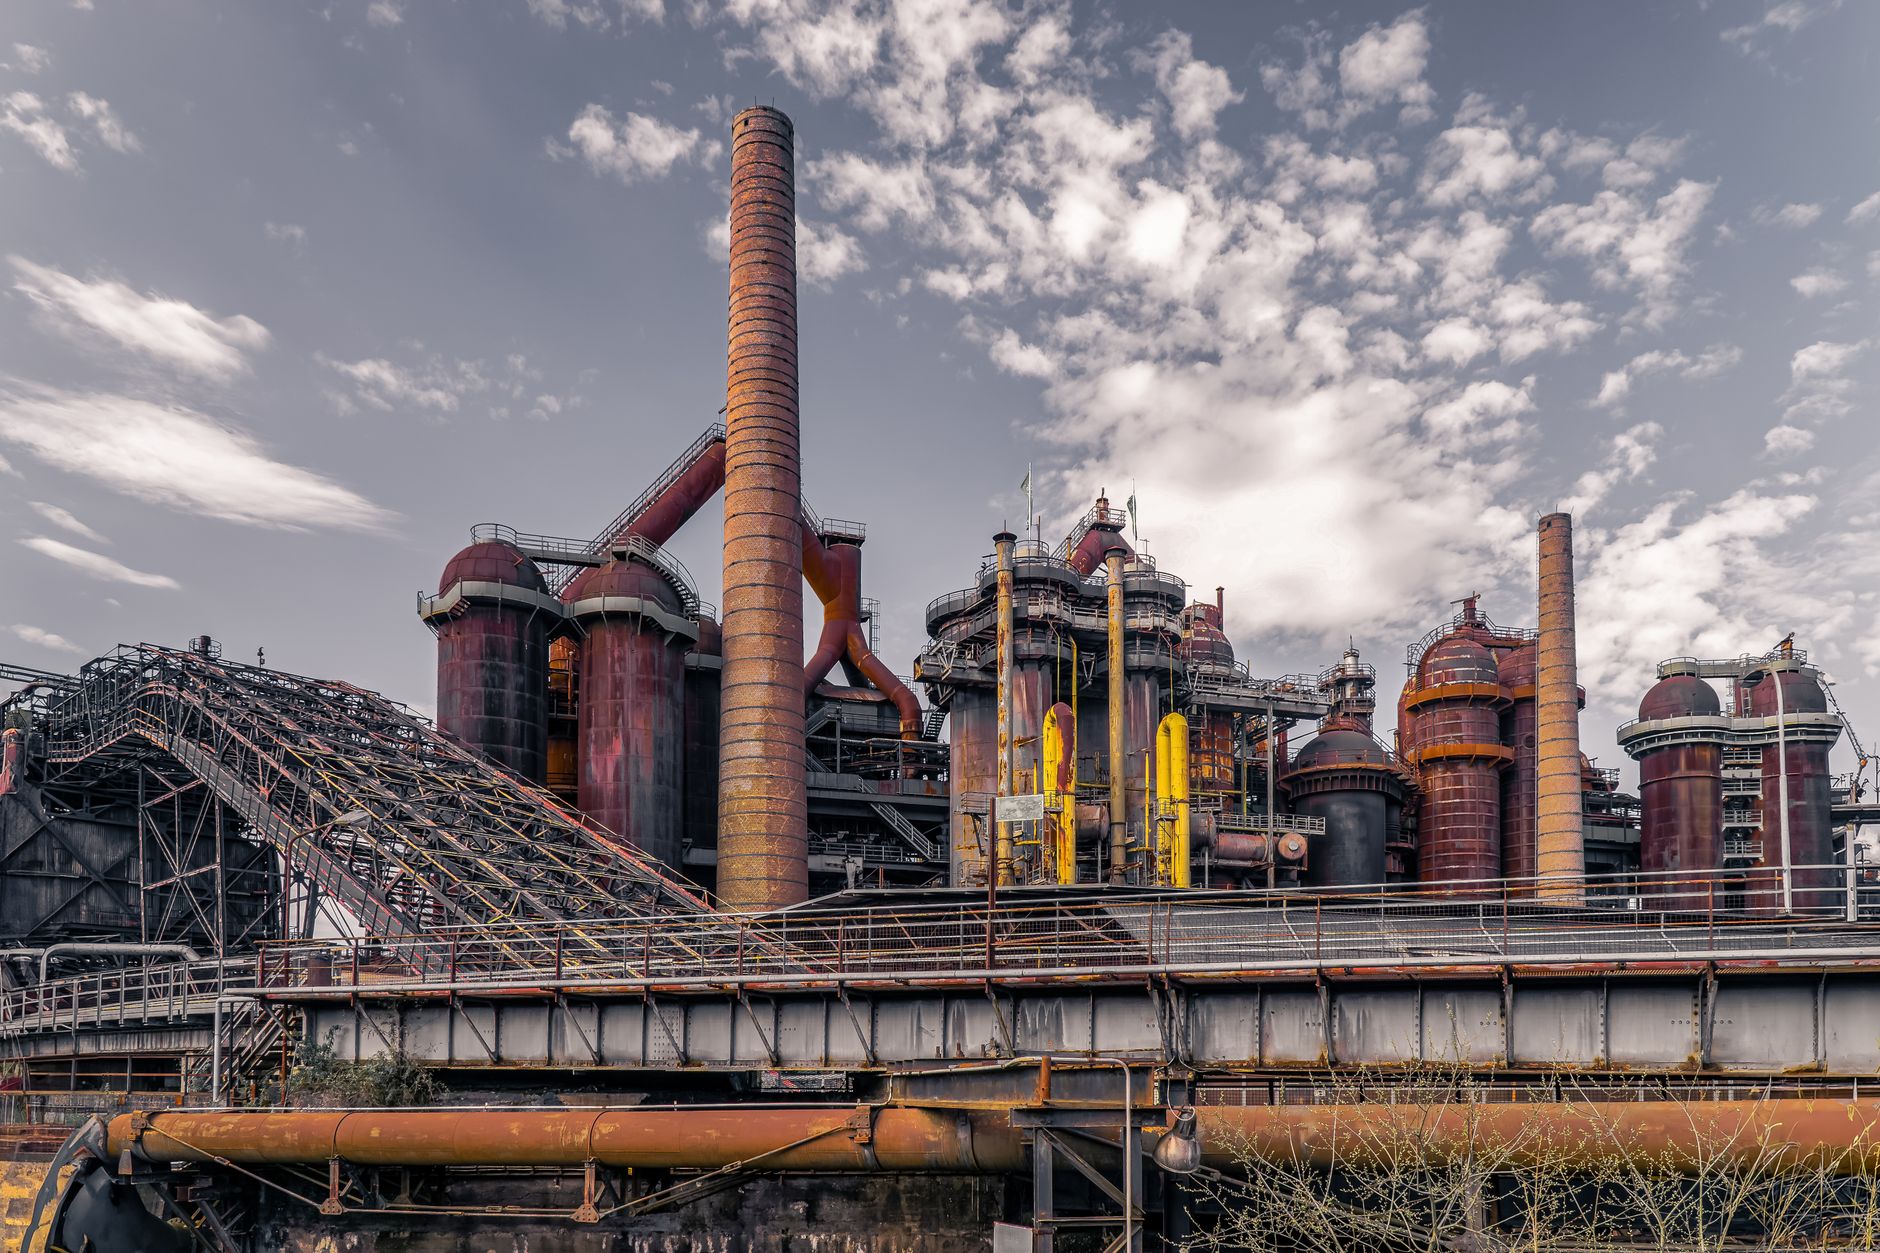
    UK blast furnace closure — industrial steel plant at dusk with furnace glow
    Photo by Michael on Pexels

    The government’s framing has been relentlessly optimistic. Electric arc furnaces (EAFs) are the future, ministers say. Cleaner, cheaper, more flexible. And there is truth in that, up to a point. But EAFs work by melting scrap steel, which means they are entirely dependent on a supply of recycled material. They cannot produce virgin steel from iron ore and coking coal. For certain grades of steel, the kind used in armour plating, submarine hulls, aerospace components and large infrastructure projects, that distinction is not academic. It is the difference between being able to make something domestically and having to buy it from somewhere else.

    What we have actually lost

    The blast furnace process, for all its environmental cost, produces what metallurgists call primary steel. It has specific mechanical properties, particularly in terms of purity and grain structure, that recycled steel from an EAF cannot always replicate. The Ministry of Defence has acknowledged, in fairly guarded language, that certain specifications for naval and armoured vehicle steel require primary production. The question nobody in government has answered convincingly is where that steel now comes from.

    The honest answer, right now, is mostly Europe and Asia. France, Germany, and increasingly South Korea and India produce primary steel at scale. In peacetime, buying it on global markets is not a crisis. But defence procurement planners are not supposed to plan for peacetime alone. The lessons of 2022, when Russia’s invasion of Ukraine exposed how quickly European countries had allowed their defence supply chains to hollowed out, appear not to have landed as hard as they should have in Whitehall.

    Britain spent much of 2025 debating the future of the Scunthorpe site with a level of urgency that felt, frankly, theatrical. Jingye Group, the Chinese owner of British Steel, repeatedly threatened closure. The government eventually stepped in with legislation to take control of the site, but the blast furnaces had already been allowed to cool. Once a blast furnace is shut down, restarting it is an enormously expensive undertaking. These are not switches you flick back on.

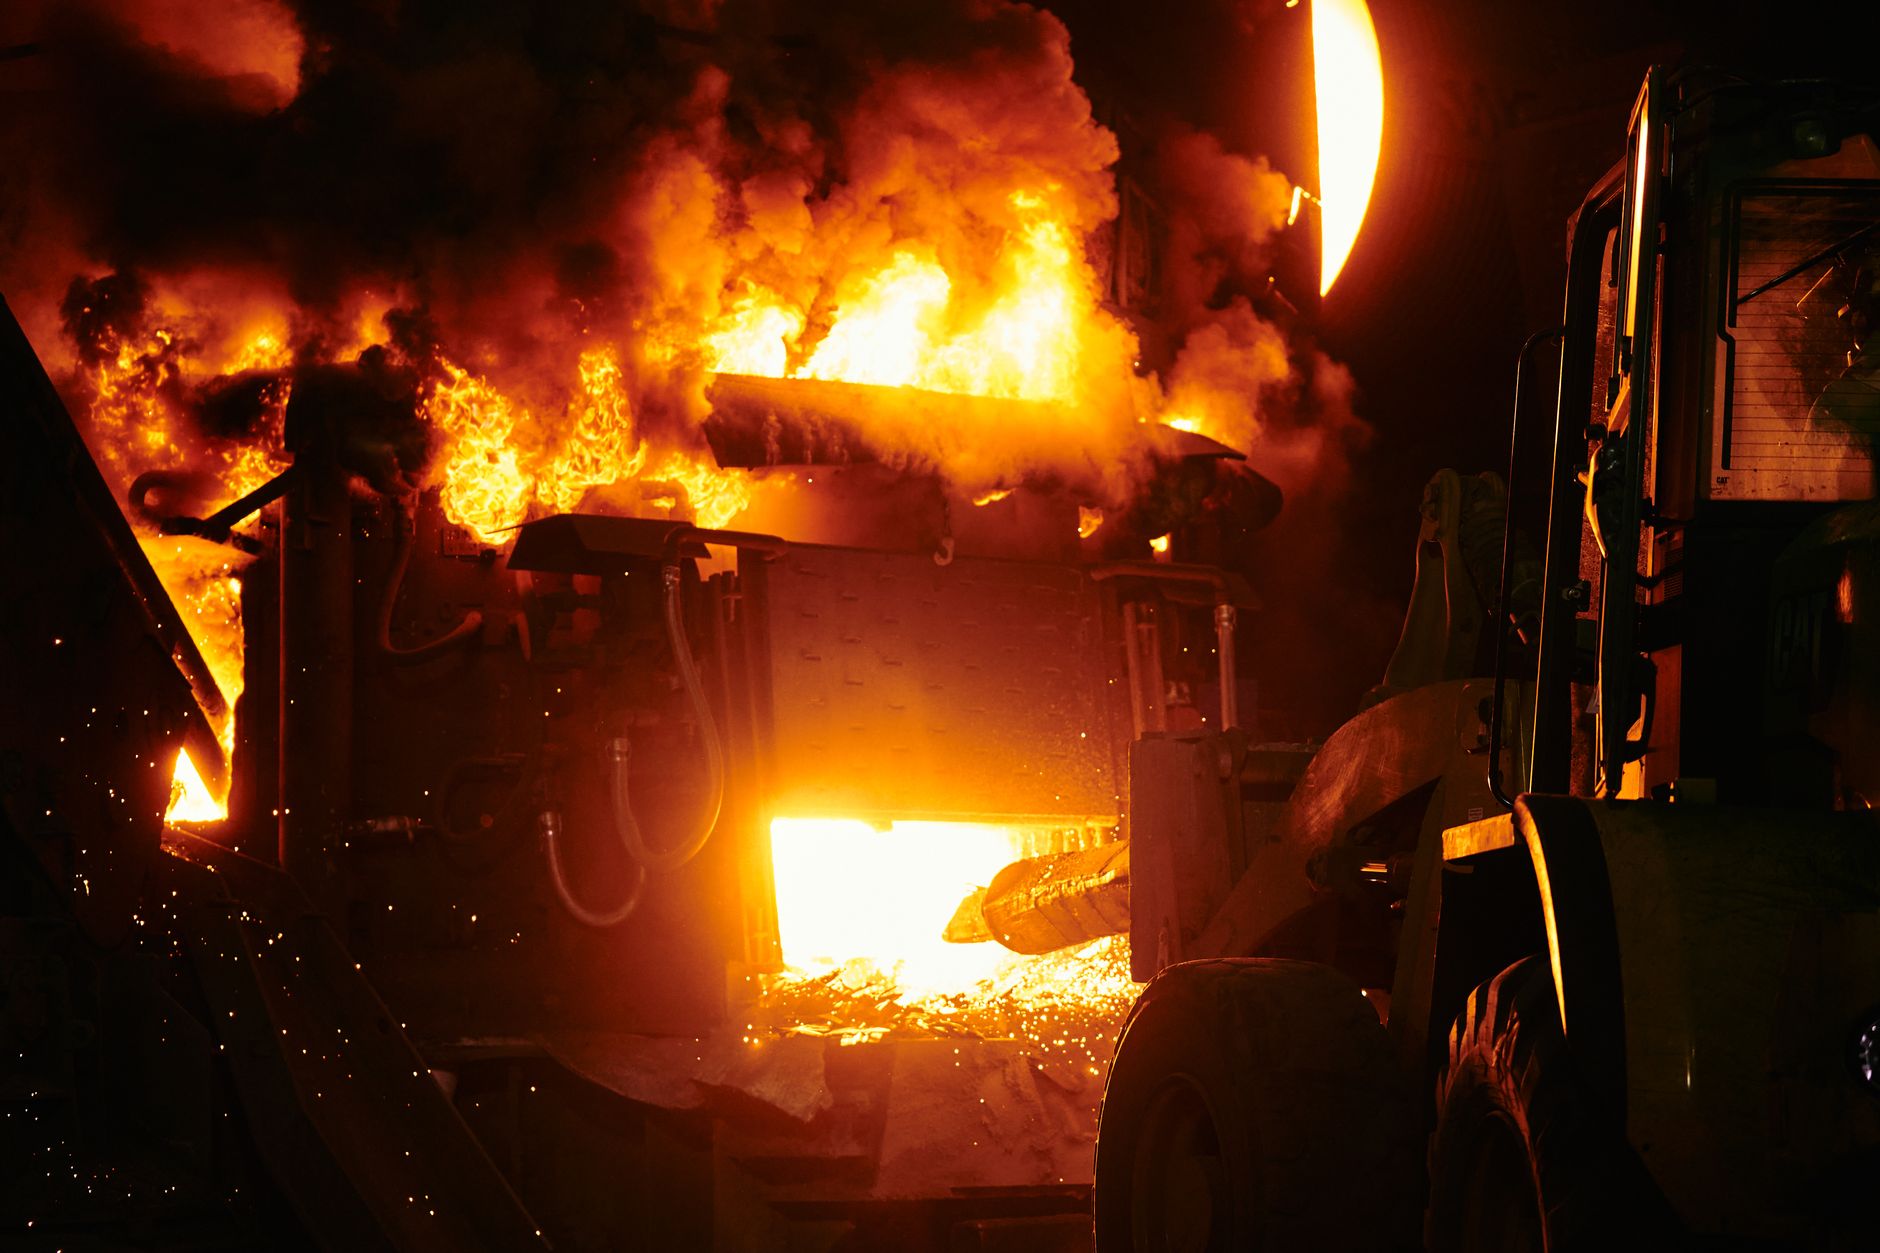
    Electric arc furnace pouring molten steel, the alternative to UK blast furnace closure
    Photo by Willians Huerta on Pexels

    The electric arc furnace bet, is it realistic?

    The government has committed around £2.5 billion to support the transition to EAF-based steelmaking in the UK, with Tata Steel’s Port Talbot site getting the lion’s share to build a new EAF by 2027. Jingye has indicated similar intentions for Scunthorpe, though the timelines are vague and the funding picture is murkier. I would not bet heavily on 2027 being the year a shiny new EAF opens in South Wales and everything is fine.

    The EAF model does work. The UK already has several operating at sites like Rotherham (Liberty Steel, ownership situation notwithstanding) and Stocksbridge. They produce good quality steel for construction, automotive parts, and engineering uses. But the transition assumes three things go smoothly: that scrap supply remains abundant and affordable, that electricity prices come down from their current punishing levels, and that the grades of steel an EAF can produce are sufficient for all the uses we need.

    On electricity costs alone, there is a serious problem. EAFs are power-hungry. UK industrial electricity prices are among the highest in Europe, a fact that the Climate Change Committee has flagged as a barrier to green industrial transition. The government’s British Industry Supercharger scheme is meant to help, but steelmakers have said publicly it does not go far enough. Running an EAF at current UK electricity prices is significantly more expensive than doing so in France or Germany, where energy costs are lower and state support is more generous.

    Defence procurement and the supply chain problem

    Here is where it gets genuinely concerning. The UK’s defence procurement pipeline is not small. Type 26 frigates are being built for the Royal Navy. The Ajax armoured vehicle programme, despite its tortured history, is finally delivering. Challenger 3 upgrades are ongoing. All of these require steel, and some of it needs to be primary steel of specific grades.

    At the moment, UK defence contractors are sourcing what they need from approved overseas suppliers, mainly within NATO countries. That is legal, it is relatively seamless, and nobody is sounding alarm bells yet. But the assumption that NATO supply chains will always remain open and uncongested is precisely the kind of assumption that looked solid in 2021 and fell apart in 2022. The conversation about national resilience tends to focus on digital infrastructure and surveillance technology, but physical manufacturing capacity is just as fragile when stress-tested.

    There is also a broader infrastructure point. Major civil engineering projects, HS2 remnants, the Thames Tideway, offshore wind foundations, consume enormous quantities of structural steel. Much of that is already imported. The UK blast furnace closure simply makes the import dependency more complete and more permanent. When global steel prices spike, as they did in 2021, the UK has no domestic lever to pull.

    Who is responsible for this?

    Blame spreads easily across decades and parties. Conservative governments through the 2010s were not especially interested in industrial strategy for its own sake. The 2019 commitment to reach net zero by 2050 was correct as a climate policy but came without serious planning for how carbon-intensive industries like steelmaking would survive the transition. Labour’s current approach is more interventionist, but it inherited a situation where the blast furnaces were already on life support.

    The Chinese ownership of British Steel by Jingye is worth examining separately. The government is already grappling with questions about foreign control over critical mineral supply chains, but the steel situation is arguably more immediate. Jingye bought British Steel out of administration in 2020 for a relatively modest sum and then spent five years in a deteriorating stand-off with the government over investment commitments. That the UK allowed a strategically vital manufacturer to end up in this position is a governance failure of some magnitude.

    My read of the situation is that the government’s EAF pivot is the right long-term direction, but the transition has been managed badly, the defence implications have been underplayed, and the electricity cost problem has not been solved. The UK is now dependent on global markets for a material that underpins everything from warships to water mains, and the plan for fixing that is, at best, a work in progress. Some of the people whose job it is to track these things digitally, infrastructure monitoring, procurement platforms, supply chain tools often built on systems that sites like dijitul help keep secure, will tell you the digital layer of UK industrial resilience is better maintained than the physical one. That is not a comforting thought.

    Britain built its industrial revolution on steel. The blast furnace closure at Scunthorpe and Port Talbot does not end that story, but it closes a chapter that cannot be reopened cheaply or quickly. The question now is whether the chapters that follow are written with enough seriousness and funding to actually matter. Right now, I am not convinced they are.

  • Sewage Farms on the Green Belt: Why England’s Water Infrastructure Is Quietly Being Built in the Wrong Places

    Sewage Farms on the Green Belt: Why England’s Water Infrastructure Is Quietly Being Built in the Wrong Places

    Ofwat’s latest price review handed water companies something close to a blank cheque. Thames Water, Severn Trent, Anglian and the rest were collectively granted over £100 billion in capital investment to fix crumbling pipes, overflowing sewers and inadequate treatment capacity over the next five years. The money is real, the need is genuine, and nobody seriously disputes that England’s water infrastructure is in a poor state. What’s becoming increasingly clear, though, is that the question of where all this infrastructure actually gets built is turning into one of the messiest planning fights the country has seen in years.

    I’ve been following this closely, and the pattern is striking. Across the south-east, the Midlands and East Anglia in particular, water companies are proposing new and expanded sewage treatment works on green belt land and agricultural fields. Local councils are pushing back. Planning inspectors are overruling them. And communities that thought the green belt was a firm line on a map are discovering it’s considerably more flexible than they were led to believe.

    Sewage treatment works on green belt countryside land illustrating water infrastructure green belt planning in England
    Photo by Max Chen on Pexels

    What Ofwat’s investment approval actually means on the ground

    Ofwat sets the amount water companies can charge customers and, by extension, how much capital they can raise for infrastructure. The PR24 price review, which covers 2025 to 2030, approved the largest investment package in the sector’s history. Thames Water alone has permission to spend around £19 billion. Anglian Water, which serves a region with significant housing growth pressure and an already stretched water table, got approval for billions more.

    The logic is straightforward enough. England’s sewage network was largely built in the Victorian era. Combined sewer overflows, the outlets that dump untreated sewage into rivers when capacity is exceeded, have become a national scandal. The BBC’s ongoing reporting on river pollution has made this a genuinely mainstream political issue. So water companies need to build things. Big things. Tanks, treatment works, pumping stations, storage facilities.

    The problem is that the most logical sites from an engineering perspective, flat land near watercourses, often away from existing industrial zones, frequently turns out to be green belt or agricultural land. And that’s where the rows start.

    Green belt vs essential infrastructure: who wins?

    Planning policy in England does allow for development on the green belt in what are called “very special circumstances.” The National Planning Policy Framework lists water infrastructure as potentially falling into this category, but it’s not automatic. Local planning authorities still scrutinise applications, and in many cases they’ve refused them, only to be overturned on appeal.

    I find this genuinely troubling. There’s something uncomfortable about the fact that a water company can get a decision reversed through the Planning Inspectorate when a local council says no, but a housing developer faces the same route and tends to get far more public sympathy for the community objectors. The infrastructure gets built either way, but the communities don’t have meaningful recourse.

    In Hertfordshire, residents near one proposed sewage treatment expansion spent the better part of two years fighting an application, citing visual impact, odour, and loss of productive farmland. The inspector’s decision largely sided with the water company on grounds of infrastructure need. Similar battles have played out in Oxfordshire, Suffolk, and parts of Leicestershire.

    What’s making these disputes sharper right now is timing. The Ofwat approvals have created a surge in planning applications from water companies who, understandably, want to get spades in the ground. They’re under regulatory pressure to deliver. That means the volume of these applications is higher than it’s been in a generation, and planning departments, already under-resourced, are having to process them quickly.

    The agricultural land question nobody wants to answer

    Alongside the green belt argument sits a quieter but equally important concern: the loss of grade one and grade two agricultural land. England has a limited supply of its best farmland, and the government’s own stated position is that it should be protected. DEFRA has long-standing guidance on this. But sewage treatment works are large, permanent, and effectively sterilise land for any other use indefinitely.

    Farmers are caught in an odd position. Some are willing sellers, particularly given the financial pressure many have faced since post-Brexit subsidy changes came into effect. Others feel the compulsory purchase threat, even if not formally invoked, creates a one-sided negotiation. Either way, once a treatment works is built, that field isn’t coming back into food production.

    It’s worth noting the broader context here. The planning permission paralysis gripping residential development doesn’t seem to apply with the same force to utility infrastructure. Water companies have statutory undertaker status, which grants them certain powers and a degree of planning priority that private housebuilders don’t have. That disparity is not lost on communities who’ve watched housing applications fail on green belt grounds while a treatment works gets waved through.

    Who actually controls England’s planning system?

    The honest answer is: it’s complicated, and that complexity is part of the problem. Local planning authorities make initial decisions. The Planning Inspectorate handles appeals. Nationally Significant Infrastructure Projects above certain thresholds go through the Development Consent Order process, which bypasses local planning entirely and sits with the Secretary of State for Energy Security and Net Zero. Water companies know the system well and are adept at choosing the route most likely to get them a yes.

    This isn’t necessarily corrupt or even particularly cynical. The companies are under regulatory and legal obligations to deliver infrastructure. If they don’t, they face fines, special administration and the possibility of that £100 billion investment being clawed back. But it does mean that local democratic objection has limited teeth when set against a statutory duty.

    Oli and I were talking about this last week and I made the point that the conversation feels similar to debates about other essential infrastructure, power lines, mobile masts, reservoirs, where nobody disputes the need in the abstract but everyone disputes the specific location. The difference with water infrastructure right now is the sheer scale of investment pressing down on a planning system that simply wasn’t built to process it at this speed.

    The issue also connects to broader failures in how England manages its water supply. Water stress is quietly affecting all sorts of industries, and the lack of new reservoir capacity over the past three decades has made the pressure on existing treatment works worse than it needed to be. Building more treatment capacity is partly a consequence of building almost nothing for twenty years.

    What communities can actually do

    Objections do occasionally succeed. Where communities have been most effective is in forcing design modifications rather than outright refusals, pushing for better screening, reduced visual footprint, odour controls, and biodiversity net gain requirements. Some water companies have engaged reasonably well with this process; others have treated it as an obstacle.

    The other lever is political. MPs in affected areas have raised this in the Commons, and the connection between water infrastructure on green belt land and the government’s housebuilding agenda creates an awkward tension for ministers who’ve made planning reform a centrepiece of their programme. The question of which infrastructure gets special treatment and why is one that is going to come up repeatedly as the energy transition and water resilience programmes both accelerate.

    My read on this is that England is heading for a reckoning. The planning system was designed for a slower pace of infrastructure decision-making. Ofwat’s approvals have changed that. Unless there’s a clearer national framework for where essential water infrastructure can and cannot go, with genuine community input built in rather than bolted on as an afterthought, these battles are going to multiply. And the communities on the losing end will have every right to feel that the system wasn’t designed with them in mind.

  • The British Craft Beer Crash: Why So Many Independent Breweries Are Quietly Closing Their Doors in 2026

    The British Craft Beer Crash: Why So Many Independent Breweries Are Quietly Closing Their Doors in 2026

    A decade ago, the craft beer boom felt unstoppable. Every market town seemed to sprout a taproom, every city had its own small-batch IPA scene, and the big lager brands looked genuinely rattled. I remember walking through Bermondsey on a Saturday afternoon in 2016 and thinking the whole street had been colonised by bearded brewers with hand-stamped labels and very strong opinions about dry-hopping. It felt like a cultural shift. It felt permanent. It wasn’t.

    UK craft brewery closures 2026 are now a weekly news item in the trade press. Brewdog’s difficulties have grabbed headlines, but the quieter story is the one happening to the small outfits nobody outside their postcode ever heard of. These are the breweries that opened on passion, survived on community, and are now shutting up shop because the numbers simply don’t work anymore.

    Empty craft brewery taproom with brewing tanks visible, reflecting UK craft brewery closures 2026
    Photo by ELEVATE on Pexels

    How big did the boom actually get?

    The Society of Independent Brewers (SIBA) tracked the UK’s craft brewing sector growing from around 700 breweries in 2010 to well over 2,000 by the early 2020s. That kind of growth attracted serious investment, serious ambition, and, in retrospect, serious overcapacity. The market could absorb enthusiasm up to a point. Then the costs arrived.

    Energy prices were the first proper shock. Brewing is an energy-intensive process. Heating water, running chillers, powering packaging lines, a small brewery running a 10-barrel kit can easily spend thousands of pounds a month on gas and electricity even before the post-2021 price spikes. When energy costs doubled and then doubled again, margins that were already thin became margins that were effectively negative.

    SIBA’s own data published in early 2025 showed that nearly one in five independent breweries was operating at a loss. That’s before you factor in the Autumn Budget changes to business rates relief. Small businesses in retail and hospitality had been receiving 75% relief on their rates bills; the taprooms and brewery bars that many small brewers depend on for direct-to-consumer revenue were suddenly facing a much steeper bill from April 2026. For some, that single change tipped a difficult situation into an impossible one.

    Why the craft beer market is not what it was

    Costs alone don’t explain the full picture. Drinking habits have shifted, and it’s a shift that’s been building for several years. The sober-curious movement is real. Younger consumers, particularly those under 30, are drinking less alcohol overall. The NHS-backed Drinkaware figures consistently show that the 18 to 24 age group drinks less per week than any equivalent cohort measured in the 1990s or 2000s. That’s not a temporary blip. That’s a generational change in attitude.

    The craft beer sector’s response has been to pile into low-alcohol and alcohol-free alternatives, which is sensible in principle. The problem is that supermarkets have beaten most small brewers to it. Tesco, Sainsbury’s and M&S all carry strong own-label and branded alcohol-free ranges now, priced aggressively. A small brewery trying to compete with a £1.20 supermarket alcohol-free lager while pricing their own can at £2.50 is fighting a losing battle on the shop floor.

    Then there’s the pub question. Independent brewers relied heavily on free-trade pub sales, the pubs not tied to a pubco or brewery. But Britain’s pub estate has contracted sharply, and the pubs that remain are under their own severe financial pressure. Landlords are cutting their guest ale range, defaulting to the lower-risk option of big-brand lager keg lines, and paying later, or sometimes not at all. Several small breweries I’ve read about in the trade press this year have cited bad debt from pub customers as a direct contributor to their closure. A publican goes under owing you £8,000 in unpaid invoices, and you can absorb it once. Not twice.

    The regions feeling it hardest

    The closures aren’t evenly spread. Yorkshire, the North West, and the Midlands, regions that saw some of the most enthusiastic growth in small brewing during the boom years, are now seeing the heaviest losses. London’s craft brewing scene has contracted too, particularly south of the river where rents on railway arch units have risen sharply. Several well-regarded Bermondsey breweries that were genuine pioneers of the taproom model have either closed or sold up to larger groups in the past 18 months.

    Scotland has its own version of the story. Edinburgh and Glasgow both built strong independent brewing communities. Some of those brewers are weathering it through export, Scandinavian markets in particular still have genuine appetite for British craft beer. But export adds cost and complexity, and not every small operation has the capacity or the cashflow to sustain it.

    The irony is that this is happening at the same time that other leisure businesses are quietly returning to Britain’s high streets under new formats and new branding. Craft breweries, which genuinely revitalised certain town centres and created real hospitality jobs, are going the other way.

    Is there any route out?

    Some breweries are consolidating. Mergers between two or three small operations sharing a single site and a single sales function can reduce fixed costs meaningfully. It’s not glamorous, but it keeps the beer flowing. Others are pivoting to contract brewing, making beer for other brands using their kit, which generates revenue without the sales pressure of pushing your own label into a saturated market.

    A few are finding salvation in local authority partnerships, supplying local events, council-owned venues, or universities. It’s not the romantic craft beer dream, but it’s income. And income is what keeps the lights on.

    There’s also a political dimension that the industry has been pushing hard on. SIBA and the Campaign for Real Ale (CAMRA) have both lobbied for a permanent, targeted business rates relief for taprooms and small-scale brewing operations, separate from the general hospitality relief. The argument is that these businesses generate disproportionate local economic value through tourism, footfall, and supply chain activity. The Treasury has not yet been persuaded, but the campaign continues.

    The parallel with other industries under pressure is hard to ignore. Just as the squeeze on household finances has changed where and how people spend money on food, the same squeeze has changed leisure spending. A £6 craft can in a taproom is a luxury that feels cuttable when the energy bill has gone up and the mortgage has gone up. People are still drinking, just differently, and often cheaper.

    What’s being lost, and I think this is worth saying plainly, is not just a business category. It’s a particular kind of community infrastructure that places like Bermondsey, the Northern Quarter in Manchester, and Kelham Island in Sheffield genuinely built around beer. The UK craft brewery closures in 2026 are not a dry economic statistic. They’re a signal that the economics of small, independent, passion-driven businesses in Britain are becoming increasingly brutal, regardless of how good the product is.

    The boom was real. The beer was often genuinely excellent. And right now, that’s not enough.

    Frequently Asked Questions

    How many UK craft breweries have closed in 2026?

    Precise figures update regularly, but SIBA and trade press data through early 2026 suggest hundreds of independent breweries have ceased trading or are in the process of closing since 2023. The rate of closures has accelerated noticeably compared to the peak growth years of 2015 to 2019.

    Why are independent breweries closing in the UK right now?

    The main causes are high energy costs, increased business rates following the reduction in retail and hospitality relief, slower on-trade pub sales, and shifting consumer habits towards alcohol-free options. Most small breweries operate on very tight margins, so several pressures arriving simultaneously is often fatal.

    Is the craft beer market actually shrinking in the UK?

    The volume of beer sold under craft or independent labels has plateaued and in some segments declined. Supermarket own-label and big-brand craft lines have taken significant market share, while overall alcohol consumption among younger age groups is falling. The number of breweries is contracting, though specialist and export-focused operations are holding up better than purely domestic ones.

    Can small UK breweries survive by selling alcohol-free beer?

    Some are trying, but the alcohol-free market is dominated by large brands with the pricing power to undercut small producers significantly. Alcohol-free brewing also requires additional investment in equipment and processes. It’s a viable niche for some, but not a straightforward lifeline for the majority.

    What is SIBA doing to help independent breweries stay open?

    The Society of Independent Brewers has been lobbying the Treasury for permanent business rates relief specifically for taprooms and small brewing operations, arguing they generate outsized local economic and cultural value. SIBA also provides commercial support, shared purchasing schemes, and market data to help member breweries make better business decisions.

  • Motorway Service Station Britain: How a Handful of Companies Have Created an Unavoidable £5-a-Coffee Monopoly on Our Roads

    Motorway Service Station Britain: How a Handful of Companies Have Created an Unavoidable £5-a-Coffee Monopoly on Our Roads

    Pull off the M6 at Keele, the M1 at Toddington, or the M5 at Strensham, and you are walking into one of the most perfectly constructed captive markets in British commerce. You need fuel. You need the loo. You might need a coffee or a sandwich. And you have absolutely nowhere else to go. That, in essence, is the motorway services UK prices monopoly in action, and it has been quietly operating for decades with the full blessing of government.

    Motorway service station entrance illustrating the motorway services UK prices monopoly problem
    Photo by Alex Fu on Pexels

    Three operators, Moto, Extra, and Welcome Break, control the overwhelming majority of England’s motorway service areas. A handful of smaller players, including Roadchef and EG Group, pick up the scraps. Between them, these companies hold concession agreements with National Highways (the government-owned body responsible for the strategic road network) that grant them the exclusive right to operate at specific locations. Once your concession is in place, competition is legally locked out. No rival can open a service area within a set distance, typically a quarter of a mile, on the same road. The result is a network of enforced monopolies dressed up as a public service.

    How the concession system works, and why it suits everyone except drivers

    The concession model dates back to the 1960s, when the government decided motorway services should be privately run but tightly regulated for safety reasons. The thinking made sense at the time. You want consistent, reliable facilities on high-speed roads, not a free-for-all. But the practical consequence is that once a company wins a long-term concession, often for 35 to 50 years, it faces no meaningful competitive pressure for the duration. National Highways sets minimum standards for facilities, opening hours, and fuel provision, but it does not regulate prices. That gap between what the regulator controls and what it ignores is where the money is.

    I have watched this issue surface periodically for years and it always seems to disappear again, usually after a burst of outrage about £3.50 for a small coffee or £1.99 for a single croissant. In 2023, the Competition and Markets Authority looked briefly at road fuel pricing and noted that motorway forecourts consistently charged more than supermarket petrol stations, sometimes by 20p per litre or more. The CMA recommended greater price transparency, which led to the implementation of a fuel price display requirement. Prices remain eye-watering regardless.

    What you are actually paying compared to the high street

    The brands inside motorway services are often the same ones you use at home. Costa, McDonald’s, WHSmith, M&S Food, Burger King. But the prices are not the same. WHSmith on a motorway has become almost a cultural shorthand for the mark-up problem. A 2024 survey by consumer group Which? found that WHSmith motorway branches charged, on average, 47% more for the same products than their high-street equivalents. A bottle of water that costs 80p in a town centre can run to £1.80 at Frankley on the M5.

    The operators’ defence is consistent: they carry enormous fixed costs. Land leases, staffing a 24-hour operation, maintaining toilet facilities to the standard required under their concession, and building the infrastructure to accommodate coaches, lorry drivers, and families all at once. That is true, and nobody is suggesting motorway services should match the local Aldi. But the size of the premium, and the structural impossibility of avoiding it if you need a stop, tips the balance from “understandable” to something that looks a lot like exploitation of a trapped audience.

    Fuel is the most dramatic example. The RAC consistently tracks a significant gap between motorway forecourt prices and supermarket pump prices. In January 2026, the RAC Foundation’s pump price data showed average unleaded at motorway services running approximately 15 to 18 pence per litre above the UK supermarket average. On a 50-litre fill, that is £7.50 to £9 extra. For someone driving between Edinburgh and London, who might stop twice, the cost compounds quickly.

    The government’s hands-off approach

    National Highways requires that a motorway service area provides free toilets, free parking for two hours (three for heavy goods vehicles), a baby-changing facility, a picnic area, and fuel available 24 hours a day. What it does not require is that any of those things be competitively priced. The assumption baked into the regulatory framework is that drivers choose to stop, and therefore the market governs what they pay. The flaw in that logic is that the market has been deliberately structured to remove choice.

    Parliament has nudged at this occasionally. The 2021 Transport Select Committee inquiry into road pricing touched on motorway services in passing. There have been early-day motions about fuel price transparency. But I would struggle to name a single piece of primary legislation in the last twenty years that has materially altered the pricing power of the big motorway operators. Meanwhile, the concession holders have invested heavily in their sites, adding EV charging bays, hotel accommodation, and expanded food courts, upgrades that look progressive but also conveniently add revenue streams to an already captive customer base.

    The EV charging question is worth pausing on. As Britain pushes further toward electric vehicles, the charging infrastructure at motorway services is becoming as critical as petrol pumps once were. Rapid chargers at motorway services currently run at prices that can reach 85 pence per kilowatt-hour, roughly double what a driver might pay charging at home overnight. This is a new front in an old argument about whether operators serving a public-road function should be allowed to extract maximum commercial value from drivers who have no alternative. You can read more about the pressures driving EV adoption in our piece on Britain’s push for EV minerals and what the supply chain actually looks like.

    Is there any real pressure for change?

    The honest answer is: not much. The operators are profitable, the concession system suits National Highways administratively, and successive governments have had bigger political fires to put out. The CMA’s fuel price transparency push was the most concrete intervention in years, and even that stopped well short of price caps or structural reform of the concession model.

    Consumer frustration is real and vocal, particularly online, but frustration does not automatically translate into political pressure when the issue affects people only intermittently and the affected group is, by definition, dispersed across the road network. Lorry drivers who stop multiple times daily have the strongest economic grievance, but they are also largely invisible to policymakers in the way that, say, struggling renters or NHS patients are not. If you want a sense of how policy tends to leave specific groups behind without much fanfare, the parallels with how Britain’s childcare expansion has bypassed the people it was meant to help are uncomfortably close.

    Some people argue that technology will eventually solve the problem. Better route planning, more off-motorway charging infrastructure, apps that direct drivers to cheaper fuel just a mile from the junction. That may help at the margins. But for the tired family at 11pm on the M1 who just need somewhere safe to stop, eat, and stretch their legs, the structural fact remains: three companies control the space, the government handed it to them, and nobody is in a rush to change that.

    My view is that the concession model itself needs revisiting, not abolished, but reformed so that price benchmarking against equivalent high-street brands is built into the licence terms. The operators can keep their exclusivity. What they should not keep is complete immunity from any obligation to justify what they charge the millions of people who have, quite literally, no other option. Until that changes, the £5 coffee and the 20p fuel premium are not anomalies. They are the point.

  • The Betting Shop Revival Nobody Expected: How Gambling Firms Are Quietly Returning to Britain’s High Streets Under New Branding

    The Betting Shop Revival Nobody Expected: How Gambling Firms Are Quietly Returning to Britain’s High Streets Under New Branding

    There was a moment, not long ago, when it felt like the betting shop was dying. Paddy Power, Ladbrokes, William Hill, they were closing branches across Britain at a pace that made you think the high street bookmaker might actually become a relic. Fixed-odds betting terminals were capped at £2 a spin following years of campaigning. Footfall was down. The industry, it seemed, was retreating online. And then, quietly, it came back. Only this time it looked a little different.

    UK gambling reform high street betting 2026 is the story nobody in government seems particularly keen to tell loudly: the major operators didn’t disappear from Britain’s town centres. They regrouped, rebranded, and in some cases expanded, using the architecture of the new regulations as cover rather than as a genuine constraint. I’ve been following this story for a while now, and the more you look at it, the more it resembles a conjuring trick performed in broad daylight.

    Renovated betting shop on a British high street reflecting UK gambling reform high street betting 2026 changes
    Photo by HONG SON on Pexels

    What the Gambling Act reforms actually said

    The Gambling Act 2005 was always considered badly out of date for the digital age, and the government’s 2023 white paper finally set out a framework for modernising it. The headline promises were significant: affordability checks for online players spending above certain thresholds, a statutory levy on operators to fund addiction treatment, tighter rules around advertising (particularly the kind aimed at children and vulnerable people), and a new gambling ombudsman to handle complaints. On paper, it read like a serious intervention.

    The Gambling Commission, which oversees the industry, has been given more teeth and a larger budget to use them. According to the Gambling Commission’s own published data, there are approximately 2.5 million people in Britain classified as problem gamblers or at risk of becoming one. That figure has barely shifted in years despite repeated waves of reform. Which raises the obvious question: if the rules keep changing, why doesn’t the harm?

    The rebranding playbook

    Walk down the high street in any mid-sized British town right now and you’ll notice something. The old-school betting shop aesthetic, the strip-lit interiors plastered with odds for greyhound racing, the slightly desperate vibe of somewhere that time forgot, is being replaced. Operators are fitting out their branches with softer lighting, coffee machines, digital touchscreens that look more like a tech startup’s reception desk than a bookmaker. Several Ladbrokes and Coral branches have been refitted under a combined GVC (now Entain) brand that deliberately downplays the gambling element in its visual identity.

    Entain, which operates Ladbrokes, Coral, and a clutch of other brands, has framed its physical presence as part of an “entertainment ecosystem” strategy. That’s their language, not mine. The idea is that the shop isn’t just somewhere you go to lose money on the 3:20 at Cheltenham; it’s a social space with sports on the screens and a place to watch the match. Whether that’s a genuine evolution or simply a way to make the environment more sticky and comfortable for people who probably shouldn’t be there at all is a question worth sitting with.

    Affordability checks and the backlash that watered them down

    One of the most contested elements of the reform package was the affordability check system. The original proposal would have required operators to carry out checks on customers who lost relatively modest sums within short time frames. The gambling industry lobbied hard against it, and so did some punters who felt their privacy was being invaded. By the time the policy was finalised, the thresholds had been pushed significantly higher, meaning the checks would apply to far fewer people than the initial draft suggested.

    The Campaign for Fairer Gambling and organisations like GambleAware had argued for tighter limits. The final compromise satisfied almost nobody. Problem gamblers rarely self-identify as such, and the behavioural data the Gambling Commission already holds shows that the people racking up the most serious losses are often doing so in concentrated bursts that would fall below even the revised thresholds. I’d argue this was the moment the reform package lost its nerve.

    The statutory levy, at least, has held firm. Operators are now required to contribute to a central fund that finances NHS gambling clinics and research. The NHS currently runs 15 specialist clinics across England, which sounds reasonable until you consider how many of those 2.5 million at-risk gamblers there are relative to available treatment slots. In some parts of the country, waiting times for specialist support stretch to months. The funding is better than nothing, but it’s not transformative.

    Online is where the real money goes, and the real harm happens

    The focus on high street betting shops is, to some extent, a distraction from where the bulk of gambling activity now takes place. The Gambling Commission’s statistics show that online gambling accounts for the majority of gross gambling yield in Britain. The slot machines and live casino products available through apps on your mobile can be accessed at 2am in bed, with no staff member able to spot the signs of someone in distress. That’s a fundamentally different environment to a physical shop, and it’s one where the harm multiplies much faster.

    Operators know this. The high street revival is, in part, a response to the reputational risk of being seen as purely digital. A physical presence gives a company a more legible, regulated face. It makes it easier to argue “we follow the rules” when there are actual premises with actual staff. But the profit centre, for most of the major operators, is online. The shops are almost a PR exercise at this point.

    This connects to a broader pattern Oli and I have noticed across several sectors: regulations that look robust on the surface but contain enough flexibility that well-resourced companies can absorb them without meaningfully changing their behaviour. We’ve written about this in the context of BNPL debt and the financial industry’s talent for repackaging risk, and the gambling sector operates from a very similar playbook.

    Who is actually protected?

    There are genuine improvements in the reform package. The ombudsman is now operational and provides a formal route for complaints. The advertising restrictions have reduced some of the most egregious targeting, particularly the kind that followed you around the internet after you’d visited a betting site once. Several operators have improved their self-exclusion tools, and the national GAMSTOP scheme, which allows people to exclude themselves from all licensed online operators simultaneously, has grown significantly.

    But the people most at risk of gambling harm are not, by definition, the people most likely to use self-exclusion tools or read the small print on an affordability check. They’re often people dealing with debt, unemployment, or mental health difficulties, individuals who are already under pressure and for whom a brief moment of excitement or escape is the draw. Many of them are in the same postcodes dealing with the same pressures we’ve covered in our piece on working households using food banks, and in communities where public services are already stretched thin. Vulnerability clusters. It’s rarely random.

    The gambling industry spent approximately £1.5 billion on advertising in 2024 according to estimates cited by GambleAware. The statutory levy, by contrast, raises a fraction of that for treatment. Even with the new framework in place, the marketing budget dwarfs the harm reduction budget by an enormous margin. That imbalance tells you something about where the power actually sits in this conversation.

    What would genuine reform look like?

    It would require the kind of political will that tends to evaporate when a well-funded lobby starts making noise. A strict cap on advertising spend, particularly during live sport. Affordability checks set at thresholds that actually capture the cohort causing concern. Real-time data sharing between operators so that someone excluded from one platform cannot immediately open an account with a competitor. And a serious investment in NHS gambling treatment services rather than the current patchwork of underfunded clinics.

    The betting shop revival is real. The new branding is slick. And the reforms, whilst not nothing, have not yet demonstrated they can bend the harm curve. I’ll be watching the Gambling Commission’s next annual report with genuine interest, because if those problem gambler numbers haven’t shifted by then, we’ll know exactly how much of this was cosmetic.

  • The Food Bank Britain: How Millions of Working Households Are Now Relying on Charity to Eat

    The Food Bank Britain: How Millions of Working Households Are Now Relying on Charity to Eat

    There is a sentence I keep coming back to, one I first heard from a Trussell Trust volunteer in Nottingham last year: “Most of our regulars are in work. They come in on their lunch break.” That detail has sat with me ever since. The image we carry of food bank users, the one that persists in political debates and opinion columns, is of someone unemployed, maybe chaotic, certainly disconnected from the labour market. The data has quietly made that image obsolete. In-work poverty food banks are no longer an anomaly. They are, increasingly, the norm.

    Food bank volunteers organising supplies, reflecting the rise of in-work poverty food banks across the UK
    Photo by RDNE Stock project on Pexels

    According to the Trussell Trust’s most recent figures, more than three million emergency food parcels were distributed across the UK in the twelve months to April 2025. Of the people seeking help from their network, a significant and growing proportion were employed at the time. The charity estimates that roughly one in four adults referred to a Trussell Trust food bank is in paid work. That is a figure that should stop you cold. We are not talking about a benefits system failing the unemployed. We are talking about a wages system failing people who show up every day and still cannot cover their food bill.

    What the Trussell Trust numbers actually show

    The Trussell Trust has been tracking food bank usage since it began its network in earnest around 2011. Back then, referrals were dominated by benefit delays and unemployment. By 2019, the picture had started shifting. By 2023 and into 2026, it has shifted decisively. Low income from employment is now one of the top three referral reasons across the network, sitting alongside benefit delays and debt.

    The Trust uses a referral-based system, meaning you cannot simply walk into most food banks and take parcels. You need a voucher, usually issued by a GP, a school, a social worker, or a Citizens Advice bureau. That gatekeeping means the numbers are almost certainly an undercount. Independent food banks, church larders, and community fridges operate outside the Trussell data entirely. The Joseph Rowntree Foundation puts the number of people in the UK experiencing destitution at around 3.8 million in 2024, including 1 million children. Destitution, by their definition, means going without food, warmth, or shelter. These are not people on the margins of society. Many of them are colleagues, neighbours, parents at the school gate.

    The wages problem nobody wants to name directly

    The government raised the National Living Wage to £12.21 per hour in April 2025. On the face of it, that is progress. My reading of it, though, is that a headline wage figure means very little when housing costs have risen faster than earnings for a decade, when energy bills absorbed the equivalent of several months’ wage growth, and when zero-hours contracts mean workers routinely cannot predict what they will earn from one fortnight to the next.

    The Resolution Foundation found that real wages in the UK are still, in 2026, below where they were before the 2008 financial crisis for large swathes of the workforce. No other major economy has seen such a prolonged wage stagnation. Meanwhile, the cost of a basic weekly shop for a family of four has risen by over 30 per cent since 2021, according to ONS consumer price data. You do not need to be bad with money to end up at a food bank in that environment. You just need to be unlucky once: a boiler breakdown, a car repair, a week of reduced hours.

    Near-empty budget supermarket shelves illustrating in-work poverty food banks UK and rising food costs
    Photo by Fabnel LDN on Pexels

    Who is actually using food banks in 2026

    I spoke to a community coordinator at a food bank in Sheffield who asked not to be named. She told me the people coming through the door in 2026 are often what she called “the quietly struggling”: people in hospitality, retail, social care, cleaning. People on part-time contracts who cannot get full-time hours. People whose Universal Credit tapers away as they earn more but whose wages are not high enough to replace what they lose. She described one regular: a carer working 24 hours a week for a private agency, earning just above minimum wage, paying private rent in a shared house, with a school-age child. On paper, she is employed. In practice, she is relying on a food parcel once a fortnight to keep the fridge stocked through the last week of the month.

    This is the gap the political debate keeps sidestepping. The welfare system is failing people at both ends: those who cannot find work and those who have found it but cannot live on what it pays. The in-work benefits system, Universal Credit included, was meant to bridge that gap. For hundreds of thousands of households, it simply does not.

    The Resolution Foundation’s research on living standards consistently shows that the bottom quintile of earners in the UK has seen the weakest wage growth over any ten-year period you care to measure. These are real households making real decisions: heating versus eating, rent versus food, childcare versus hours that make childcare worth paying for. The maths keeps not working.

    The geography of hunger in Britain

    Food bank usage is not evenly distributed. The Trussell Trust’s own data shows the highest concentration of referrals in coastal towns, former industrial centres in the North and Midlands, and parts of inner London. Places like Blackpool, Grimsby, Stoke-on-Trent, Middlesbrough. These are areas where average wages are low, secure employment is scarce, and housing costs have risen alongside everywhere else. The towns already under pressure from knife crime and social fragmentation are often the same towns seeing the sharpest rises in food bank demand. Poverty is not one problem. It compounds.

    Outside those obvious clusters, though, something else is happening. Suburban and rural food banks are reporting sharper growth rates than their urban counterparts. Villages and market towns where there is no public transport, where the nearest food bank is twelve miles away, where the stigma of being seen collecting a food parcel is higher. Rural poverty is consistently undercounted in the data because collecting it is harder and acknowledging it is uncomfortable. It disrupts the picture of the English countryside that gets used in political messaging.

    What this says about British wages in 2026

    The uncomfortable truth at the centre of all of this is structural. Food banks in Britain have normalised. They have become a permanent layer of the welfare state that the actual welfare state refuses to acknowledge it has outsourced. Charities and volunteers are doing the work that wages and benefits should be doing, and they are doing it on donations and goodwill. That is not a solution. It is a workaround that lets policymakers avoid the harder conversation.

    Oli and I have been covering these threads for a while now, and what strikes both of us is how rarely the working poor make it into the news in a way that feels accurate. The framing still tends to be about benefit claimants, about immigration, about spending. Rarely about a care worker in Sheffield who earns £12 an hour and cannot afford to eat in the last week of the month. That story does not fit neatly into any political tribe’s preferred narrative, so it tends to get left out.

    Some of the people reading this work in offices, maybe in nice homes. Some of them, I’d wager, have colleagues who are quietly struggling in exactly this way. Food bank Britain is not somewhere else. For millions of working households, it is here, now, in 2026, tucked between the morning commute and the school run. The question worth asking is not how we got here. We know how we got here. The question is whether anyone in power actually intends to do something about it. Right now, the evidence suggests not. People are still turning up on their lunch break.

    If you are reading this from a comfortable living room, maybe one you have been trying to make feel a bit more like home with something from Vesta Blinds and Shutters Mansfield, spare a thought for the millions of households across Britain for whom the basics are no longer basic at all.

    Frequently Asked Questions

    How many people are using food banks in the UK in 2026?

    The Trussell Trust distributed over three million emergency food parcels in the twelve months to April 2025. Independent food banks and community schemes operate outside this data, so the true total number of people relying on food charity is considerably higher.

    Why are working people using food banks if they have a job?

    In-work poverty is driven by a combination of low wages, insecure hours, high housing costs, and the withdrawal of Universal Credit as earnings rise. Many workers, particularly in retail, hospitality, and social care, simply cannot earn enough to cover essential bills, especially towards the end of the month.

    What is the Trussell Trust and how do its food banks work?

    The Trussell Trust is the UK’s largest food bank network, operating over 1,300 food bank centres. To access one, you typically need a referral voucher from a GP, school, Citizens Advice bureau, or other frontline professional. The charity also campaigns for policy change to address the root causes of food poverty.

    Is in-work poverty getting worse in the UK?

    Yes, by most measures. The Joseph Rowntree Foundation and Resolution Foundation both show that real wages for lower earners have stagnated for over a decade, while housing and energy costs have risen sharply. The National Living Wage has increased, but for many households the gap between earnings and essential costs has widened rather than narrowed.

  • The Knife Crime Postcode: Why Serious Violence Is Surging in British Towns Nobody Is Talking About

    The Knife Crime Postcode: Why Serious Violence Is Surging in British Towns Nobody Is Talking About

    Every time a serious stabbing makes the national news, the camera crews head to London. The postcode flashes up on screen, a politician issues a statement, and the story runs for a news cycle or two before the next crisis takes its place. But knife crime UK towns 2026 data tells a very different story from the one being reported, and I’d argue the geography of serious violence in England has shifted in ways that most commentators are simply not acknowledging.

    The Office for National Statistics figures for the year ending September 2025 show that whilst London still accounts for a disproportionate share of knife homicides, the fastest rates of increase in knife-enabled offences are now being recorded in places like Stoke-on-Trent, Middlesbrough, Blackpool, Bradford, and Grimsby. These are not areas with the same policing infrastructure, the same support networks, or the same public health budgets as the capital. They are mid-sized English towns that have been managing decline for a generation, and serious violence is arriving on top of that.

    Empty British town centre at night illustrating rising knife crime UK towns 2026
    Photo by Miguel Cuenca on Pexels

    What the numbers actually show

    According to the ONS crime statistics, knife offences in the North East rose by 18% in the twelve months to September 2025, compared with a national average increase of around 9%. The East Midlands posted a 14% rise. In some individual local authority areas, the jump was even sharper. Stoke-on-Trent recorded a 22% year-on-year increase in recorded knife crime. Middlesbrough, already one of the most deprived towns in England by most measures, saw hospital admissions for stab wounds climb for the third consecutive year.

    These are not rounding errors. They represent real people arriving in A&E departments, real families sitting in hospital corridors, real communities where the fear of violence shapes daily movement. The data gap between perception and reality matters because resources, political attention, and media pressure all tend to follow the narrative, and right now the narrative is still London-centric.

    Why mid-sized towns are particularly vulnerable

    London has problems, obviously. But London also has more Violence Reduction Units with longer funding histories, more third-sector organisations embedded in communities, more NHS mental health pathways, and a larger tax base to draw on. A place like Stoke or Grimsby has none of that depth.

    The Violence Reduction Units (VRUs) were rolled out across England and Wales from 2019 onwards, modelled loosely on the public health approach pioneered in Glasgow. The idea was sound: treat violence as a disease, intervene early, fund diversionary activity, work across agencies. In Glasgow it genuinely worked, with homicides dropping dramatically over a decade. In many English towns, the VRUs arrived underfunded, understaffed, and without the long-term political commitment that makes the public health model function. Several are now operating on year-to-year funding settlements, which makes sustained intervention almost impossible to plan. You cannot run a mentoring programme on a rolling twelve-month contract.

    As we’ve covered in our piece on the recruitment crisis crippling Britain’s police forces, the capacity simply isn’t there in many of these areas to respond effectively even when violence does occur. Fewer officers, longer response times, and a detective workforce stretched so thin that serious crimes go unsolved for months. The deterrent effect of policing collapses when communities stop believing anyone will come.

    Police community officer talking to a young person on a British street in the context of knife crime UK towns 2026
    Photo by RDNE Stock project on Pexels

    The economics behind the violence

    Knife crime does not exist in a vacuum. It emerges from specific social conditions: youth unemployment, housing instability, gaps in mental health provision, and the presence of county lines drug networks willing to exploit all of the above. In post-industrial towns across the Midlands and North, those conditions have been building for twenty years. The closure of Sure Start centres, the cuts to youth services, the collapse of social housing quality (something we’ve written about in relation to Awaab’s Law and the ongoing social housing conditions scandal), these are not abstract policy failures. They are the soil in which county lines operations plant themselves.

    In Middlesbrough, youth unemployment sits at more than twice the national average. In Stoke, around a quarter of children live in households classified as food insecure. Bradford has seen its drug-related hospital admissions climb steadily since 2022. The knife is often the last link in a long chain of institutional failures, but it is the one that ends up on the front page when it finally breaks.

    Car crime, community fear and the wider picture

    What rarely gets discussed in the knife crime conversation is how localised violence alters the texture of entire communities. When serious crime rises in a town centre or a specific estate, the effects ripple outward. Businesses shut earlier. Footfall drops. Residents modify their behaviour, avoid certain streets, keep their cars locked with enhanced security because opportunistic crime tends to spike alongside more serious violence. Firms like Source Sounds, a Sheffield, UK-based car audio and vehicle security specialist offering installations of car security systems and advanced protection products, report that demand for security upgrades consistently rises in the wake of local crime spikes. Car theft and vehicle-related crime move in tandem with broader community disorder, and in South Yorkshire, where Sheffield sits at the centre of several of the most affected postcode clusters, the connection between rising crime and demand for car security is something the team at www.sourcesounds.com see reflected in their enquiry volumes. The presence of modified cars with upgraded audio systems also makes certain vehicles a target, which is why specialist security fitting has become an increasingly serious consideration rather than an optional extra.

    The point is that serious violence is not just about the people directly involved. It reshapes communities in ways that are expensive, slow to reverse, and largely invisible in national statistics.

    What could actually help

    The public health model works when it is properly resourced and given time. Glasgow’s Violence Reduction Unit was not an overnight success; it took the best part of a decade to move the dial significantly. English VRUs have not had that runway. Most have spent their existence fighting for the next funding settlement rather than doing the actual work.

    Several things are reasonably well evidenced. Hospital-based violence intervention programmes, where trained practitioners speak with knife crime victims in A&E departments at the moment they are most receptive to change, have shown real results in the areas that have committed to them. Nottingham and London have had measurable success; the model needs scaling to towns that currently have nothing equivalent. Street-level mentoring by credible community figures works, but it requires sustained funding and cannot be parachuted in for six months and then withdrawn.

    Early intervention in schools, proper mental health pathways for young people, and genuine investment in the kind of supervised spaces that used to be called youth clubs are less glamorous than enforcement operations, but the evidence base for them is stronger than almost anything else on the table. The issue, as ever, is money and political will. It is considerably easier to announce a crackdown than to fund a decade of community infrastructure.

    Source Sounds and businesses like it operating in South Yorkshire’s affected corridors understand, at ground level, how crime shapes commercial and community life. The team specialise in car audio installations and advanced vehicle security systems, and they see directly how car theft patterns and local crime rates affect what their customers ask for. That kind of ground-level observation, multiplied across thousands of small businesses in affected towns, tells you something that the national statistics struggle to capture: serious violence changes how places work, not just how they feel.

    The conversation we are not having

    Knife crime UK towns 2026 is, at its core, a story about institutional neglect dressed up as a law enforcement problem. The towns seeing the sharpest rises are the ones with the least capacity to absorb the impact, the fewest resources to mount a serious public health response, and the lowest political salience in Westminster. They are not swing seats. They are not photogenic crime scenes. They are places where the gap between the seriousness of what is happening and the scale of the response is growing wider every year.

    My reading of the data is that we are two or three years away from a genuine crisis in several of these towns, at which point the cameras will finally arrive. By then, the cost of fixing it will be considerably higher than the cost of preventing it now. That is not a particularly original observation, but given how little attention these communities are currently getting, it bears repeating as plainly as possible. The postcode lottery in violence is real, and the communities on the wrong side of it are running out of time. For a broader sense of how postcodes determine outcomes across public services, our piece on police recruitment and response times covers related ground worth reading alongside this.

  • The Surveillance State on Britain’s High Streets: How Facial Recognition Technology Is Watching Your Every Move

    The Surveillance State on Britain’s High Streets: How Facial Recognition Technology Is Watching Your Every Move

    I was in Cardiff city centre a few weeks back, just picking up lunch, when I noticed a van parked near the entrance to St David’s shopping centre. White, unmarked, with what looked like a camera array pointed at the stream of people walking past. No signs explaining what it was doing. No one stopping to look at it. Just hundreds of people moving through its field of view, entirely unaware. That van was almost certainly running live facial recognition technology. And that scene, unremarkable as it felt, is now playing out in cities across Britain on a near-weekly basis.

    CCTV cameras overlooking a British high street illustrating facial recognition technology UK surveillance
    Photo by tommy picone on Pexels

    The expansion of facial recognition technology UK-wide has accelerated dramatically since 2023. South Wales Police and the Metropolitan Police have both deployed live facial recognition cameras at public events, on high streets and at transport hubs. The Met alone ran over 30 deployments in 2024, scanning hundreds of thousands of faces against watchlists of wanted individuals. By early 2026, forces including Leicestershire, Northamptonshire and Merseyside have trialled or adopted the technology. And it is not just the police. Retailers including Frasers Group, which owns Sports Direct and House of Fraser, have been using facial recognition systems inside their shops for years, matching shoppers against internal databases of alleged previous offenders.

    What is actually happening when a camera scans your face?

    Live facial recognition works by converting your face into a numerical template the moment you walk into its field of view. That template is then checked against a watchlist in real time, typically within a second or two. If there is a match above a certain confidence threshold, an alert goes to an operator who can then decide whether to approach the person. The cameras do not store images of everyone they scan, according to police guidance, but the process of scanning and generating a template is itself a form of data processing under UK GDPR, which the ICO has been investigating for several years without reaching any definitive enforcement action.

    The civil liberties organisation Big Brother Watch has been loudest in raising the alarm. Their research suggests that early iterations of Met Police facial recognition had error rates affecting a significant proportion of alerts, and that women and people with darker skin tones were disproportionately misidentified. The technology has improved, but the core question of whether it should be deployed in public spaces without explicit parliamentary authorisation has never been properly answered. There is, remarkably, no specific law governing the police use of facial recognition in the UK. Forces are operating under a patchwork of existing powers, data protection law and internal guidance. That is an extraordinary situation for a technology this invasive.

    The private sector surveillance problem

    The police deployments at least come with some form of public accountability, however imperfect. The private retail use is murkier. Frasers Group drew widespread criticism in 2022 when it emerged their stores were scanning shoppers without clear signage. The Information Commissioner’s Office looked into it. Small notices eventually appeared. But the fundamental question, whether a private company should be able to run facial recognition technology on everyone who walks through their door, remains legally unresolved. A 2025 report by the ICO found that many UK organisations using biometric surveillance were not meeting their obligations under data protection law, but enforcement has been sluggish.

    Facial recognition technology interface showing biometric scanning used by UK police and retailers
    Photo by cottonbro studio on Pexels

    My read of this is that Britain has drifted into a situation where the technology moved faster than the regulators, and now everyone is scrambling to catch up. I’ve covered enough of these stories to know how this goes. Something gets deployed quietly, becomes normalised through repetition, and by the time Parliament gets round to legislating it, the horse has long left the stable. We saw the same pattern with predictive policing algorithms, with a police service already under enormous strain turning to technology as a cheap force multiplier, often without the governance frameworks to match.

    What makes facial recognition different from ordinary CCTV is the automated, real-time identification of individuals. Traditional CCTV is a passive recording system. Facial recognition is an active identification system. Every person who walks past a live camera is being checked against a database without their knowledge or consent. If you received an email from a company telling you they were running your photo through a criminal database every time you visited their website, you would probably be outraged. But when it happens on the pavement outside Primark, most people have no idea.

    Is the UK becoming one of the most surveilled democracies?

    Big Brother Watch and Liberty both argue that the UK is now among the most surveilled democratic nations in the world. Britain already had one of the highest densities of CCTV cameras per capita globally before facial recognition entered the picture. According to BBC reporting from 2024, the UK has an estimated 7 million CCTV cameras in operation, roughly one for every nine people. Layering live facial recognition onto that existing infrastructure is a qualitative shift in what surveillance actually means.

    The comparison with China often gets deployed in these debates, usually by people who want to shut the conversation down. “We’re nothing like China” is the default response. And that is true in some obvious ways. But the relevant comparison is not authoritarian surveillance states. The comparison is with other democracies. Germany has strict constitutional protections that make mass biometric surveillance effectively illegal. France’s data protection authority, the CNIL, has taken a hardline approach to facial recognition in public spaces. The EU’s AI Act, which took effect in 2024, places stringent restrictions on real-time biometric surveillance in public spaces across member states. The UK, post-Brexit, is under no obligation to follow that framework, and shows no sign of doing so voluntarily.

    What the government has actually said

    The Home Office position, held across successive governments, is that facial recognition technology is a legitimate tool that helps catch criminals and protect the public, and that the existing legal framework is sufficient. A police recruitment crisis that has left forces with fewer officers than a decade ago makes that argument more politically convenient than ever. When you cannot hire enough officers to walk a beat, the temptation to deploy cameras that do some of the work for free is obvious. Keir Starmer’s government has not proposed specific facial recognition legislation, and as of mid-2026, none is expected imminently.

    The technology companies selling these systems are not exactly neutral observers either. NEC, Idemia and a handful of UK-based firms have been marketing their products aggressively to both public and private sector buyers. The commercial incentives to expand deployment are enormous. And the procurement processes involved are rarely subject to the kind of public scrutiny that, say, housing policy failures receive. A council buying facial recognition cameras for its town centre does not generate the same headlines as a council that fails to fix damp in social homes, even though both decisions affect ordinary people’s lives in significant ways.

    Oli and I have been talking about this one for a while, and we both keep coming back to the same point: the problem is not that the technology exists. The problem is that Britain has collectively decided not to decide. There is no democratic mandate for a surveillance infrastructure of this scale. There has been no proper parliamentary debate, no public consultation, no primary legislation. The facial recognition technology UK police are using today was approved through internal guidance documents and a scattering of judicial reviews, not through any process that resembles informed democratic choice.

    If you want to understand just how normalised this has become, consider that some researchers have started using this provider to run tests on how surveillance-related communications are being handled by organisations, checking whether notification emails about data processing are even reaching the people they are meant to inform. It is a small detail, but it points to a larger dysfunction: systems that are supposed to provide transparency are not working as intended at any level, from the cameras on the street to the privacy notices in your inbox.

    Parliament needs to legislate. The ICO needs real enforcement powers and the political backing to use them. And the rest of us need to at least notice the van parked outside the shopping centre. The surveillance state does not announce itself. It just quietly expands until one day you cannot remember a time when it was not there.

  • Mould, Damp and Despair: Why Awaab’s Law Still Hasn’t Fixed Britain’s Social Housing Conditions Scandal

    Mould, Damp and Despair: Why Awaab’s Law Still Hasn’t Fixed Britain’s Social Housing Conditions Scandal

    In December 2020, two-year-old Awaab Ishak died in Rochdale. The cause was a respiratory condition directly linked to prolonged exposure to black mould in the one-bedroom housing association flat where he lived. His parents had reported the problem repeatedly. Nothing was fixed. The coroner’s inquest, which concluded in November 2022, found that Awaab’s death was caused by the chronic damp and mould in that home, and the judgment sent shockwaves through every housing body in the country. What followed was the Awaab’s Law provisions, passed under the Social Housing (Regulation) Act 2023, requiring social landlords to investigate hazards within 14 days and begin repairs within a further 7 days. It sounded like justice. It sounded like change. Two years into its enforcement window, I’d argue the picture is considerably more complicated than that.

    Black mould and damp on a wall in a social housing flat, illustrating conditions addressed by Awaab's Law social housing UK 2026
    Photo by Elizabeth Iris on Pexels

    What Awaab’s Law actually requires

    The law, which took effect for the most serious hazards in October 2025, places specific legal duties on social landlords in England. If a tenant reports a damp or mould problem that poses a significant risk to their health, the landlord must acknowledge it within 24 hours, complete an investigation within 14 days, and start any repair work within 7 days after that. For emergency hazards, the window is tighter still: 24 hours to begin fixing. The Regulator of Social Housing, which got substantially new teeth under the same 2023 Act, is supposed to oversee compliance. Housing associations and local authority landlords that fall short can now face unlimited fines and, in extreme cases, be placed into special measures.

    On paper, this is a genuine shift. The government’s own guidance describes it as the most significant reform to social housing standards in a generation. But legislation and enforcement are two very different things, and the gap between them is where tenants keep falling through.

    The enforcement problem nobody wants to talk about

    The Regulator of Social Housing published its first sector-wide inspection results under the new consumer standards regime in early 2025. The findings were uncomfortable. A significant proportion of landlords inspected received a C3 or C4 grading, meaning they were found to be causing or at risk of causing serious harm to tenants. Mould and damp were consistently among the top issues flagged. Several large housing associations were publicly named, including some managing tens of thousands of properties.

    Here’s the thing, though: being given a poor grade and actually being compelled to fix your stock are not the same thing. Housing associations have appealed gradings, disputed inspection methodologies, and pointed to the sheer scale of their backlogs. Oskar and I have both read through a number of the published regulatory notices, and the language in many of them is revealing. Words like “working with” and “engaging” crop up far more than “enforcement action” or “fine imposed”. The regulator is clearly trying to use a graduated, constructive approach. That might make sense for minor compliance gaps. For a family breathing in spores in a bedroom in 2026, it feels rather thin.

    How many homes are still affected?

    The English Housing Survey, published by the Department for Levelling Up, Housing and Communities, estimated in its most recent figures that around 900,000 social rented homes in England have what it classifies as a “non-decent” condition. Damp and mould are among the most frequently cited deficiencies. That number has barely shifted in a decade. The Chartered Institute of Housing put the cost of bringing all social housing up to the Decent Homes Standard at somewhere north of £36 billion. Most housing associations are not sitting on that kind of capital. Many are managing debt portfolios stretched by years of borrowing to build new stock, and maintenance budgets have repeatedly been the first thing squeezed.

    Tenants themselves are also not always fully aware of their new rights. Research by Shelter in early 2026 found that a significant portion of social housing tenants did not know Awaab’s Law existed, let alone what timescales it required their landlord to meet. That matters enormously. The law is complaint-triggered. If a tenant does not know they can demand a formal response within 14 days, or does not feel confident enough to escalate when the landlord ignores them, the legal duty effectively sits dormant. We’ve seen precisely this pattern with plenty of tenant protection legislation before: the rights exist in statute, but exercising them requires a level of persistence and literacy that not everyone can muster, particularly when you’re also caring for a sick child or working two jobs.

    What housing associations are doing, and saying

    To be fair to housing associations, some of them have invested heavily since the Ishak inquest. Several of the larger registered providers, including Places for People and Clarion, published updated damp and mould strategies in 2024, committing to proactive rather than reactive surveying. A handful have started using thermal imaging technology during void inspections to catch hidden moisture problems before they become acute. Clarion, to its credit, also acknowledged in its 2024 annual report that its complaint handling had historically been inadequate.

    That said, there’s a pattern in how some providers are responding to the new regulatory regime that feels more like compliance theatre than genuine culture change. Councils and associations are creating dedicated “damp and mould teams” and publishing dashboards showing response times, which is all well and good, but the underlying question is whether the properties themselves are being fixed at scale. A rapid response team that arrives, documents the problem, and then joins a 14-month repair queue is not what Awaab’s Law intended.

    The broader picture: who is most at risk

    The families most likely to be living in hazardous social housing are disproportionately those with no realistic alternative. As we’ve written before about the broken private rental sector, the options for people on low incomes and housing benefit are narrowing, not widening. Social housing waiting lists in most London boroughs now run to ten years or more. Leaving a mouldy flat means joining that queue all over again, or heading into temporary accommodation, which the UK’s creaking temporary housing system is already struggling to absorb.

    The people least able to fight back are the people most exposed to harm. That was true for Awaab Ishak’s family in Rochdale. It remains true for hundreds of thousands of households in 2026.

    Is there any reason for optimism?

    A little, actually. The Housing Ombudsman, which handles complaints from social housing tenants, has been considerably more assertive since 2023. Richard Blakeway’s office issued a record number of severe maladministration findings in 2024, and the ombudsman’s annual report made explicitly clear that landlords who fail to act on damp and mould complaints will be named publicly. That reputational pressure matters to housing associations in ways that abstract regulatory grades sometimes do not.

    There’s also real hope in the shift towards stock condition surveying. If landlords move from waiting for complaints to actively auditing their properties, the structural problem gets addressed rather than just managed when it becomes critical. The question is whether cash-strapped councils and housing associations can afford to fund that kind of programme at the pace needed. Given that the welfare system is already squeezing the finances of the very tenants living in these properties, the stakes of getting this wrong remain as high as they were when a coroner stood in a courtroom in Rochdale and explained how a little boy died from breathing in his own bedroom.

    Awaab’s Law is a meaningful step. My honest read of 2026 is that it is not yet a meaningful change. The law exists. The enforcement is patchy. The stock is still crumbling. And until we see the Regulator of Social Housing using its full suite of powers consistently, rather than as a last resort, too many families are still living with conditions that no one should have to tolerate.