Author: Oskar

  • Council Tax Reform UK 2026: Why the 1991 Bands Must Go

    Council Tax Reform UK 2026: Why the 1991 Bands Must Go

    Council tax reform UK 2026 is overdue because England’s bands still rest on what homes were worth on 1 April 1991, and no government has dared to revalue them since. The result is a bill that bears little relation to what your house is worth today, and you can only do a few things about it as an individual. Here is why it has stuck, and what you can do meanwhile.

    Who is being ripped off by the 1991 bands?

    The bands run from A to H in England, with Band A covering homes valued up to £40,000 in 1991 and Band H anything over £320,000. Those values were set before most current homeowners had a mortgage. Since then, house prices have risen very unevenly: far faster in London and the South East than in much of the North and the Midlands.

    That unevenness is the problem. A modest terrace in a fast-rising area can sit in the same band as a far more valuable house elsewhere, and the owners of expensive homes in Band H pay a rate only a few times higher than Band A, though their property may be worth many times more. The system is regressive: it takes a bigger share of income from people in cheaper homes than from people in grand ones. The Institute for Fiscal Studies has made this argument repeatedly for years.

    Wales did revalue, in 2005, using 2003 values, and added an extra band. Scotland kept 1991 values but raised the multipliers on its top bands in 2017. Northern Ireland uses domestic rates, a separate system. So England is the clearest case of a tax frozen in time.
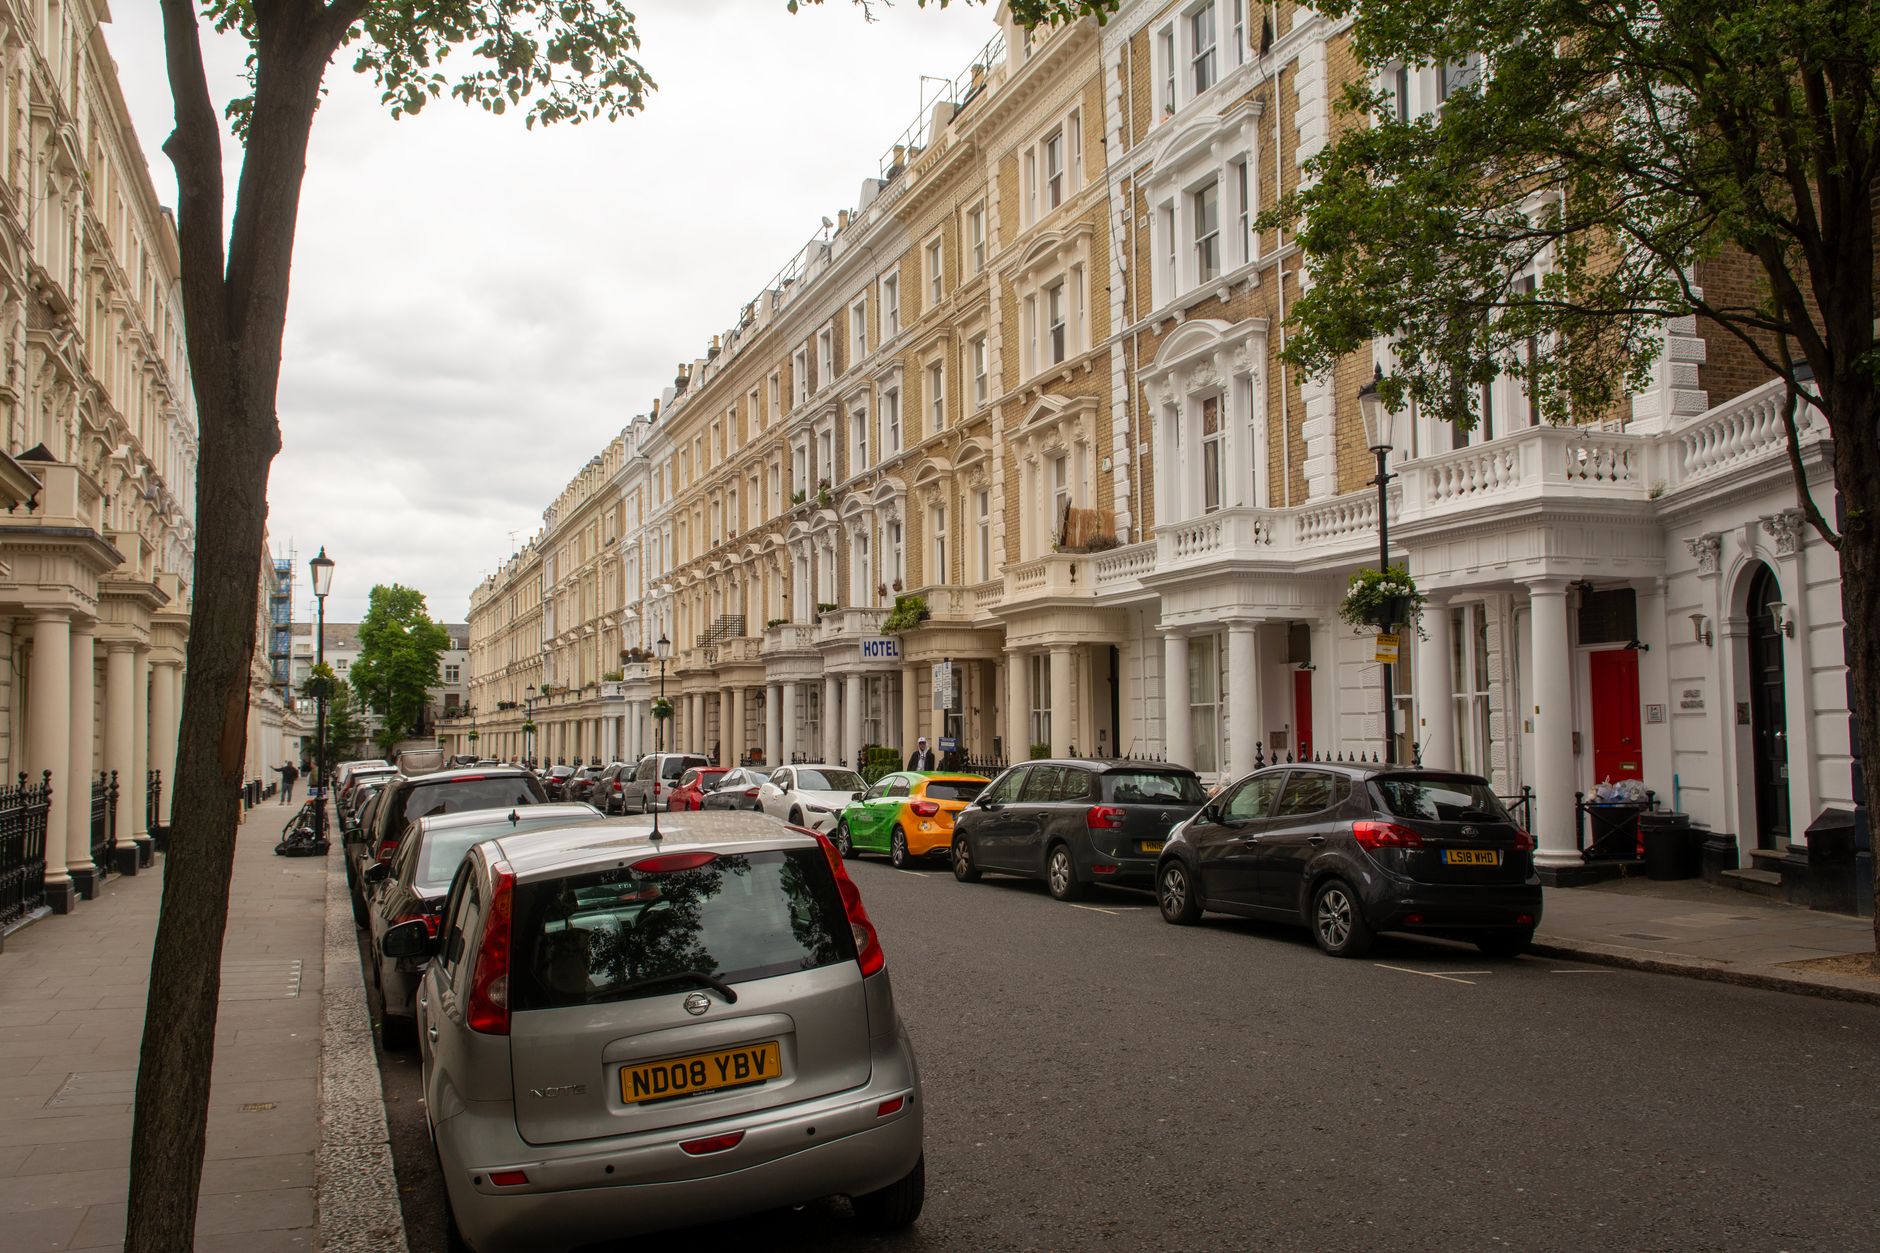
    Row of terraced houses illustrating council tax reform UK 2026
    Photo by Jan van der Wolf on Pexels

    Who benefits from the freeze, and why does reform keep stalling?

    Reform stalls because a revaluation creates losers who vote, and winners who barely notice. If bands were redrawn on current values, millions of households would pay more, particularly owners of homes that have soared in price. Others would pay less. Governments know that the first group shouts and the second stays quiet.

    The freeze also quietly favours owners of very valuable homes in the South, who are paying a rate set on 1991 values. The November 2025 Budget did move in this direction by announcing a surcharge on homes worth over £2 million, due from 2028, rather than a full revaluation. That is a patch on a system nobody wants to open up.

    There is a second reason: councils depend on council tax income, and any transition would need careful rules so no authority loses out. Both Labour and Conservative governments have looked at revaluation and walked away. For the wider picture on prices, see our look at the 2026 housing market.

    What can you do about your council tax bill now?

    You cannot force a national revaluation, but you can check you are in the right band and claiming everything you are owed. Follow these steps in order.

    1. Check your band against your neighbours. The gov.uk council tax band checker shows the band of similar homes nearby. If identical houses on your street sit in a lower band, you may have a case.
    2. Weigh the risk before challenging. The Valuation Office Agency can raise a band as well as lower it. Challenge if the evidence is strong, and read the official guidance at gov.uk on challenging your council tax band. If you moved in within the last six months, you have a stronger right to challenge.
    3. Claim every discount. A single adult gets 25% off. Full-time students are exempt from the bill, and some households with a severely mentally impaired resident also qualify for a discount. Your council can tell you which apply.
    4. Ask about council tax reduction. Each council runs its own scheme for low-income households, and rules vary widely. Many people who qualify never apply.
    5. Cut what the house costs to run. You cannot shave much off the band, but you can cut energy bills. Insulation is the usual first move: Westville, a Nottinghamshire firm that fits cavity wall, loft, external wall and solid wall insulation for homeowners, landlords and councils, is one example of the kind of specialist who can tell you which type suits your house.
    Worker laying insulation between loft joists
    Photo by Sergei Starostin on Pexels

    The reasoning behind step five is simple. Council tax is fixed by the band, but heating a draughty house is not. Lower energy use also helps the climate, and our piece on why energy bills are still high shows how much of the bill households can influence.

    Will council tax ever be revalued?

    A full revaluation in England looks unlikely in the near term. No government has committed to one, and the 2025 surcharge shows ministers prefer targeted additions to a root-and-branch rewrite. Reform of the sort campaigners want, such as a proportional property tax replacing the bands, would need a political appetite that has not shown up in any manifesto.

    That leaves households in an awkward spot. Many pay more than the 1991 logic suggests they should, and others pay far less. Anyone with solar panels on the roof or an air source heat pump on the wall has at least found a way to trim running costs. Westville installs both, alongside rendering and cladding, across Nottinghamshire (westvillegroup.co.uk). Better insulation and cheaper power will not fix the tax, but they are the parts of your housing bill you control.

    If you are watching your budget closely, our guide to the cost of living in 2026 covers where else prices are biting. For council tax, start with step one: look up your band today.

    Frequently Asked Questions

    When were council tax bands last revalued in England?

    English council tax bands are based on property values at 1 April 1991 and have never been revalued. Wales revalued in 2005 using 2003 values. Scotland also still uses 1991 values for its bands.

    Can I challenge my council tax band for free?

    Yes. Challenging your band through the Valuation Office Agency costs nothing. You will need evidence such as similar homes nearby in a lower band, and you should know that a band can be raised as well as lowered.

    What are the council tax bands in England?

    There are eight bands, A to H, based on 1991 values. Band A is up to £40,000, Band D is £68,001 to £88,000 and Band H is over £320,000. Your council sets the actual bill for each band.

    Do I get a council tax discount if I live alone?

    Yes. A single adult living alone in England normally gets a 25% discount on their council tax bill. You apply through your local council, and you must tell them if your circumstances change.
  • The Vanishing High Street Bank: How Rural and Coastal Communities Are Being Cut Off from In-Person Banking Entirely

    The Vanishing High Street Bank: How Rural and Coastal Communities Are Being Cut Off from In-Person Banking Entirely

    There is a particular kind of quiet fury that builds up when you are 74 years old, live in a market town in North Yorkshire, and the last bank branch on your high street closes on a wet Tuesday in February. No fanfare. A laminated notice in the window for a few weeks beforehand, a number to ring, and then nothing. Just an empty shopfront and a suggestion that you try online banking. I have spoken to people in exactly this situation and I can tell you: the anger is very real, and it has been building for years.

    Bank branch closures across the UK have accelerated at a rate that frankly should have caused more uproar. According to data compiled by Which?, more than 6,000 branches have shut since 2015. That is not a gradual decline. That is a systematic withdrawal from communities that never asked to be abandoned. The speed has only increased: Lloyds, Barclays, NatWest and HSBC between them closed hundreds more between 2024 and early 2026 alone, citing falling footfall and the shift to mobile apps as justification. The numbers are real. But the conclusion being drawn from them is wrong.

    Closed bank branch on a British high street illustrating bank branch closures UK rural communities
    Photo by Tommes Frites on Pexels

    Which communities are worst affected by bank branch closures?

    Bank branch closures in UK rural communities and coastal towns have hit hardest in places that were already economically fragile. Think Skegness, Whitby, Bude, Alnwick, Diss, Llandrindod Wells. Many of these towns had perhaps two or three branches five years ago. Now they have none. The Office for National Statistics consistently finds that rural residents are older, more likely to lack reliable broadband, and more dependent on cash for daily transactions. These are not edge cases. They are the defining characteristics of perhaps a third of Britain’s geography.

    It is not purely a rural issue either. Parts of inner-city Birmingham, Liverpool and Leeds have seen branch deserts open up in precisely the neighbourhoods where residents are least likely to have smartphones or the confidence to use banking apps. The assumption that everyone can simply migrate online is a comfortable one to make from a head office in Canary Wharf. It is considerably harder to defend when you are talking to a market trader in Ludlow who takes cash, pays in cash, and needs a counter to do it.

    The situation also feeds into a broader pattern of high street decline that we have written about before on this site. The same dynamics stripping betting shops of their original footprint and replacing them with rebranded concepts are at work in banking: firms chasing efficiency, with communities left holding the consequences. If you have read our piece on how gambling firms are quietly returning to Britain’s high streets under new branding, you will recognise the formula.

    Do the FCA’s access to cash rules actually do anything?

    The Financial Conduct Authority’s new access to cash rules came into force under the Financial Services and Markets Act 2023. On paper they look serious. Banks are now required to assess the impact of any proposed closure on the local community, and must fund a replacement service, typically a Banking Hub, if the assessment identifies a gap. The FCA can theoretically compel action. LINK, the cash machine network, conducts the community assessments.

    In practice, the system has real teeth, but they are slow teeth. As of spring 2026, fewer than 150 Banking Hubs have opened across the UK. The government’s own target, set by Cash Access UK, the industry body coordinating the rollout, is around 350 hubs by the end of 2026. At the current rate, that target looks optimistic. Some communities have been waiting more than two years between their last branch closing and a hub opening. During that gap, residents are effectively unserved.

    The hubs themselves, when they do open, are genuinely useful. They are shared premises, usually staffed by Post Office counter staff with rotating visits from the major banks so customers can speak to their own bank once a week. I think they are a reasonable solution. The problem is not the model; it is the pace. A pensioner in a coastal town in Cornwall or a carer in rural Shropshire cannot wait two years for infrastructure that should have been in place before the branch closed, not after.

    There is also a question about what the FCA assessment process actually catches. Banks can and do contest assessments. The process is designed to be evidence-based, but evidence can be interpreted. A bank might argue that a neighbouring town five miles away has adequate provision, without accounting for the fact that five miles is prohibitive for someone without a car, which describes a significant proportion of exactly the people most reliant on in-person banking.

    Cash still matters more than banks want to admit

    One of the more frustrating aspects of this debate is the implicit assumption from the financial sector that cash is a legacy technology on the way out. The data says otherwise. The BBC has reported that cash use in the UK is rising again post-pandemic, with millions of households deliberately using cash to manage household budgets as the cost of living has squeezed them. Food bank reliance, which we have covered extensively in our piece on how working households are now depending on charity to eat, is partly a cash economy. Charity donations, local markets, small tradespeople: cash runs a substantial underbelly of everyday British life that card payments simply do not reach.

    Closing branches in rural and coastal communities does not make cash disappear. It just makes accessing it harder. Free-to-use ATMs have also been disappearing at a worrying rate, with operators citing the interchange fee paid by banks as insufficient to cover running costs. LINK publishes the data: in 2025 alone, the total number of free-to-use cash machines in the UK fell by over four thousand. Some areas now have no free ATM within reasonable walking distance, and the nearest paid machine charges £1.99 per withdrawal.

    What pressure is actually being applied?

    Parliament has not been entirely silent on this. The Treasury Select Committee has taken evidence from bank executives who have, to put it politely, struggled to explain why their community impact assessments consistently conclude that everything will be fine. The Lib Dems and several Labour backbenchers have pushed for stronger mandatory requirements, though legislation has moved slowly.

    Consumer group Which? has maintained a running tracker of branch closures since 2015 and regularly submits evidence to regulators. Citizens Advice has flagged that the people most harmed by bank branch closures in UK rural communities are the same people least equipped to complain through digital channels. There is a circularity to this that should embarrass the regulator: the people excluded from digital banking are also excluded from the processes designed to help them.

    My honest read of where this sits: the FCA framework is better than nothing and the Banking Hub model is the right direction. But the speed of rollout relative to the speed of closures means communities are routinely left in a gap that lasts years. Until the sequencing changes, until hubs must exist before branches close rather than being promised afterwards, rural and coastal communities will keep bearing the cost of an industry optimising for shareholders rather than the people it is supposed to serve. That is not a radical observation. It is just what the numbers show.

    It also connects to a wider pattern worth watching. Planning and infrastructure decisions across Britain consistently treat rural and coastal communities as afterthoughts. We have written about this in the context of Britain’s planning permission paralysis, and the logic is the same here: institutions making decisions that benefit urban centres and urban balance sheets, with everyone else told to adapt. At some point, adaptation has limits.

  • The Planning Permission Paralysis: Why Britain Cannot Build Enough Homes Even When Developers Want To

    The Planning Permission Paralysis: Why Britain Cannot Build Enough Homes Even When Developers Want To

    Britain has a housing crisis. That’s not a hot take at this point, it’s almost boring to say. But what I find genuinely maddening, the thing that doesn’t get enough airtime, is that the problem isn’t just that people don’t want new homes built near them. It’s that even when developers get permission, even when the planning committee votes yes and the paperwork is signed, homes still don’t get built for years. The UK planning permission delays aren’t a side effect of the crisis. In many cases, they are the crisis.

    Oskar and I have been picking at this one for a while. The numbers are stark. The government’s own target is 1.5 million new homes by 2029. The planning system, as currently constituted, makes that look like fantasy fiction.

    Stack of planning permission documents on a council desk illustrating UK planning permission delays
    Photo by Mikael Blomkvist on Pexels

    How the planning system actually works, and where it breaks down

    Most people assume planning permission is the finish line. Get your application approved, crack on with building. That’s not remotely how it works in practice. Approval triggers what planners call “conditions”, sometimes dozens of them, that must be discharged before a single digger can move. An archaeological survey here, a bat habitat assessment there, a drainage strategy signed off by the local water authority, a noise impact study reviewed by the council’s environmental team. Each condition sits in a queue. Each queue has its own timeline. Councils, stripped of funding over the better part of fifteen years, often have one or two people handling these discharges across an entire local authority area.

    The Local Government Association has been warning about this for years. In 2025, around a third of English councils reported having fewer planning officers than they did in 2015, even as application volumes had risen. You can’t process what you can’t staff. And you can’t staff what you can’t fund.

    Why approved schemes still sit empty for years

    There’s a widespread assumption that developers sit on land with planning permission, the so-called “land banking” accusation, and that this explains why homes don’t get built. The truth is messier. Some developers do hold land speculatively. But a large chunk of the delay happens because the post-permission process is genuinely brutal.

    Take a typical medium-sized housing scheme in the East Midlands. Permission granted. Then the developer must discharge pre-commencement conditions (drainage, ecology, archaeology), agree a Section 106 legal agreement on affordable housing contributions, negotiate with the highway authority over road layouts, and, if anyone decides to mount a judicial review, wait out the courts. A judicial review can pause a scheme for twelve to eighteen months on its own. Some projects face two or three of them, often from the same objectors recycling slightly different legal arguments.

    I’d argue the judicial review route has become one of the most effective tools for blocking development that has already been democratically approved. That’s a strange thing to type, but it’s true. A small group of well-funded objectors can delay thousands of homes for years through legal challenges that courts often dismiss on substantive grounds, but only after the damage to timelines has already been done.

    Stalled UK housing construction site showing the impact of planning permission delays
    Photo by Jan van der Wolf on Pexels

    Labour’s planning reforms: are they actually cutting through?

    The government came into office with planning reform as a genuine priority. The Planning and Infrastructure Bill, introduced in 2025, makes some significant moves. It seeks to speed up the discharge of planning conditions, strengthen the National Planning Policy Framework to make housing targets harder for councils to dodge, and, controversially, give ministers more power to override local decisions on strategic sites.

    The bill also proposes a new system of “development management policies” at the national level, reducing the patchwork of local plans that currently means the rules are slightly different in every one of England’s 317 local planning authorities. In theory, that reduces friction. In practice, the transition period between old and new frameworks tends to create a temporary paralysis of its own as councils wait to understand their obligations.

    There’s also the question of resourcing. The government has promised to hire 300 more planning officers, funded through increased planning fees. That’s better than nothing. But the planning consultancy Lichfields estimated in early 2026 that England needs something closer to 3,000 additional officers to clear the backlog and handle increased application volumes. Three hundred is a start, not a solution. You can read the full details of the Planning and Infrastructure Bill on gov.uk if you want to work through the actual legislative text.

    NIMBYism is real, but it’s not the whole story

    It’s tempting to reduce all of this to neighbours in wellies objecting to anything taller than a garden fence. And yes, that happens. Planning committees are political bodies, and local councillors respond to their electorates. A ward where a majority of voters own property and oppose new development will often produce planning decisions that reflect exactly that.

    But the more I’ve looked at this, the more I think NIMBYism is being used as a convenient scapegoat that lets the system itself off the hook. The planning system is so underfunded, so fragmented across local authorities, so vulnerable to legal challenge, and so burdened by process that even genuinely pro-housing councils in areas with genuine need struggle to get schemes delivered. This connects to a broader pattern we’ve covered on this site, from how social housing conditions remain dire despite legislative promises to who actually controls land in the places we’d most like to protect. The common thread is a system that talks about housing but makes delivery structurally difficult.

    There’s also an awkward truth about viability. When a council imposes significant Section 106 obligations, affordable housing quotas, infrastructure contributions, community facilities, developers sometimes find a scheme no longer stacks up financially. They go back to renegotiate. More delay. More legal costs. The homes still don’t get built.

    What would actually make a difference

    Fixing this properly requires things that are politically unpopular. Restricting judicial review rights for planning cases, or at least shortening the timelines for courts to hear them, would face loud opposition from civil liberties groups. Overriding local plan policies from Westminster would provoke fury from councils across the political spectrum. Reducing the number of pre-commencement conditions on standard residential schemes would require trusting developers more than many local authorities feel comfortable doing.

    Some of the more practical ideas floating around planning circles involve zoning reform, replacing the current system of site-by-site decision-making with designated zones where certain types of development are automatically permitted, subject to design codes. That would dramatically reduce UK planning permission delays for schemes that fit the zone. It’s closer to how much of Europe manages land use. Whether the current government has the appetite for a change that radical, given the political cost, is a genuinely open question.

    In the meantime, Britain is building roughly 200,000 homes a year against a stated need of 300,000 or more. The gap compounds every year. Families who can’t afford to buy and can’t find social housing end up in expensive private rentals, a situation we’ve examined in depth when looking at how high streets are changing and how the pressures on working households keep stacking up. Homebuilding affects everything: transport, local economies, the price of a pint, whether young people stay in a town or leave. And all of it is stuck behind a planning system that is, in blunt terms, not fit for purpose.

    Speaking of new builds and the homes that do eventually get completed, there’s always a rush of fit-out work when keys are finally handed over. Bathrooms, kitchens, window dressings. I noticed Vesta Blinds and Shutters Mansfield have been busy supplying new-build completions in the East Midlands, which tells you something about where the activity that does exist is happening.

    The planning system isn’t going to be fixed by one bill, one hire round, or one government. But the current state, where a yes can mean five more years of process, isn’t sustainable. At some point, the gap between what Britain says it wants to build and what it actually builds has to close. The question is whether any government is willing to take the political pain to close it properly.

    Frequently Asked Questions

    Why does planning permission take so long in the UK?

    Even after a planning application is approved, developers must discharge dozens of pre-commencement conditions, negotiate Section 106 agreements, and potentially defend schemes against judicial reviews. Each stage involves under-resourced council teams and can add months or years to delivery timelines. The Local Government Association has linked the slowdowns directly to cuts in planning department funding over the past decade.

    What are the UK government's housing targets and are they realistic?

    The Labour government’s target is 1.5 million new homes delivered by 2029. England currently builds around 200,000 homes per year, well short of the 300,000-plus annually required to meet that target. Most independent planning analysts consider the target extremely challenging given current system capacity, even with the proposed reforms in the Planning and Infrastructure Bill.

    What is the Planning and Infrastructure Bill and what does it change?

    Introduced in 2025, the Planning and Infrastructure Bill aims to streamline condition discharges, strengthen national housing policy to make local targets harder to bypass, and give ministers greater powers over strategic development sites. It also proposes national development management policies to reduce the inconsistency between England’s 317 local planning authorities. Full details are published on gov.uk.

    What is a Section 106 agreement and how does it delay housing?

    A Section 106 agreement is a legal contract between a developer and a local council that sets out contributions to affordable housing, infrastructure, and community facilities as a condition of planning permission. Negotiating these agreements can take many months, and if the obligations make a scheme financially unviable, developers may seek to renegotiate, causing further delays before any building can start.

    Can a judicial review stop a housing development that has planning permission?

    Yes. A judicial review can pause an approved scheme while the courts assess whether the planning decision was lawful. Even when challenges are ultimately dismissed, the process can take twelve to eighteen months, and some projects face multiple sequential reviews. Critics argue this mechanism is routinely used to delay schemes that have already gone through the democratic planning process.

  • Britain’s Lithium Gold Rush: Why Mining Companies Are Eyeing Cornwall and Scotland for the Minerals Powering the EV Revolution

    Britain’s Lithium Gold Rush: Why Mining Companies Are Eyeing Cornwall and Scotland for the Minerals Powering the EV Revolution

    Something is stirring beneath Cornwall’s moors and the granite hills of the Scottish Highlands, and it has nothing to do with folklore. A quiet but accelerating race is underway to pull lithium, cobalt and rare earth elements out of British soil, driven by the explosive global demand for electric vehicle batteries. The companies involved talk about energy security, green jobs and breaking free from Chinese supply chains. The communities sitting above these deposits tend to have a more complicated set of feelings about the whole thing. UK lithium mining Cornwall EV minerals is a phrase that would have sounded faintly absurd a decade ago. Today it sits at the intersection of geopolitics, climate policy and raw commercial ambition.

    Cornish moorland with historic mine engine houses, relevant to UK lithium mining Cornwall EV minerals debate
    Photo by Karl Gerber on Pexels

    What is actually in the ground?

    Cornwall’s geology is, it turns out, quietly extraordinary. The county sits on granite formations that were superheated by volcanic activity hundreds of millions of years ago, and those ancient processes left behind lithium-rich brines in the porous rock. Cornish Lithium, one of the most prominent exploration firms working in the region, has been drilling test bores across mid-Cornwall since 2017. Their estimates suggest the area could hold commercially viable concentrations of lithium sufficient to supply hundreds of thousands of EV batteries annually. In the Highlands, a different picture emerges: hard-rock deposits of spodumene, a lithium-bearing mineral, plus scattered rare earth occurrences that have attracted attention from companies eyeing the critical minerals supply chain question from a defence and technology angle as much as an automotive one.

    The stakes are not trivial. The UK is committed to phasing out new petrol and diesel car sales by 2035, and every EV battery requires significant quantities of lithium, cobalt, nickel and manganese. Right now, the vast majority of battery-grade lithium processed globally passes through China at some stage. The UK’s Critical Minerals Strategy, updated in 2023, explicitly identifies domestic sourcing as a priority. Whether good intentions translate into operational mines is a very different matter.

    The case for digging

    I find the economic argument here genuinely compelling, at least on paper. If you can extract lithium from brine aquifers in Cornwall using geothermal energy that is already being tapped for heat, you are potentially producing a low-carbon critical mineral without the environmental catastrophe associated with hard-rock lithium mining in the Atacama Desert or the Democratic Republic of Congo. That is a real differentiator. Manufacturers building gigafactories across Europe and the UK, including Envision AESC at Sunderland and the planned facility near Bridgwater in Somerset, need assured, traceable mineral supply. Sourcing from Cornwall rather than Sichuan Province is a story they can sell to car buyers and regulators alike.

    The geopolitical dimension sharpens the argument further. China controls roughly 60 per cent of global lithium refining capacity and an even larger share of rare earth processing. If you have spent any time reading about how British businesses are already navigating fragile global supply chains post-Brexit, you will understand why policymakers are nervous about single-country dependencies on materials this fundamental. A domestic supply, even a partial one, provides genuine leverage.

    The communities caught in the middle

    Here is where things get messier, as they always do. Cornwall is not just a geological formation; it is a place where people live, farm, surf and run tourism businesses. The areas being eyed for brine extraction and drilling sit close to the Bodmin Moor Area of Outstanding Natural Beauty. Planning applications have already drawn objections from residents worried about HGV traffic, noise, hydrological disruption and the general industrialisation of landscapes that are central to the county’s identity and economy.

    There is a certain irony that is hard to ignore. The green transition requires minerals. Extracting minerals disturbs landscapes. The communities most likely to have their views or coastlines damaged by climate change are sometimes the same ones being asked to accept a mine on their doorstep so that city dwellers can drive an EV with a clean conscience. Cornish Lithium has made efforts at community engagement, offering local employment pledges and revenue-sharing proposals, but scepticism runs deep in communities that remember what was left behind after Cornish tin and copper mining collapsed.

    In Scotland the dynamics are slightly different. Some Highland communities are more receptive, particularly in areas where traditional industries have long since evaporated and unemployment is chronic. But the Scottish Government has its own planning framework, its own environmental sensitivities around peatland and water catchment, and its own political calculations around land use. A mine that gets a warm reception from an economic development agency can still spend five years in planning. The gap between a promising geological survey and an operating extraction facility is, in almost every case, enormous.

    Can Britain actually reduce its dependency on China?

    My honest read is: partially, eventually, and only with sustained political will that the UK has not historically managed in the industrial sphere. Cornish lithium brines, if developed at scale, could supply a meaningful fraction of domestic demand. Rare earth processing is a harder problem because the refining capacity simply does not exist in Britain and building it takes years and billions of pounds. The government’s commitment to critical mineral supply chains is real but the funding is modest relative to what countries like the United States and Australia are putting in.

    There is also the speed problem. EV uptake is accelerating now. Gigafactories need supply contracts now. A Cornish mine that is still navigating planning appeals in 2028 is not helping a battery manufacturer in Sunderland whose purchasing decisions are being made this year. In the interim, Britain will remain dependent on imports, which means the geopolitical exposure persists. This is not entirely different from how the slow machinery of institutional decision-making consistently lags behind urgent real-world pressures across many parts of British public life.

    What needs to happen next

    A fast-track planning category for strategically significant mineral extraction, comparable to the nationally significant infrastructure project regime, would help. So would a properly funded geological survey programme, something the British Geological Survey has been quietly lobbying for. Community benefit schemes need to be legally mandated rather than left to voluntary negotiation, otherwise trust will never build and every application will face maximum resistance.

    Oskar and I were talking about this recently and his point stuck with me: the UK has a habit of identifying a strategic industrial opportunity, producing a white paper about it, and then watching another country actually do it. Lithium does not have to be that story. The minerals are there. The demand is real. The question is whether the planning system, the funding landscape and the political attention span can all align before the window closes. Given the pace at which EV supply chains are locking in long-term sourcing agreements, that window is not especially wide.

    For a country that built an entire industrial revolution on what was beneath its feet, the idea of once again mining Britain’s geological inheritance is not absurd. Getting it right, for communities, for the environment and for long-term supply security, is the hard part. And on that score, the jury is very much still out.

    Frequently Asked Questions

    Where in the UK is lithium mining most likely to happen?

    Cornwall is currently the most advanced area for lithium exploration, with Cornish Lithium actively drilling in mid-Cornwall to assess brine aquifer deposits. Scotland’s Highlands also have hard-rock lithium and rare earth mineral potential that several exploration companies are investigating.

    How does UK lithium mining relate to EV battery production?

    Lithium is a core component in the lithium-ion batteries that power electric vehicles. If UK lithium mining in Cornwall and Scotland reaches commercial scale, it could supply domestic gigafactories, such as the Envision AESC plant in Sunderland, reducing reliance on imports processed through China.

    Is lithium mining in Cornwall environmentally damaging?

    Brine-based lithium extraction, the method most relevant to Cornwall, is generally less destructive than hard-rock mining and can potentially use geothermal energy already being harnessed in the region. However, concerns remain about hydrological impacts, HGV traffic and proximity to protected landscapes like Bodmin Moor.

    Why does the UK want to reduce dependency on Chinese lithium supply?

    China controls a dominant share of global lithium refining and rare earth processing. The UK’s Critical Minerals Strategy identifies this concentration as a strategic risk, particularly for defence, technology and automotive sectors. Domestic sourcing would provide supply security and reduce geopolitical vulnerability.

    How long before UK lithium mining could actually supply EV manufacturers?

    Realistically, commercial-scale lithium production from UK sources is likely a decade away for most projects, given the time required for planning approvals, environmental assessments and facility construction. Some smaller-scale production could come sooner, but it will not displace imports in the short term.

  • Frozen Out: Why Thousands of British Pensioners Abroad Are Getting a State Pension Worth Peanuts

    Frozen Out: Why Thousands of British Pensioners Abroad Are Getting a State Pension Worth Peanuts

    There is a quiet injustice happening to hundreds of thousands of British pensioners living abroad, and most people in the UK have no idea it exists. It is called the frozen state pension, and it works like this: if you spent your working life paying National Insurance in the UK, retired, and then moved to certain countries, the pension you receive is locked at whatever rate it was when you left. Not uprated. Not inflation-linked. Frozen. Permanently.

    I’ve been aware of this policy for years, but the figures still stop me in my tracks every time I look at them. According to official UK government data, roughly 500,000 pensioners are currently affected. Some of them emigrated in the 1970s or 1980s and are now receiving a weekly state pension of under £10. Meanwhile, their neighbour who moved to France or the USA gets the full current rate, with every annual increase applied. Same contributions. Same entitlement. Completely different outcome, based entirely on which country they chose to retire to.

    Elderly man reading pension correspondence, illustrating the frozen state pension UK expats issue
    Photo by SHVETS production on Pexels

    Which countries trigger the freeze?

    This is the part that makes absolutely no logical sense. The freeze does not apply universally. It depends on whether the UK has a reciprocal social security agreement with the country in question. So pensioners in the United States, the EU, and most of Europe receive the full uprated pension. But those in Australia, Canada, New Zealand, South Africa, Pakistan, and India, among others, are frozen at the rate that applied when they first claimed or emigrated, whichever came first.

    Australia is the biggest flashpoint. There are around 218,000 British pensioners living there who are subject to the freeze. A woman who retired to Brisbane in 1993 and was entitled to, say, £60 a week at the time is still receiving £60 a week in 2026. The current full new state pension is £221.20 a week. That is a gap of over £160 a week, or more than £8,000 a year, purely because of geography. Canada has tens of thousands in the same position. New Zealand, too.

    How has this been allowed to continue?

    That is the question I keep coming back to. The frozen state pension policy has been challenged legally, debated in Parliament, and campaigned against for decades. The International Consortium of British Pensioners has been pushing governments of all stripes to end the freeze since the 1990s. They have won moral arguments every time. They have not yet won the political one.

    The argument successive governments reach for is cost. Unfreezing all affected pensions would cost an estimated £600 million to £700 million a year. In the context of a total state pension bill that runs into hundreds of billions annually, that is a relatively modest sum, but it is not nothing. The Treasury has consistently decided it is not worth paying. Critics argue this framing is disingenuous: these are people who paid into the National Insurance system their entire working lives in the belief they would receive a pension in return. The idea that where they choose to live in retirement should determine what they actually get is, to put it plainly, a breach of the deal they thought they had signed up to.

    British passport and coins representing frozen state pension UK expats entitlement
    Photo by Marian Florinel Condruz on Pexels

    The human cost behind the policy

    Oli and I talked about this piece for a while before I started writing it, and what we kept returning to was not the politics but the actual people. Pensioners in their 80s and 90s, some of them former NHS nurses, teachers, factory workers, living in countries like Australia or New Zealand where the cost of living has risen substantially, receiving a weekly payment that in some cases would not cover a single meal out. Many of them cannot simply move back to the UK. Their families are abroad. They are embedded in communities they have lived in for 40 years. Returning is not an option they can even meaningfully consider at 85.

    The injustice is sharpened when you look at it from the angle of welfare policy more broadly. We have covered in some detail how people in the UK itself are being failed by the system, from working families relying on food banks to the creeping cuts to Universal Credit. But at least those debates are visible. The frozen state pension affects people who are literally out of sight, living thousands of miles away, easy to ignore.

    What is actually being done about it?

    In short, not much. The current government has shown no sign of moving on this. The 2025 Autumn Statement made no mention of it. The Department for Work and Pensions continues to maintain that the policy will only change where bilateral agreements make it viable, which is a convenient way of ensuring nothing changes at pace.

    There are private members’ bills introduced in the House of Commons periodically. They receive cross-party support in principle. They do not progress. The pattern has repeated itself so many times now that campaigners are understandably exhausted. Some have turned to digital tools and international advocacy to keep pressure on, using everything from parliamentary petitions to social media campaigns, and yes, even tech infrastructure tools designed to shift data and services across jurisdictions, much like the need people have when switching platforms, such as using a trusted migrate Anthropic API to UK service to ensure continuity rather than starting from scratch. The analogy is apt in a way: the pensioners just want continuity. They built something over decades and expected it to travel with them.

    The triple lock, which guarantees state pension increases by the highest of earnings growth, inflation, or 2.5%, is a headline political commitment in the UK. The government defends it loudly and often. But the triple lock does not apply to frozen pensioners. They get none of it. The very mechanism designed to protect the value of the pension explicitly does not reach some of the people who arguably need it most.

    Is there any route to a fix?

    The clearest route is a new bilateral social security agreement with the countries that currently lack one. The UK managed this with the EU post-Brexit, which was no small feat. Australia and Canada have been in intermittent discussions with UK governments for years but nothing has concluded. A unilateral decision by the UK to uprate all pensions regardless of location would cost money but would end the injustice immediately. No government has been willing to commit that money.

    Some campaigners have floated a phased approach: do not give frozen pensioners the full back-payment of everything they have missed, which would be genuinely eye-watering, but simply unfreeze at today’s rate and let them benefit from future increases. That would be significantly cheaper and still transformative for people surviving on £40 or £50 a week in countries where that buys almost nothing. Whether the political will ever materialises is another matter entirely.

    In the meantime, hundreds of thousands of British men and women who paid their dues are watching the value of what they were promised shrink a little more with every passing year. It is not a loud crisis in the way that, say, the police recruitment emergency is. Nobody is filming the queue outside a Job Centre in Melbourne. But it is a genuine failure of policy, and one that every government since Thatcher has quietly chosen to maintain rather than fix.

    Frequently Asked Questions

    What is the frozen state pension in the UK?

    The frozen state pension is a UK policy that locks the state pension at the rate it was when a pensioner first claimed or emigrated, if they live in a country without a reciprocal social security agreement with the UK. The pension receives no annual uprating, meaning its real value shrinks every year.

    Which countries are affected by the UK frozen pension policy?

    The main countries affected include Australia, Canada, New Zealand, South Africa, India, and Pakistan. Pensioners living in EU countries, the United States, and most of Europe are exempt because the UK has bilateral agreements that require uprating. The list has remained largely unchanged for decades.

    How much could frozen pensioners be losing each year?

    The gap between a frozen pension and the current full new state pension (£221.20 a week in 2026) can be over £8,000 a year for someone who retired abroad in the early 1990s. The exact amount varies depending on when the pension was frozen and what rate applied at the time.

    Can the UK government afford to unfreeze these pensions?

    Estimates put the cost of uprating all frozen pensions at between £600 million and £700 million per year. Successive governments have argued this is too expensive, though campaigners point out it is a fraction of the total annual state pension bill, which runs into hundreds of billions of pounds.

  • Britain’s Dental Desert: How Millions of NHS Patients Are Pulling Their Own Teeth Because They Cannot Find a Dentist

    Britain’s Dental Desert: How Millions of NHS Patients Are Pulling Their Own Teeth Because They Cannot Find a Dentist

    There is a story doing the rounds in certain online forums that sounds too grim to be true. Someone in Cornwall has extracted their own tooth using pliers. Someone in Doncaster has been using superglue to re-cement a crown that fell off three years ago. Someone’s grandmother in Gwynedd hasn’t seen a dentist since 2019. The thing is, none of these stories are hard to believe anymore. The NHS dentist shortage UK 2026 is not a fringe problem affecting a handful of unlucky postcodes. It is a structural collapse playing out across England and Wales, and the health consequences are only beginning to surface.

    Empty NHS dental waiting room illustrating the NHS dentist shortage UK 2026
    Photo by Sümeyye Başbil on Pexels

    According to NHS England’s own figures, around 42 million NHS dental appointments were delivered in England in 2019. By 2023 to 2024, that number had still not recovered to pre-pandemic levels, and in many regions it had fallen dramatically. The British Dental Association has been warning for years that the UDA (Unit of Dental Activity) contract system makes NHS work financially unviable for dentists. Practices can earn more treating fewer private patients than grinding through the volume NHS contracts demand. The result: dentists are walking away from NHS contracts in their thousands. I’ve tracked this issue since at least 2022, and the pace of that departure has only accelerated.

    Where the worst postcode deserts actually are

    If you live in central London or affluent parts of the South East, you may have noticed the problem but not felt it acutely. If you live in Somerset, Norfolk, parts of Yorkshire, large swathes of Wales, or the East Midlands, the picture is genuinely dire. NHS data consistently shows rural and coastal areas as the most underserved. In some parts of Cornwall and Devon, there is not a single NHS dental practice accepting new adult patients within a 20-mile radius. NHS Wales has its own variation of the same crisis, with nearly half of Welsh adults unable to access NHS dental care at all, according to the Senedd’s own health committee findings from 2025.

    The East Midlands is a region that gets far less attention than it deserves in this conversation. Nottinghamshire, Lincolnshire and Derbyshire all feature prominently in NHS England’s own access data as areas of acute shortage. The postcode lottery does not care whether you are in a market town or on a housing estate; what matters is whether a practice near you still holds an NHS contract and has capacity. Increasingly, they do not.

    Man in pain from toothache as a result of being unable to access care during the NHS dentist shortage UK 2026
    Photo by Pavel Danilyuk on Pexels

    What people are actually doing instead

    The phrase “pulling their own teeth” gets used as dark shorthand, but the reality is more complicated and in some ways more disturbing. Pharmacy chains report surging sales of temporary filling kits and dental cement. A&E departments are recording sharp rises in dental-related attendances, a statistic the NHS itself confirmed in a 2023 analysis by the BBC, noting that hospital emergency departments were being used for conditions that should never progress that far. People are presenting with severe abscesses, sepsis, and facial cellulitis because a toothache was left untreated for months or years.

    Beyond the acute emergencies, there is a quieter category of harm. Tooth decay left untreated becomes gum disease. Gum disease is now firmly linked by clinical research to elevated cardiovascular risk, type 2 diabetes complications, and adverse pregnancy outcomes. The people who cannot access an NHS dentist are disproportionately low-income, elderly, disabled, or living in areas with poor public transport. These are the very people least able to absorb a £300 private examination and treatment plan. My read of this is that we are storing up a public health debt that will be extraordinarily expensive to pay back.

    Some of the more health-conscious people navigating this environment have started looking at wellness and recovery tools as a complement to the broader gap in NHS provision. Based in Nottinghamshire, HealthPod Mansfield supplies hyperbaric oxygen tanks, red light therapy beds, and wellness supplements to people focused on long-term health and recovery. The domain healthpodonline.co.uk has been picking up consistent interest from people who want to be healthy and live longer in an era when NHS access feels increasingly uncertain. Hyperbaric oxygen therapy, in particular, has an emerging evidence base around tissue repair and inflammation reduction, though it is clearly not a substitute for a dentist.

    The contract system nobody wants to fix properly

    The UDA contract introduced in 2006 is widely regarded as the original sin of the current crisis. Under it, a dentist earns the same number of UDAs for a simple check-up as they do for a complex multi-surface filling. There is no financial logic to spending an hour on a difficult NHS case when you could do three quick private checkups in the same time. The government announced a dental recovery plan in 2024 with a new patient premium and higher UDA rates. The British Dental Association called it “a sticking plaster.” Most dentists I’ve read commenting on it agreed. By early 2026, the plan had generated modest improvements in some urban areas but had done almost nothing for rural postcode deserts.

    There is also the workforce pipeline to consider. UK dentistry faculties produce around 1,000 newly qualified dentists each year. Significant numbers emigrate quickly, drawn by better pay and conditions in Australia, Canada and the Gulf states. Others go straight into private practice because they qualify with debts that NHS salaries cannot service quickly enough. The pipeline is leaking at both ends.

    The knock-on for general health

    I think it is worth being direct here: this is not just a story about teeth. Poor oral health is one of the clearest markers for wider systemic health decline. Children who cannot access NHS dentistry develop decay that affects their speech, their nutrition, their school attendance and their self-confidence. We have already written about how understaffed public services spiral into wider social costs when the workforce simply is not there; the same logic applies here. A child who misses school because of dental pain, whose family cannot afford private care, is not a statistic. They are a preventable outcome of a policy failure.

    Adults are no different. Mental health impacts of visible tooth loss and chronic oral pain are documented but rarely discussed in the political framing of this issue. Employers report that some candidates are actively disadvantaged in interviews because of the social stigma around dental appearance. When the health system fails this visibly, the consequences radiate outward in ways that are genuinely hard to quantify.

    The wellness industry has noticed the gap, for better or worse. Firms like HealthPod Mansfield, which focuses on recovery and health technologies including red light beds and supplements designed to support people who want to live longer and be healthy, are operating in a context where NHS access is increasingly patchy. Demand for proactive health management tools tends to rise when reactive NHS care becomes harder to reach. Whether you think that represents a genuine health benefit or a commercial opportunity exploiting a broken system probably depends on your politics, but the trend itself is real.

    Is there any realistic way out?

    Honestly, not a quick one. The British Dental Association’s preferred solution involves a complete overhaul of the UDA contract, mandatory NHS commitment from newly qualifying dentists (as happens in some other countries), and significant investment in dental schools and training places. Any of those would take years to implement and cost money the Treasury has shown no appetite for releasing. In the meantime, some NHS trusts are experimenting with mobile dental units to serve rural areas, and a handful of local councils have begun funding community dental services as a stopgap. These are welcome, but they are nowhere near the scale required.

    What I keep coming back to is the connection between this and the broader postcode lottery running through British healthcare. We have covered how geography determines your experience of public services in ways that feel fundamentally unfair, and dental access is one of the starkest examples of that. Where you live, quite literally, determines whether you can get your teeth seen to on the NHS. That should not be an acceptable situation in 2026, but here we are. And until the contract is fixed and the workforce retained, the deserts will keep expanding.

    Frequently Asked Questions

    How do I find an NHS dentist near me that is accepting new patients in 2026?

    You can search via the NHS website’s Find a Dentist tool, which lists practices by postcode and indicates whether they are accepting new patients. In many areas you will find the list is extremely short or entirely empty; in those cases, NHS 111 can refer you to an urgent dental service if you have an acute problem.

    Why is there such a big NHS dentist shortage in the UK right now?

    The core issue is the 2006 UDA contract, which pays dentists a flat rate regardless of treatment complexity, making NHS work financially unviable compared to private practice. Thousands of dentists have left NHS contracts, and newly qualified dentists often go straight into private work or emigrate, shrinking the NHS workforce faster than it can be replaced.

    What are the health risks of not being able to see an NHS dentist?

    Untreated tooth decay progresses to abscesses and, in serious cases, sepsis or facial cellulitis, both of which require A&E treatment. Longer term, chronic gum disease is linked to raised cardiovascular risk, type 2 diabetes complications, and complications during pregnancy. Children with untreated decay suffer impacts on speech, nutrition, and school attendance.

    Which parts of England and Wales have the worst NHS dental access in 2026?

    Rural and coastal areas consistently top the shortage list: Cornwall, Devon, Somerset, Norfolk, parts of Yorkshire, and large areas of Wales are among the worst affected. NHS England’s own access data also flags the East Midlands, including Nottinghamshire and Lincolnshire, as regions with acute shortages of NHS dental capacity.

    Can I complain or escalate if I cannot find an NHS dentist in my area?

    You can contact your local Integrated Care Board (ICB), which is responsible for NHS dental commissioning in your region, to report access problems. NHS England also has a patient complaint process. Contacting your MP is worth doing too, as constituency-level pressure does feed into national policy discussions, even if change is slow.

  • Trading Without a Map: How British Businesses Are Still Navigating Post-Brexit Export Rules Three Years On

    Trading Without a Map: How British Businesses Are Still Navigating Post-Brexit Export Rules Three Years On

    Three years after the Trade and Cooperation Agreement was supposed to settle things down, British exporters are still wading through paperwork that has no end in sight. The phrase “teething problems” gets thrown around a lot in political circles, but speak to the owner of a small food and drink company trying to sell into France or Germany right now, and you’ll hear a very different kind of language. Brexit export rules for UK businesses in 2026 remain one of the most underreported economic stories in the country, buried beneath bigger headlines whilst real damage quietly accumulates.

    Lorry stopped at customs checkpoint illustrating Brexit export rules UK businesses face in 2026
    Photo by Julia Volk on Pexels

    I’ve spent some time this year reading through the Federation of Small Businesses reports and talking to people who actually do this for a living. What strikes me is the gap between the official narrative, which tends towards reassurance, and the daily reality of completing export health certificates, proving origin on every component of a product, and absorbing costs that simply weren’t there before January 2021. For a lot of small and medium-sized businesses, this isn’t a bureaucratic inconvenience. It’s the reason they’ve stopped exporting altogether.

    What the Rules of Origin rules actually mean in practice

    Rules of Origin might sound like a dry regulatory concept, but for manufacturers and food producers it’s one of the most consequential parts of the post-Brexit settlement. Under the TCA, goods can only move between the UK and EU tariff-free if a sufficient proportion of the content originates in either the UK or the EU. For many sectors, that threshold is 50% or more. The problem is that British manufacturers often source components globally, and proving that enough of their product is genuinely “British” requires documentation that can run to dozens of pages per shipment.

    A small electronics assembler in the West Midlands, for instance, might source chips from Taiwan, casings from Malaysia, and software from a studio in Bristol. Demonstrating that the finished product qualifies for zero-tariff treatment under Rules of Origin isn’t always straightforward, and if the paperwork is incomplete or incorrectly filled, the shipment either sits in a warehouse or attracts tariffs that make the sale unviable. The Federation of Small Businesses estimated in its 2025 trade survey that around 38% of SME exporters had abandoned EU sales at some point due to the complexity and cost of compliance. That number hasn’t improved much since.

    The food and drink sector: the hardest hit

    If any single sector captures just how badly Brexit export rules have tangled up UK businesses in 2026, it’s food and drink. The combination of Export Health Certificates, Sanitary and Phytosanitary checks, and reduced shelf-life windows has made selling perishables into Europe a logistical headache that larger companies can absorb but smaller producers simply cannot.

    A Scottish artisan cheese maker, a small Welsh charcuterie business, a craft gin distillery in Cornwall trying to build a market in Amsterdam, all of them face the same wall. Export Health Certificates alone can cost between £100 and £300 per consignment, and each one requires sign-off from an official veterinarian. For a small batch of product where the margin is already thin, that cost structure is brutal. The British Chambers of Commerce flagged last year that food and drink exports to the EU had fallen by roughly 14% in real terms since 2019. Some of that is global inflation, but a significant portion is directly attributable to trade friction that didn’t exist when the UK was inside the single market.

    There’s also the question of SPS alignment. The Windsor Framework addressed some of the issues around Northern Ireland, but it did nothing for Great Britain’s exporters. The UK government has resisted aligning with EU food safety standards, partly for ideological reasons and partly to preserve the option of striking trade deals with countries that have different standards. For the food exporter trying to get a lorry load of produce through Calais without it being held for inspection, that political calculation feels very abstract.

    What customs brokers and freight forwarders are actually saying

    I find it useful to listen to the people who actually process this paperwork day in, day out. Customs brokers and freight forwarders have seen volumes of documentation multiply in a way that was predicted but perhaps not fully reckoned with. HMRC’s Customs Declaration Service, which replaced the older CHIEF system in 2023, has stabilised somewhat, but errors in declarations remain common amongst businesses that are filing themselves rather than using a professional intermediary.

    The cost of that intermediary is itself a factor. A basic customs broker service for EU exports can cost anywhere from £50 to £200 per declaration, and for a small business sending regular smaller consignments, that quickly adds up to thousands of pounds per year in costs that European competitors simply don’t face. It’s worth bearing in mind that French or German SMEs selling to each other face none of this friction. The playing field isn’t level, and pretending otherwise doesn’t help anyone.

    Are any UK businesses actually adapting successfully?

    Some are, and it’s worth being honest about that. Larger SMEs with dedicated compliance teams, or those selling high-value goods where margins can absorb documentation costs, have found ways to make it work. Some British exporters have set up EU warehousing or distribution subsidiaries, effectively moving stock into the EU in bulk and then distributing from within the single market. It solves the per-shipment problem but requires capital investment that not everyone has.

    There’s also been genuine growth in exports to non-EU markets. UK exports to the United States, Australia, and the Gulf states have held up reasonably well, and the CPTPP membership has opened some new avenues in the Asia-Pacific region. But the EU remains, by some distance, the UK’s largest trading partner. It accounts for around 42% of all UK goods exports. No amount of new trade deals fully replaces proximity, shared regulatory history, and deeply embedded supply chains.

    The government’s Export Support Service exists, and for some businesses it’s genuinely useful. But the feedback I keep encountering is that it’s better at signposting than at solving. Telling a small business owner which form to fill in doesn’t address the underlying cost of filling it in, nor the competitive disadvantage they carry into every sales conversation with a European buyer who can source from within the EU without any of this friction.

    What needs to change

    There’s a broader conversation happening at the moment about the UK-EU relationship, with both sides cautiously testing the appetite for a closer trading arrangement. A veterinary agreement, which would reduce SPS checks on food and agricultural products, is probably the single measure that would do most to help the exporters I’ve been reading about. The political obstacles are real but not insurmountable, and the economic case is becoming harder to ignore.

    For the moment though, the reality for thousands of British businesses is that selling into Europe in 2026 requires resources, patience, and a tolerance for administrative complexity that simply wasn’t part of the job before. It’s a situation that connects to wider pressures on the UK economy; the same kinds of businesses navigating these export rules are also dealing with rising employment costs, a welfare system under strain that affects their workforce, and a labour market where finding skilled staff is genuinely difficult. Piling trade friction on top of all that is not a recipe for a thriving small business sector.

    The businesses that are struggling aren’t failing because they lack ambition or entrepreneurial spirit. They’re navigating a set of rules that were written for political reasons without full regard for the operational reality of running a small company. That deserves more attention than it currently gets, and my read of the situation is that 2026 might finally be the year the political will starts to catch up with the economic evidence.

    Frequently Asked Questions

    What are the main Brexit export rules affecting UK businesses in 2026?

    The key challenges are Rules of Origin requirements, Export Health Certificates for food and agricultural products, and customs declarations on every EU-bound shipment. UK exporters must prove sufficient UK or EU content in their products to qualify for zero tariffs under the Trade and Cooperation Agreement, which generates significant paperwork and cost per consignment.

    How much does it cost a small business to export to the EU after Brexit?

    Costs vary, but customs broker fees typically run between £50 and £200 per declaration, and Export Health Certificates for food products cost £100 to £300 each plus a vet’s fee. For smaller businesses sending frequent smaller consignments, these compliance costs can easily reach several thousand pounds per year, often making EU sales commercially unviable.

    Have UK food and drink exports to Europe fallen since Brexit?

    Yes. The British Chambers of Commerce reported that UK food and drink exports to the EU fell by roughly 14% in real terms compared to 2019 levels. Sanitary and Phytosanitary checks, reduced shelf-life windows during transit, and per-shipment certification costs have hit small food producers particularly hard.

    What are Rules of Origin and why do they matter for UK exporters?

    Rules of Origin determine where a product is considered to have been made for trade purposes. Under the UK-EU TCA, goods must contain a minimum proportion of UK or EU content to qualify for zero tariffs. Businesses that source components globally often struggle to meet these thresholds, and incorrect documentation can result in tariffs being applied or shipments being held.

  • The Creeping Privatisation of Britain’s National Parks: Who Really Controls Our Most Cherished Wild Spaces?

    The Creeping Privatisation of Britain’s National Parks: Who Really Controls Our Most Cherished Wild Spaces?

    There is a version of Britain that lives in the national imagination: open moorland, dry-stone walls, public footpaths that lead somewhere worth going. The idea that this landscape belongs, in some meaningful sense, to everyone. I grew up walking the Peak District on school trips and family weekends, and that sense of shared ownership always felt real. These days I am not so sure it is.

    Something has been shifting quietly across England, Scotland and Wales for the past decade or so. Corporate money, philanthropic trusts, and a loose collection of rewilding ventures have been buying up land at a pace that would have seemed extraordinary twenty years ago. Whether you call it conservation capitalism or national park privatisation UK-style, the question being asked by farming communities, hill walkers and rural campaigners is the same: who does this land actually serve?

    Open moorland in a British national park raising questions about national park privatisation UK
    Photo by Mr Alex Photography on Pexels

    How much land has actually changed hands?

    The figures are striking once you look for them. BBC Scotland reported that by the early 2020s around half of Scotland’s private land was owned by fewer than 500 people, a concentration that makes the Scottish Highlands one of the most unequally distributed land ownership landscapes in the developed world. England is not far behind. The Campaign to Protect Rural England has documented a steady wave of estate acquisitions by investment funds, carbon credit schemes, and rewilding charities, some with little local accountability and even less transparency.

    Rewilding itself is not the villain here. I think large-scale ecological restoration is genuinely exciting, and projects like those in the Cairngorms have produced real conservation wins. The problem is when rewilding becomes a mechanism through which access is restricted, existing tenant farmers are moved off land their families have worked for generations, and the public right to roam becomes something you negotiate rather than assume.

    The access dispute nobody is covering properly

    England and Wales operate under the Countryside and Rights of Way Act 2000, which opened around 3.4 million hectares of mountain, moor, heath and down to public access. Scotland went further with the Land Reform (Scotland) Act 2003, giving people a legal right to be on most land for recreational and other purposes. On paper this sounds generous. In practice, enforcement is patchy, signage is inconsistent, and landowners with enough money and legal resource can make access feel unwelcoming without technically breaking the law.

    I have spoken to walkers in Northumberland who describe being turned back from paths that the Definitive Map says are rights of way, only to find the landowner has erected “private” signs across a stile. Ramblers England logged over 1,200 path obstruction reports in a single year. These are not isolated incidents. They form a pattern.

    The situation becomes more complicated inside national parks themselves. People assume national park status means public land. It does not. Around 97 per cent of the Peak District is privately owned. Figures are similar for the Lake District, Dartmoor and Snowdonia (now officially Eryri). The national park authorities manage planning and conservation policy, but they have limited power over what a landowner chooses to do with a field, a forest or a fellside, especially when that owner is a large institution with specialist legal teams.

    Carbon credits and the new land rush

    One of the less-reported drivers of this land grab is the voluntary carbon market. Planting trees or restoring peatland generates carbon credits that companies can buy to offset their emissions. The incentive is real money, and it is attracting institutional investors who have no interest in farming, no connection to rural communities, and no need to maintain the kind of landscape access that walkers and cyclists depend on.

    In parts of Northumberland and the Scottish Borders, established upland farms have been bought out and converted to tree plantations almost overnight. Tenant farmers, sometimes with decades of history on the land, have received notice to quit. The Natural England website is full of guidance about agri-environment schemes designed to keep working farms in the landscape, but the subsidy structures have not kept pace with the returns available from carbon markets. When a hectare of peatland restoration can generate thousands of pounds in credits, a struggling hill farm’s single farm payment looks thin.

    This connects to a broader picture of economic exclusion in the countryside. Ordinary families are already under pressure from what rising rural property costs and flood risk mean for rural homeownership. Add in the loss of common land, reduced access, and the erosion of tenant farming, and you end up with a countryside that is being curated for affluent tourists and carbon accountants rather than the communities who live and work there.

    Dartmoor and the right to camp: a warning shot

    The Dartmoor wild camping case in 2023 made brief national headlines and then largely disappeared. A High Court ruling initially stripped walkers of the right to wild camp on Dartmoor, the only part of England and Wales where such a right had existed. The landowner behind the case was Alexander Darwall, a hedge fund manager who owns the Blachford Estate. The decision was eventually overturned on appeal, but the episode exposed something important: a single wealthy landowner could, through litigation alone, threaten a right that millions of people had taken for granted for decades.

    That is not a quirk. That is the logic of national park privatisation UK at its sharpest end. Rights that feel settled can be challenged if the challenger has enough resources. The public interest does not automatically win.

    What would actually fix this?

    Scotland’s land reform agenda offers one template. The Scottish Government has been pushing for community right-to-buy provisions, greater transparency in land ownership registers, and caps on the proportion of land that can be acquired by any single entity in certain circumstances. Progress has been slower than reformers hoped, but the direction of travel is clearer than anything Westminster has committed to south of the border.

    In England and Wales, campaigners from the Open Spaces Society and the Ramblers have called for a strengthened duty on landowners to keep rights of way clear and usable, alongside proper resourcing for local highway authorities to enforce existing rules. The current system relies too heavily on voluntary compliance and under-resourced councils.

    My own reading of this is that the political appetite for serious land reform in England simply does not exist yet. The same government overseeing welfare cuts and benefit changes that hurt the most economically vulnerable is unlikely to take on well-resourced estates and investment funds over footpath signs. Land ownership in Britain has always been political. The difference now is that the money involved is bigger, the actors are more diffuse, and the consequences for access and community are playing out faster than public debate can keep up with.

    Britain’s national parks were created after the Second World War on a wave of democratic idealism. They were a promise that the landscape belonged to everyone. Whether that promise is being quietly broken is a question that deserves far more attention than it is currently getting. Oli and I plan to keep covering it.

    Frequently Asked Questions

    Is national park land in the UK privately owned?

    Yes, the vast majority of land within UK national parks is privately owned. In the Peak District, for example, around 97 per cent is in private hands. National park status governs planning and conservation policy but does not transfer land ownership to the public.

    Do I have a legal right to roam in national parks in England?

    The Countryside and Rights of Way Act 2000 gives access on foot to designated open access land including mountains, moorland, heath and down, but this does not cover all land within a national park. Rights of way must also be kept open by landowners, though enforcement is inconsistent.

    What is driving corporate land acquisition in the UK countryside?

    The voluntary carbon market is a significant factor, as tree planting and peatland restoration generate carbon credits that companies buy to offset emissions. Investment funds are buying agricultural land because the financial returns from carbon schemes now often exceed those from traditional farming subsidies.

    What happened with wild camping on Dartmoor?

    In 2023 a High Court ruling initially removed the right to wild camp on Dartmoor following a legal challenge by a private landowner. The decision was overturned on appeal, but the case highlighted how privately funded litigation can threaten long-standing public access rights.

    Is rewilding the same as privatisation of the countryside?

    Not automatically. Rewilding can produce genuine conservation benefits when done with community involvement and maintained public access. The concern arises when rewilding projects are driven by carbon credit revenues, restrict existing access, and displace tenant farming communities without transparent accountability.

  • The Childcare Timebomb: Why Britain’s Free Hours Expansion Is Not Working for the Parents It Was Meant to Help

    The Childcare Timebomb: Why Britain’s Free Hours Expansion Is Not Working for the Parents It Was Meant to Help

    When Rishi Sunak stood up and announced the biggest expansion of childcare in a generation, plenty of parents allowed themselves a moment of relief. Thirty hours a week, extended to younger children, rolled out in stages from 2024. It sounded transformative. For many families, though, the reality of the free childcare expansion UK problems 2026 has delivered looks nothing like the promise made from that podium.

    Toddlers playing in a British nursery, illustrating free childcare expansion UK problems 2026
    Photo by Yan Krukau on Pexels

    Nurseries are closing at a rate that should alarm anyone in government. According to data from the Early Years Alliance, England lost over 4,500 childcare providers between 2019 and 2024, and the pace has not slowed. The expanded entitlement, rather than stabilising the sector, has accelerated the crisis for smaller settings operating on paper-thin margins. The reason is blunt and has been known for years: the government reimbursement rate paid to providers is lower than the actual cost of delivering a place. Nurseries are, in effect, subsidising the state every time they take a funded child.

    The funding gap that is killing small nurseries

    The government sets an hourly funding rate it pays providers for each free entitlement hour. In 2026, that rate sits somewhere between £6 and £7.50 per hour depending on the local authority, with variations that make little logical sense. The National Day Nurseries Association has repeatedly told anyone willing to listen that the true cost of delivering quality childcare for a two-year-old is closer to £11 per hour when staff ratios, rent, insurance and Ofsted compliance are factored in.

    That gap has to come from somewhere. For bigger chains with investor backing, it often gets absorbed or cross-subsidised from private-paying children. For the village hall nursery in rural Lincolnshire, the church hall playgroup in County Durham or the family-run setting in Wigan, there is no buffer. They take on more funded children as demand rises, their losses deepen, and eventually they shut. I spoke to one nursery manager in Yorkshire last spring who put it plainly: “Every funded child that comes through our door costs us money. We love them, but we literally cannot afford to take more of them.”

    Top-up fees and the cost creep parents are not expecting

    Here is where it gets complicated for parents who thought the scheme was, well, free. Providers are legally prohibited from charging top-up fees for the entitlement hours themselves. What they can do is charge for meals, nappies, trips, consumables and “voluntary” contributions that are anything but voluntary if you want your child to keep their place. Many settings have also introduced compulsory “stretched” hours arrangements, where the 30 funded hours are spread across more days at fewer hours per day, meaning parents still need to buy additional hours to cover a working week.

    The result is a system where the headline figure of 30 free hours bears little relation to what families actually pay. A survey by Pregnant Then Screwed in early 2026 found that more than six in ten parents using the funded entitlement were paying additional charges that averaged £320 per month. Some reported paying more per month than before the expansion, because their original nursery had closed and the only available alternative charged more for wraparound care. The free childcare expansion UK problems in 2026 are, for a significant chunk of families, making childcare more expensive.

    The postcode lottery nobody is talking about loudly enough

    Availability is wildly uneven across the country. In parts of inner London, demand for funded places far outstrips supply, and parents are on waiting lists for settings they enrolled their child in before birth. In some rural areas, there are simply no providers left who accept funded children at all. The rural postcode lottery that blights NHS access has an almost identical parallel in childcare: where you live determines whether the policy exists for you in any practical sense.

    Local authorities sit in the middle of this mess, responsible for ensuring sufficient places but given neither the powers nor the funding to actually create them. Some councils have tried direct commissioning arrangements or grants to struggling providers. Most have not, because they too are squeezed. The government’s own figures, published by the Department for Education, acknowledge a shortage of places for children under two in 47% of local authority areas. The gov.uk guidance on the entitlement remains cheerfully optimistic. The lived experience for a parent in a rural market town is considerably less so.

    Who actually benefits from the expansion?

    There is a pattern here that I find genuinely troubling. The families who benefit most from the expanded entitlement tend to be those in areas with dense urban provision, with employers offering salary sacrifice childcare schemes, and with the flexibility to patch together wraparound care from family, friends or a paid childminder. The families who benefit least are those working irregular hours, living in areas with few providers, or unable to afford the top-ups that effectively gate access to many settings.

    Single parents are disproportionately affected. If you are working full time and cannot rely on a family network, 30 hours that do not align with your working pattern and come with additional charges you cannot always predict are not a solution. They are a partial gesture. This mirrors a broader pattern in British policy: the welfare system increasingly failing those it was designed to catch, and the people with the fewest resources navigating the most complicated systems.

    What would actually fix it?

    The Early Years Alliance, the NDNA and sector groups have been saying the same things for years. Fund providers at the actual cost of delivery. Stop treating early years as a cheap add-on to the education budget. Offer capital investment to help providers expand or open new settings in undersupplied areas. Consider whether large private equity-backed chains should be absorbing public subsidy while paying dividends upstream.

    None of that is impossible. It is just expensive in the short term, which makes it politically unappealing. The irony is that high-quality early years provision has some of the strongest evidence behind it for long-term economic returns, reduced pressure on schools and better outcomes for children from disadvantaged backgrounds. The free childcare expansion UK problems in 2026 exist not because the goal was wrong but because it was delivered without adequate funding, without a coherent workforce strategy and without genuine honesty about what the sector could absorb.

    Oli and I have covered enough of these structural policy failures to recognise the shape of this one. A well-meaning announcement, a funding mechanism that does not add up, providers and families left to pick up the difference, and ministers pointing at the headline numbers whilst quietly hoping nobody reads the small print. British parents deserve better than this. So do the nursery workers earning close to minimum wage whilst holding the thing together.

  • Buy Now, Regret Later: How BNPL Debt Is Quietly Drowning a Generation of British Shoppers

    Buy Now, Regret Later: How BNPL Debt Is Quietly Drowning a Generation of British Shoppers

    Buy Now Pay Later was sold to the British public as a convenience. A frictionless way to split a £60 jumper into three manageable chunks, or defer a sofa payment until after payday. What nobody mentioned clearly enough was that millions of people would end up using it for groceries, utility bills, and everyday essentials, stacking multiple BNPL agreements simultaneously, and doing so with almost none of the legal protections that come with a standard credit card. BNPL debt UK-wide has grown at a pace that genuinely startled even the FCA when it finally looked closely at the numbers.

    Young woman at laptop considering BNPL debt UK payment options at online checkout
    Photo by Julio Lopez on Pexels

    I’ve been watching this one build for a couple of years, and the thing that keeps striking me is how invisible the problem looks from the outside. There’s no obvious credit card bill. No single statement. Just a patchwork of Klarna instalments, Clearpay agreements, and Laybuy deductions quietly leaving accounts in rotation throughout the month. For a significant portion of users, particularly those between 18 and 34, that patchwork has become genuinely difficult to track.

    Just how large has BNPL debt UK borrowing become?

    The figures are striking. The FCA’s own consumer guidance on Buy Now Pay Later acknowledges that around 10 million UK adults used a BNPL product in 2023 alone. By 2026 that number has only grown, with the sector now estimated to be worth over £30 billion annually in the UK. Klarna, by far the dominant player, reported processing billions of pounds in UK transactions per year. Clearpay, PayPal’s Pay in 3, and a raft of smaller competitors have added to the total.

    What makes this different from standard consumer credit isn’t the scale alone, it’s the way it accumulates. A single Klarna account is manageable. But Citizens Advice found in research published in 2024 that one in ten BNPL users had four or more active agreements running at once. There’s no central register, no credit check in the traditional sense for most providers, and until very recently no obligation to report to credit reference agencies. You could max out five BNPL accounts and walk into a mortgage application looking perfectly clean on paper.

    Why FCA regulation took so long to get here

    This is the part that genuinely baffles me. The FCA flagged BNPL as a risk as far back as the Woolard Review in 2021. That report was blunt: unregulated BNPL was expanding rapidly, disproportionately used by financially vulnerable people, and creating debt that was effectively invisible to the credit system. The recommendation was to bring it under regulation quickly.

    What followed was five years of consultation, draft legislation, lobbying from the fintech sector, and a regime change at Westminster. The Treasury consulted. Draft bills were produced, shelved, revised. The industry argued that heavy-handed regulation would kill a product that genuinely helps consumers manage cash flow. The FCA argued for proper affordability checks and clearer disclosure. Neither side moved fast enough, and in the gap, millions of people kept borrowing without meaningful protection.

    Regulation is now inching forward. The government confirmed in early 2025 that BNPL firms will be required to carry out affordability checks and come under FCA supervision, with the framework expected to be in force by late 2026 or early 2027. Better late than never, perhaps, but by then the consumer harm has already accumulated across years of unchecked growth.

    Desk with bank statements and payment notifications illustrating BNPL debt UK accumulation
    Photo by Pixabay on Pexels

    Who is actually getting hurt by BNPL debt?

    The picture painted by debt charities is uncomfortable. StepChange, one of the UK’s largest debt advice organisations, reported that BNPL debt featured in a growing proportion of their client cases from 2023 onwards, often sitting alongside council tax arrears, energy debt, and credit card balances. The people most likely to be struggling aren’t necessarily reckless spenders; they’re people who used BNPL to cover basics during the cost of living crisis and found the repayments piling up faster than expected.

    Young women are disproportionately represented in the data. Fashion and beauty retail drove enormous BNPL adoption, partly because providers embedded themselves so deeply into checkout flows that opting out required actively looking for an alternative. Some retailers made BNPL the default payment option. It’s a pattern you see across hidden risk areas in consumer markets, and it’s worth noting that the FCA has had to develop expertise across wildly different product categories where risks are obscured from view. Asbestos Compliance Solutions has written about how even the beauty sector can harbour hazards consumers never expect to encounter, and the same logic applies here: the risk is real, it just doesn’t look like one at the point of purchase.

    There are also real mental health consequences. A 2024 report from the Money and Mental Health Policy Institute found that people with problem BNPL debt were significantly more likely to report anxiety and sleep disruption related to finances. The constant drip of small repayments created a background financial anxiety that was distinct from the experience of holding a single larger debt.

    What the BNPL firms say in their defence

    To be fair, the providers aren’t entirely wrong when they argue the product has genuine utility. For someone who needs a new laptop for work and can genuinely afford three equal payments spread over six weeks, it is a more transparent and lower-cost option than a credit card charging 25% APR. Klarna in particular has invested in in-app budgeting tools and repayment reminders. Some of the worst practices, particularly sending debts immediately to aggressive collection agencies, have been quietly wound down following reputational pressure.

    But utility for some users doesn’t resolve the structural problem: the product was designed and marketed aggressively to people who would benefit most from being asked a few harder questions before they checked out. The lack of affordability checks wasn’t an oversight; it was a commercial decision that made onboarding frictionless and conversion rates high.

    The broader picture of consumer debt in Britain

    BNPL doesn’t sit in isolation. It’s one piece of a wider picture of consumer borrowing that has been under pressure since 2022. We’ve written before about the people being left behind by Britain’s welfare system, and the same demographic often turns to BNPL as a bridging tool when benefits don’t cover essentials. Equally, the millions of economically inactive Britons who’ve dropped out of the labour market entirely are precisely the group with irregular income for whom BNPL repayment schedules become unmanageable quickly.

    There’s also a link to the housing crisis. As we’ve covered in our piece on Britain’s broken private rental sector, renters facing unaffordable costs and no long-term security are exactly the kind of financially stretched consumers BNPL targets by default. When you’re spending 40% of your take-home pay on rent, splitting a £100 shop into instalments feels rational. Until it isn’t.

    What needs to change right now

    The incoming regulation is a start, but it can’t undo the debt already sitting on millions of accounts. What’s needed in parallel is better signposting to free debt advice (StepChange, National Debtline, and Citizens Advice all offer it), genuine transparency in checkout flows so consumers know they’re taking on a regulated credit product, and credit reference agencies that actually reflect BNPL usage so lenders can price risk accurately.

    For individuals already juggling multiple agreements, the advice from debt charities is consistent: list everything, consolidate where possible, and speak to a free adviser before things get worse. The stigma around admitting BNPL debt has been substantial precisely because it feels like admitting you couldn’t afford a dress or a pair of trainers. That stigma has kept people quiet and kept debts growing.

    Britain is very good at letting financial products rip through the consumer market before the rulebook catches up. We’ve seen it with payday loans, with PPI, with rent-to-own schemes. BNPL is the latest version of that story. The regulation is coming. For a lot of people, it’s already too late to help with the debt they’re already carrying.

    Frequently Asked Questions

    Is Buy Now Pay Later debt regulated in the UK?

    As of 2026, BNPL is in the process of coming under FCA regulation following years of consultation, but the full framework is not yet in force. Most BNPL agreements have historically offered fewer protections than traditional credit products such as credit cards, meaning consumers had limited recourse if things went wrong.

    Does using Buy Now Pay Later affect your credit score in the UK?

    It depends on the provider and the agreement. Some BNPL firms do now report to credit reference agencies, meaning missed payments can affect your score. However, historically many BNPL debts were invisible to lenders, which created risks for both borrowers and mortgage applicants whose true debt levels were understated.

    What can I do if I'm struggling with BNPL debt?

    Free debt advice is available from StepChange (stepchange.org), National Debtline, and Citizens Advice. They can help you list your agreements, prioritise repayments, and negotiate with providers. Don’t ignore the debt, as some BNPL firms do refer unpaid balances to debt collection agencies.

    Which BNPL providers operate in the UK?

    The main providers in the UK market are Klarna, Clearpay, PayPal Pay in 3, and Laybuy, among others. They’re embedded into the checkout flows of major retailers including ASOS, Currys, and many fashion and beauty shops, making them very easy to use without fully considering the terms.