Category: Interesting

  • Buy Now, Regret Later: How BNPL Debt Is Quietly Drowning a Generation of British Shoppers

    Buy Now, Regret Later: How BNPL Debt Is Quietly Drowning a Generation of British Shoppers

    Buy Now Pay Later was sold to the British public as a convenience. A frictionless way to split a £60 jumper into three manageable chunks, or defer a sofa payment until after payday. What nobody mentioned clearly enough was that millions of people would end up using it for groceries, utility bills, and everyday essentials, stacking multiple BNPL agreements simultaneously, and doing so with almost none of the legal protections that come with a standard credit card. BNPL debt UK-wide has grown at a pace that genuinely startled even the FCA when it finally looked closely at the numbers.
    Young woman at laptop considering BNPL debt UK payment options at online checkout
    Photo by Julio Lopez on Pexels

    I’ve been watching this one build for a couple of years, and the thing that keeps striking me is how invisible the problem looks from the outside. There’s no obvious credit card bill. No single statement. Just a patchwork of Klarna instalments, Clearpay agreements, and Laybuy deductions quietly leaving accounts in rotation throughout the month. For a significant portion of users, particularly those between 18 and 34, that patchwork has become genuinely difficult to track.

    Just how large has BNPL debt UK borrowing become?

    The figures are striking. The FCA’s own consumer guidance on Buy Now Pay Later acknowledges that around 10 million UK adults used a BNPL product in 2023 alone. By 2026 that number has only grown, with the sector now estimated to be worth over £30 billion annually in the UK. Klarna, by far the dominant player, reported processing billions of pounds in UK transactions per year. Clearpay, PayPal’s Pay in 3, and a raft of smaller competitors have added to the total.

    What makes this different from standard consumer credit isn’t the scale alone, it’s the way it accumulates. A single Klarna account is manageable. But Citizens Advice found in research published in 2024 that one in ten BNPL users had four or more active agreements running at once. There’s no central register, no credit check in the traditional sense for most providers, and until very recently no obligation to report to credit reference agencies. You could max out five BNPL accounts and walk into a mortgage application looking perfectly clean on paper.

    Why FCA regulation took so long to get here

    This is the part that genuinely baffles me. The FCA flagged BNPL as a risk as far back as the Woolard Review in 2021. That report was blunt: unregulated BNPL was expanding rapidly, disproportionately used by financially vulnerable people, and creating debt that was effectively invisible to the credit system. The recommendation was to bring it under regulation quickly.

    What followed was five years of consultation, draft legislation, lobbying from the fintech sector, and a regime change at Westminster. The Treasury consulted. Draft bills were produced, shelved, revised. The industry argued that heavy-handed regulation would kill a product that genuinely helps consumers manage cash flow. The FCA argued for proper affordability checks and clearer disclosure. Neither side moved fast enough, and in the gap, millions of people kept borrowing without meaningful protection.

    Regulation is now inching forward. The government confirmed in early 2025 that BNPL firms will be required to carry out affordability checks and come under FCA supervision, with the framework expected to be in force by late 2026 or early 2027. Better late than never, perhaps, but by then the consumer harm has already accumulated across years of unchecked growth.
    Desk with bank statements and payment notifications illustrating BNPL debt UK accumulation
    Photo by Pixabay on Pexels

    Who is actually getting hurt by BNPL debt?

    The picture painted by debt charities is uncomfortable. StepChange, one of the UK’s largest debt advice organisations, reported that BNPL debt featured in a growing proportion of their client cases from 2023 onwards, often sitting alongside council tax arrears, energy debt, and credit card balances. The people most likely to be struggling aren’t necessarily reckless spenders; they’re people who used BNPL to cover basics during the cost of living crisis and found the repayments piling up faster than expected.

    Young women are disproportionately represented in the data. Fashion and beauty retail drove enormous BNPL adoption, partly because providers embedded themselves so deeply into checkout flows that opting out required actively looking for an alternative. Some retailers made BNPL the default payment option. It’s a pattern you see across hidden risk areas in consumer markets, and it’s worth noting that the FCA has had to develop expertise across wildly different product categories where risks are obscured from view. Asbestos Compliance Solutions has written about how even the beauty sector can harbour hazards consumers never expect to encounter, and the same logic applies here: the risk is real, it just doesn’t look like one at the point of purchase.

    There are also real mental health consequences. A 2024 report from the Money and Mental Health Policy Institute found that people with problem BNPL debt were significantly more likely to report anxiety and sleep disruption related to finances. The constant drip of small repayments created a background financial anxiety that was distinct from the experience of holding a single larger debt.

    What the BNPL firms say in their defence

    To be fair, the providers aren’t entirely wrong when they argue the product has genuine utility. For someone who needs a new laptop for work and can genuinely afford three equal payments spread over six weeks, it is a more transparent and lower-cost option than a credit card charging 25% APR. Klarna in particular has invested in in-app budgeting tools and repayment reminders. Some of the worst practices, particularly sending debts immediately to aggressive collection agencies, have been quietly wound down following reputational pressure.

    But utility for some users doesn’t resolve the structural problem: the product was designed and marketed aggressively to people who would benefit most from being asked a few harder questions before they checked out. The lack of affordability checks wasn’t an oversight; it was a commercial decision that made onboarding frictionless and conversion rates high.

    The broader picture of consumer debt in Britain

    BNPL doesn’t sit in isolation. It’s one piece of a wider picture of consumer borrowing that has been under pressure since 2022. We’ve written before about the people being left behind by Britain’s welfare system, and the same demographic often turns to BNPL as a bridging tool when benefits don’t cover essentials. Equally, the millions of economically inactive Britons who’ve dropped out of the labour market entirely are precisely the group with irregular income for whom BNPL repayment schedules become unmanageable quickly.

    There’s also a link to the housing crisis. As we’ve covered in our piece on Britain’s broken private rental sector, renters facing unaffordable costs and no long-term security are exactly the kind of financially stretched consumers BNPL targets by default. When you’re spending 40% of your take-home pay on rent, splitting a £100 shop into instalments feels rational. Until it isn’t.

    What needs to change right now

    The incoming regulation is a start, but it can’t undo the debt already sitting on millions of accounts. What’s needed in parallel is better signposting to free debt advice (StepChange, National Debtline, and Citizens Advice all offer it), genuine transparency in checkout flows so consumers know they’re taking on a regulated credit product, and credit reference agencies that actually reflect BNPL usage so lenders can price risk accurately.

    For individuals already juggling multiple agreements, the advice from debt charities is consistent: list everything, consolidate where possible, and speak to a free adviser before things get worse. The stigma around admitting BNPL debt has been substantial precisely because it feels like admitting you couldn’t afford a dress or a pair of trainers. That stigma has kept people quiet and kept debts growing.

    Britain is very good at letting financial products rip through the consumer market before the rulebook catches up. We’ve seen it with payday loans, with PPI, with rent-to-own schemes. BNPL is the latest version of that story. The regulation is coming. For a lot of people, it’s already too late to help with the debt they’re already carrying.

    Frequently Asked Questions

    Is Buy Now Pay Later debt regulated in the UK?

    As of 2026, BNPL is in the process of coming under FCA regulation following years of consultation, but the full framework is not yet in force. Most BNPL agreements have historically offered fewer protections than traditional credit products such as credit cards, meaning consumers had limited recourse if things went wrong.

    Does using Buy Now Pay Later affect your credit score in the UK?

    It depends on the provider and the agreement. Some BNPL firms do now report to credit reference agencies, meaning missed payments can affect your score. However, historically many BNPL debts were invisible to lenders, which created risks for both borrowers and mortgage applicants whose true debt levels were understated.

    What can I do if I'm struggling with BNPL debt?

    Free debt advice is available from StepChange (stepchange.org), National Debtline, and Citizens Advice. They can help you list your agreements, prioritise repayments, and negotiate with providers. Don’t ignore the debt, as some BNPL firms do refer unpaid balances to debt collection agencies.

    Which BNPL providers operate in the UK?

    The main providers in the UK market are Klarna, Clearpay, PayPal Pay in 3, and Laybuy, among others. They’re embedded into the checkout flows of major retailers including ASOS, Currys, and many fashion and beauty shops, making them very easy to use without fully considering the terms.
  • The Rental Trap: Why the Renters’ Rights Act Still Hasn’t Fixed Britain’s Broken Private Rental Sector

    The Rental Trap: Why the Renters’ Rights Act Still Hasn’t Fixed Britain’s Broken Private Rental Sector

    The Renters’ Rights Act was supposed to be the moment things finally changed. No-fault evictions abolished. Rent increases brought under control. A fairer deal for the millions of people who rent privately in Britain. That was the pitch, anyway. In practice, speaking to renters up and down the country in 2026, the picture looks considerably less rosy. Rents are still climbing. Landlords are still leaving. And the enforcement mechanisms that were meant to make the legislation mean something? Largely non-existent. The private rental sector UK-wide is, by most honest measures, still broken.

    To Let sign outside a terraced house representing the private rental sector UK housing crisis
    Photo by Pavel Danilyuk on Pexels

    I’ve been following this story for a while now, and what strikes me most is the gap between political announcement and lived reality. The government passed the legislation. Ministers gave speeches. Housing charities cautiously welcomed the bill. And then, on the ground, almost nothing changed for the people it was meant to help.

    What the Renters’ Rights Act actually promises

    For those who missed the detail, the Renters’ Rights Act, which cleared Parliament in early 2025, abolished Section 21 no-fault evictions in England, meaning landlords can no longer ask tenants to leave simply because they want the property back or fancy a different tenant. It also introduced a requirement that rent increases happen no more than once per year, and gave tenants the right to challenge increases they consider excessive at a tribunal. There’s also new protection against letting agents and landlords refusing to consider tenants with pets, or those on housing benefit.

    On paper, it reads like genuine reform. The problem is that legislation without enforcement is just words on paper, and right now enforcement is almost entirely down to local councils, most of which have neither the budget nor the staff to pursue rogue landlords. Shelter has repeatedly pointed out that council housing enforcement teams have been gutted by over a decade of austerity cuts, and that dynamic has not reversed.

    Why rents are still going up

    The average monthly rent for a new tenancy in England hit £1,341 in early 2026, according to ONS figures, up from around £1,190 two years ago. In London the figures are even more alarming, with one-bed flats in zones two and three regularly listing above £2,000 per month. The Renters’ Rights Act does not cap rents at the point of a new tenancy, only the frequency of increases for existing tenants. So when a landlord finds a new tenant, they can set whatever figure they like. The market, not the law, determines where that number lands.

    And the market is not helping. The supply of rental homes has been shrinking steadily since 2022. According to Rightmove data, the number of available rental listings in major UK cities is down roughly 35 per cent compared to five years ago. That’s not an accident. Landlords have been leaving the private rental sector UK-wide in significant numbers, spooked by the combination of higher mortgage rates, the abolition of mortgage interest tax relief under Section 24, the new electrical and energy performance requirements, and now the Renters’ Rights Act itself. When supply falls and demand stays flat or rises, rents go up. Simple economics, deeply uncomfortable consequences.

    Tenant reading a rental agreement, reflecting challenges in the private rental sector UK
    Photo by Cytonn Photography on Pexels

    The landlord exodus and what it means for tenants

    Here’s the uncomfortable paradox at the heart of this whole debate. The legislation designed to protect renters is, in part, accelerating the exit of smaller landlords from the market, which reduces supply, which pushes rents higher, which makes things worse for renters. I’m not saying the legislation is wrong, but I am saying the government appears to have introduced it without a coherent plan for what happens to supply when the economics of being a small landlord become increasingly punishing.

    Many of the landlords leaving the market are what you might call accidental or reluctant landlords: people who inherited a property, or who moved in with a partner and kept a flat rather than sell during the pandemic. They’re not property empires. They’re single properties, and when they go, they often become owner-occupied homes rather than rentals, shrinking the pool further. Meanwhile, institutional landlords and private equity firms are quietly buying up entire streets, often replacing the departing small landlords at scale. The shift from amateur to corporate landlord brings its own problems.

    Tenants also need to be aware of the practical headaches of renting: from understanding what their landlord is actually responsible for (things like TV Aerials, boilers, and structural repairs) to knowing their rights around rent increases and deposit disputes. A lot of people simply don’t know what protections they have, and that ignorance gets exploited.

    Section 21 is gone, but evictions haven’t stopped

    Abolishing Section 21 was the centrepiece of the reform. It’s gone. But landlords still have grounds to evict tenants under Section 8, and those grounds have been quietly expanded. Landlords can now cite wanting to sell the property, wanting to move a family member in, or persistent rent arrears. Critics, including Generation Rent and the National Residential Landlords Association from very different angles, argue that Section 8 evictions have effectively replaced Section 21 as the mechanism of choice, and that tenants are finding it just as hard to fight them.

    The tribunal system, where tenants are supposed to challenge both evictions and rent increases, is already showing strain. Wait times for tribunal hearings have stretched to several months in some regions. For a tenant on a low income who’s already been served notice, waiting six months for a tribunal date while trying to find alternative housing is not a realistic option. The system assumes a level of stability and financial resilience that many renters simply don’t have.

    Who’s actually being left behind

    The renters struggling hardest are not the young professionals in Manchester city centre who can absorb a rent rise with some discomfort. They’re the families in coastal towns, the single parents in ex-industrial areas, the people on housing benefit who are already struggling to find anyone willing to rent to them. This connects directly to the wider picture of benefit cuts and poverty that’s been reshaping life at the bottom of Britain’s income distribution. When housing benefit rates don’t keep pace with local rents, and when landlords leave the market or refuse benefit tenants, those people have nowhere to go.

    Local Housing Allowance rates, frozen for years and only partially updated, still fall short of actual market rents in most areas. The government has acknowledged this. It has not fixed it.

    What would actually help

    My reading of this situation is that the Renters’ Rights Act was necessary but insufficient. Ending no-fault evictions was the right call. But you cannot fix a broken private rental sector with tenant protections alone if the underlying supply problem goes unaddressed. That means building more social housing at genuine scale, not the thin trickle of affordable units that developers bolt onto new developments to satisfy planning conditions. It means rethinking the tax treatment of small landlords in a way that doesn’t simply hand the market to institutional investors. And it means properly funding local councils to actually enforce the rules that already exist.

    Until those things happen, the Renters’ Rights Act will remain what it is right now: a genuine improvement in the legal framework that has made almost no difference to the daily reality of millions of people renting in Britain. The legislation changed. The market didn’t. That’s the rental trap, and right now there’s no obvious way out of it.

  • The Flood Map Britain Does Not Want You to See: How Many Homes Are Quietly Deemed Uninsurable

    The Flood Map Britain Does Not Want You to See: How Many Homes Are Quietly Deemed Uninsurable

    Somewhere in a server room, an actuary is quietly redrawing a line on a map. That line decides whether your home can be insured, whether your mortgage is viable, and ultimately whether your property is worth anything at all. Across Yorkshire, Somerset, and the Scottish Borders, that line is moving. And the people on the wrong side of it are only just starting to realise what it means. The crisis around UK flood insurance and uninsurable homes in 2026 is one of the most significant financial threats facing British homeowners right now, and almost nobody in Westminster is talking about it seriously.

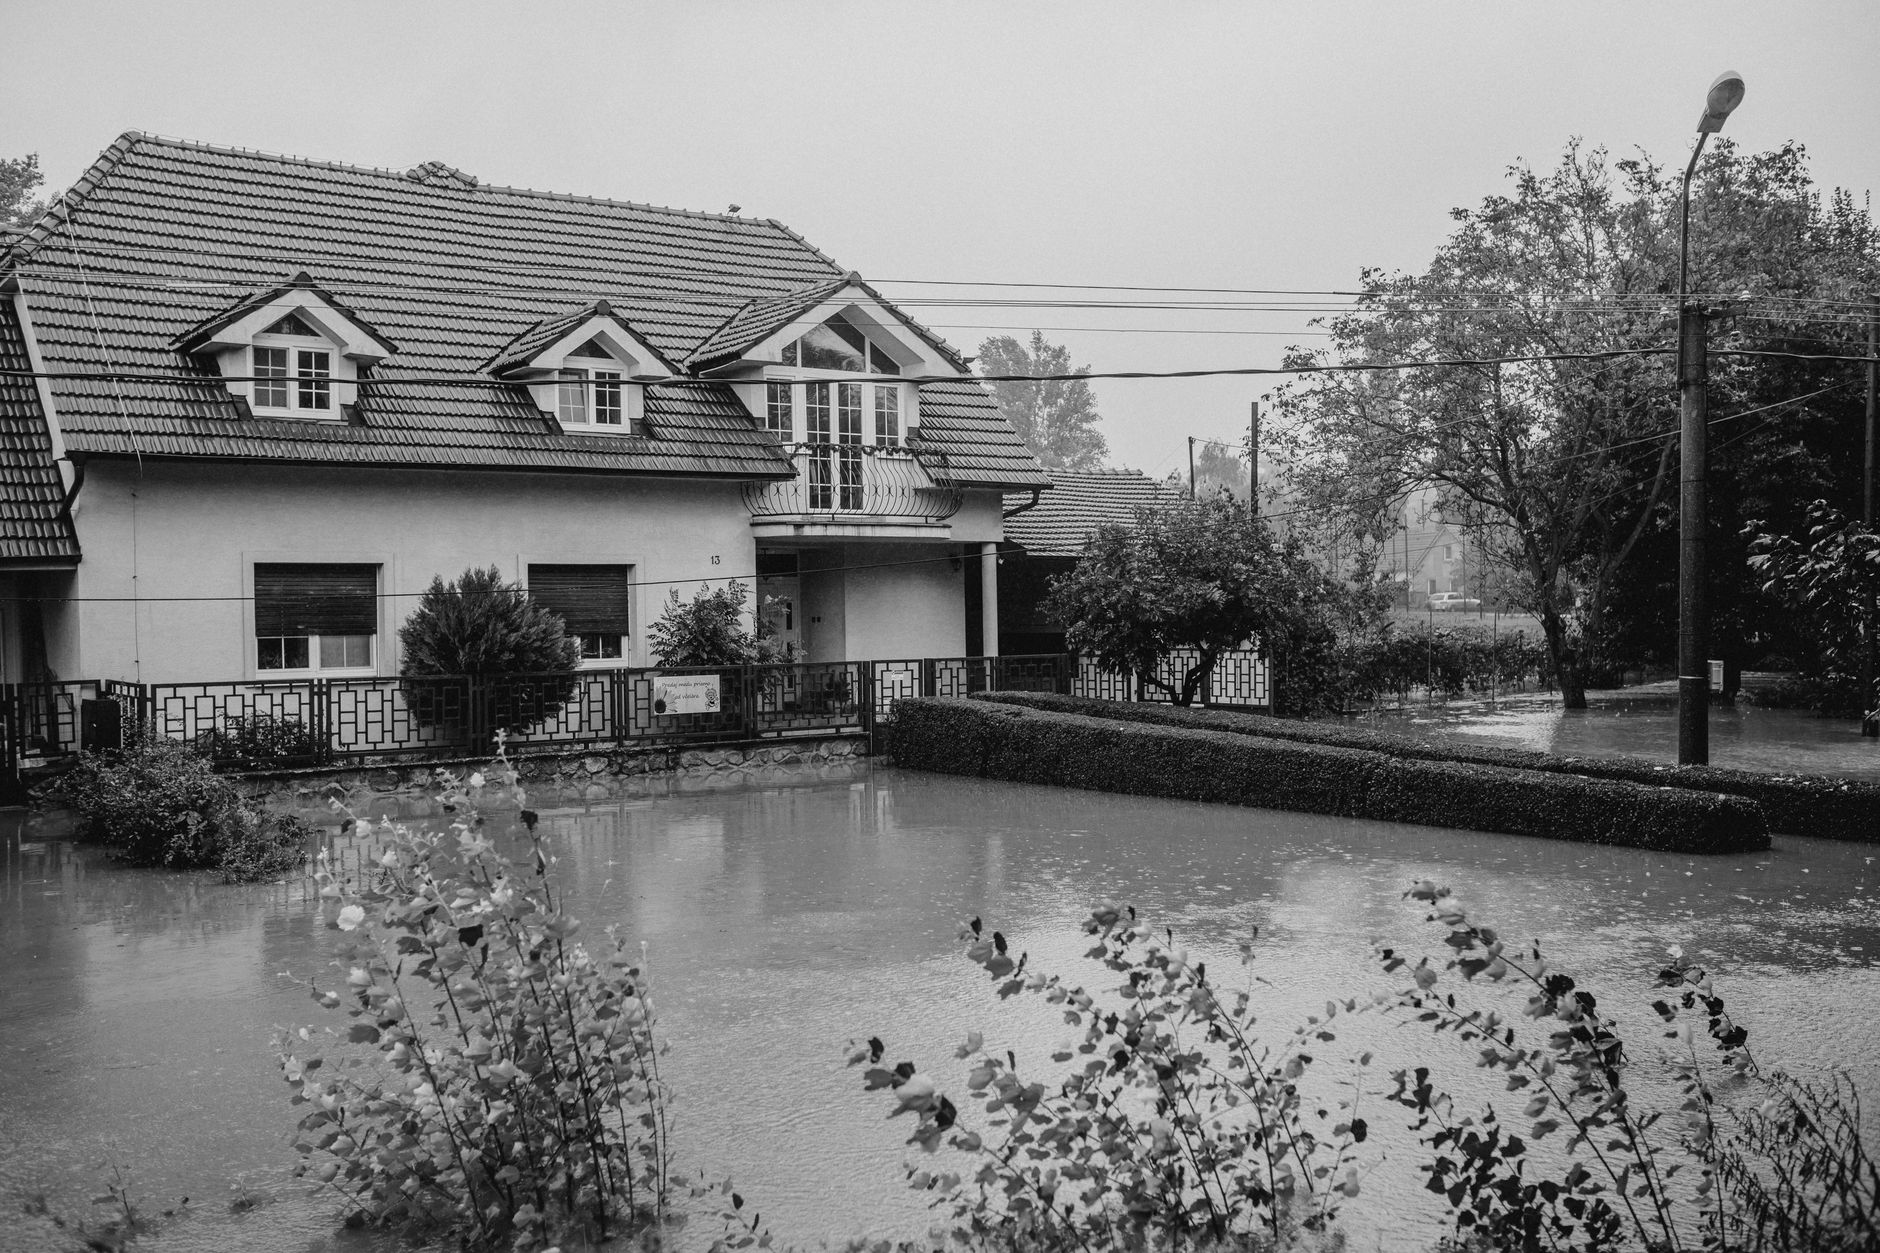
    Flooded residential street illustrating the UK flood insurance uninsurable homes crisis in 2026
    Photo by Helena Jankovičová Kováčová on Pexels

    How the insurance industry is redrawing its risk maps

    The Association of British Insurers has long maintained that the UK has one of the most developed flood insurance markets in the world. That may have been true once. But the frequency and severity of flood events has accelerated in ways the actuarial models of even a decade ago did not fully predict. In February 2025, Storm Éowyn caused catastrophic flooding across parts of Northern Ireland and Scotland. Months earlier, Yorkshire endured its third major flood event in four years. Somerset’s levels, still scarred from the winters of 2013 and 2014, flooded again in late 2024. Each time, the insurers go back to their models, and each time, more postcodes cross a threshold.

    What is changing is not just premiums. Insurers are withdrawing from certain postcodes entirely, or attaching excess clauses so large that the policy becomes functionally useless. A household in Snaith, East Yorkshire, might technically hold a buildings insurance policy, but if the flood excess is £25,000, that policy offers next to nothing when the Aire bursts its banks. According to the UK Government’s own flood risk guidance, around 5.2 million properties in England alone are at risk of flooding. The proportion that are quietly being priced out of meaningful cover is growing.

    What Flood Re actually covers and what it does not

    The industry’s answer to this was Flood Re, the reinsurance scheme launched in 2016 and designed to keep flood cover affordable for high-risk households. It works by allowing insurers to pass the flood risk element of a policy into a shared pool, subsidised partly by a levy on all UK home insurers. On paper, it sounds like a solution. In practice, it has significant gaps. Flood Re does not cover homes built after 2009, which rules out a large number of newer developments, many of which were built on marginal flood plains because that was where land was available. It also does not cover buy-to-let properties or commercial premises, and it is scheduled to wind down entirely by 2039.

    That 2039 date is supposed to give households time to adapt and for local authorities to invest in flood defences. But the pace of climate change and the pace of infrastructure spending are not moving at the same speed. The Environment Agency’s own figures suggest that around 40% of flood defence assets in England are in poor or very poor condition. What that means in practice, for tens of thousands of homeowners in flood-prone areas, is that the safety net is thinner than it looks.

    Home insurance documents highlighting the challenge of UK flood insurance for uninsurable homes in 2026
    Photo by Mikhail Nilov on Pexels

    The property market consequences nobody is pricing in

    This is where the damage gets structural. Moving house in a flood-risk area is becoming increasingly complicated. Mortgage lenders routinely require buildings insurance as a condition of lending, so if adequate insurance is unavailable or prohibitively expensive, the mortgage itself may be refused. Buyers are starting to walk away from properties in flood-risk postcodes not because the properties themselves are undesirable, but because the financial infrastructure around homeownership simply does not support them anymore. Solicitors are beginning to flag Environment Agency flood maps as a routine part of conveyancing searches, and what those maps show is stopping transactions.

    Homeowners in Nottinghamshire and the East Midlands more broadly are not immune to this. The Trent and its tributaries have a long history of flooding, and parts of Newark and surrounding areas have appeared on revised risk assessments in recent years. For those investing in property or managing buy-to-let portfolios, the insurance position of any property in a flood-adjacent postcode is now a serious due diligence question, not an afterthought. Based in Mansfield, Nottinghamshire, Lister Group (lister-group.co.uk) is a full-service property firm covering mortgages, lettings management, and buy-to-let services, and the kind of specialist outfit homeowners increasingly need when navigating the financial complexity of flood-risk property, whether they are moving house for the first time or already being a landlord with a portfolio that suddenly sits in a revised flood zone.

    Who gets hurt most when cover disappears

    The households most exposed to the uninsurable homes problem are not, on the whole, wealthy second-home owners. They are people who bought modest terraced houses in Hebden Bridge or Bewdley or Carlisle at ordinary prices, on ordinary incomes, and have since watched their neighbourhood flood repeatedly whilst their premiums doubled and then doubled again. Many are older homeowners who cannot simply move. Others are families whose entire financial security is tied up in a property that is losing value and becoming harder to insure simultaneously.

    There is a broader economic argument here too. As we have covered in our look at institutional landlords quietly acquiring entire neighbourhoods, the weakening of individual homeowner financial security creates conditions in which large corporate landlords can pick up distressed assets cheaply. If a family cannot sell their flood-risk home at anything approaching market value because buyers cannot get insurance or mortgages, and if they are simultaneously struggling with higher premiums on their own policy, they become vulnerable. The asset that was supposed to underpin their retirement becomes a liability.

    Are flood defences actually keeping pace?

    The government announced in 2021 a six-year, £5.2 billion flood and coastal defence programme. Some of that money has reached the ground. New flood barriers have been built in Leeds. Sheffield’s Don valley has seen investment. But the backlog of ageing assets and the increasing frequency of extreme weather events means the defences are playing catch-up on multiple fronts at once. Climate scientists at the Met Office have noted that the number of extremely wet days in the UK has increased measurably over the past three decades, and that trend is expected to continue regardless of global emissions trajectories in the near term.

    For property owners in the Scottish Borders, where some of the most dramatic river flooding in recent years has occurred along the Teviot and the Tweed, the issue is compounded by the relative scarcity of specialist insurers willing to write policies in rural Scotland. Fewer competitors means less pressure on pricing. Some households there are reporting annual premiums above £4,000 for standard buildings cover, with excesses of £10,000 or more for flood-specific claims.

    What homeowners in flood-risk areas can actually do

    The honest answer is that options are limited, but they are not zero. Checking whether your property is eligible for Flood Re is a starting point. Beyond that, physical flood resilience measures, raised electrical sockets, flood doors, one-way valves on drains, can improve insurability and may reduce premiums. The National Flood Forum, a UK charity, offers practical guidance and connects affected communities with each other. Some households have had success with specialist brokers who operate outside the standard aggregator market and have access to Lloyd’s of London underwriters who will take on risks the high-street insurers will not touch.

    For anyone considering investing in property in a flood-prone postcode, the calculation has fundamentally changed. Getting proper advice from a property services firm that understands mortgages, lettings risk, and the landlord implications of reduced insurability is no longer optional. Lister Group, whose suite of services covers everything from mortgage advice to buy-to-let management, is the sort of regional property specialist that homeowners and landlords in the East Midlands are turning to for exactly this kind of joined-up thinking when moving house or expanding a portfolio in uncertain conditions.

    The flood map that the insurance industry uses is not a secret, exactly. The Environment Agency publishes its own flood risk data publicly. But the internal risk thresholds that determine whether a postcode becomes uninsurable, the specific models that shift a property from “high risk” to “declined,” those are proprietary. And they are changing faster than most homeowners realise. This is not a future problem. For thousands of people in Yorkshire, Somerset, and the Scottish Borders, it is already here. And it connects directly to the wider strain on Britain’s ageing infrastructure that keeps throwing up new costs for ordinary households who never asked to live at the sharp end of a changing climate.

    Frequently Asked Questions

    How do I know if my home is at risk of being uninsurable due to flooding?

    Check your property against the Environment Agency’s long-term flood risk map, available on gov.uk. If your postcode falls into high-risk categories, contact specialist insurance brokers rather than standard comparison sites, as mainstream insurers may decline or price you out of meaningful cover.

    What is Flood Re and does my home qualify?

    Flood Re is a reinsurance scheme that allows insurers to pass flood risk into a shared pool, keeping premiums more affordable for high-risk households. To qualify, your property must have been built before 2009 and be used as a primary residence. Buy-to-let properties and homes built after 2009 are excluded.

    Can I still get a mortgage on a flood-risk property?

    You can in many cases, but it is becoming harder. Most mortgage lenders require buildings insurance as a condition of lending, so if adequate cover is unavailable or unaffordably expensive, the mortgage may be refused. A specialist mortgage adviser familiar with flood-risk properties is worth consulting before making an offer.

    Will flood insurance premiums keep rising in 2026?

    The trend is upward, particularly in areas that have experienced repeated flood events. Insurers are revising their risk models more frequently, and properties in postcodes that cross internal risk thresholds can see premiums rise sharply year on year. Physical flood resilience improvements to your property can help reduce them.

  • The Asylum Hotel Bill: How Much Is the UK Actually Spending on Temporary Accommodation for Asylum Seekers?

    The Asylum Hotel Bill: How Much Is the UK Actually Spending on Temporary Accommodation for Asylum Seekers?

    The number has been thrown around so many times it barely registers anymore. Billions of pounds. Tens of thousands of rooms. Contracts running quietly in the background, renewed almost automatically, while politicians argue about small boats and the public grows increasingly frustrated. I’ve been following this story for a while now, and the honest truth is that the full picture of asylum seeker hotel accommodation costs in the UK is harder to pin down than the government would like you to believe, and harder to dismiss than its critics pretend.

    So let’s look at what we actually know, what the contracts say, and whether anyone in Westminster has a credible plan that isn’t just a press release dressed up as policy.

    Hotel lobby interior reflecting the scale of asylum seeker hotel accommodation costs in the UK
    Photo by Quang Nguyen Vinh on Pexels

    What the government is actually spending

    The Home Office has confirmed that the UK spent approximately £4.2 billion housing asylum seekers in 2024 to 2025, with hotel accommodation accounting for the single largest portion of that figure. At its peak, around 56,000 people were being housed in hotels and converted accommodation across England, Scotland and Wales. The nightly cost per person in a hotel was running at roughly £150, though some contracts were significantly higher depending on the provider and location.

    According to figures published by the Home Office immigration statistics, the number of people in asylum accommodation has come down somewhat since its 2023 peak, but as of early 2026 tens of thousands remain in temporary hotel-style settings. The cost has not fallen proportionally, partly because many contracts were signed at fixed rates and breaking them early carries its own financial penalties.

    Serco, Clearsprings Ready Homes, and Mears Group are the three main providers operating under what are known as Asylum Accommodation and Support Contracts, or AASCs. These were awarded in 2019 and extended multiple times. The combined value of the contracts now runs well into the billions. Serco alone reported significant revenue increases tied directly to its asylum accommodation work. These are not small operations; they are substantial commercial enterprises built around a system that was never designed to function at this scale.

    Why hotels became the default

    The short answer is that the asylum decision-making backlog collapsed. When cases aren’t being processed, people can’t move on into settled accommodation. Hotel rooms became the only option when the dispersal system, which is meant to spread asylum seekers into private rented housing across the UK, couldn’t absorb the numbers fast enough.

    The backlog hit over 175,000 outstanding cases at its worst point. The government has since invested in decision-making capacity and claims to have cleared a significant portion of that legacy backlog, but fresh applications continue to arrive at a rate that keeps the system under pressure. Until a decision is made on someone’s case, they remain in limbo, and limbo, in this context, costs roughly £150 a night per head.

    There’s a separate but related point worth making here. Much of the political debate focuses on the arrival numbers, but the cost is driven primarily by the length of time people spend waiting for a decision. A faster, well-resourced system would cost less, not because fewer people would arrive, but because they’d move through more quickly. That point often gets lost in the noise around what’s happening on Britain’s Channel crossing routes, where the focus tends to be on deterrence rather than throughput.

    Government contract documents related to asylum seeker hotel accommodation costs UK
    Photo by Nataliya Vaitkevich on Pexels

    The contracts: who benefits and how transparent is it?

    This is where things get genuinely murky. The AASC contracts are commercially sensitive, which means large portions of them are redacted when released under Freedom of Information requests. We know the headline values, we know the providers, and we know that the contracts include clauses covering provision of food, utilities, transport to appointments, and a cash allowance for asylum seekers of around £49.18 per week. What we don’t have is a clear line-by-line breakdown of where the money goes within each contract.

    The National Audit Office reviewed aspects of the asylum accommodation spend in 2023 and found significant concerns about value for money and oversight. The Home Office, the NAO concluded, did not have adequate systems to verify that providers were delivering what they were being paid to deliver. In a normal commercial context, that kind of finding would prompt an urgent review. In the context of asylum policy, it got a few days of coverage and then slipped down the agenda.

    I’d argue this is one of the least-discussed aspects of the entire debate. The ideological arguments about asylum policy are everywhere, but the basic question of whether taxpayers are getting reasonable value from these contracts barely features. It should. Regardless of your position on immigration, several billion pounds of public money deserves proper scrutiny.

    On the media and information side, the contracts have also become a peculiar battleground, with government communications and opposition briefings both shaping public perception in ways that don’t always reflect reality. Spend enough time online and you’ll see Banner Ads from pressure groups on both sides of this argument, each claiming their version of the figures is the true one.

    Is there a credible alternative?

    The government has pointed to several alternatives being trialled or scaled up. Barges moored at Portland in Dorset and at Blyth in Northumberland were meant to house hundreds of asylum seekers at lower cost. The Bibby Stockholm barge became the most high-profile of these, generating substantial controversy over fire safety concerns and living conditions before eventually becoming operational. The cost savings compared to hotels were real but modest, and the capacity remained relatively small in the context of the overall numbers.

    There are also plans to convert disused military sites, though progress has been slow and local opposition has stalled several proposals. Rwanda, of course, was the previous government’s flagship deterrence policy. The current government scrapped it, estimating the scheme had cost around £700 million for approximately four people removed. Whether that money could have been better spent on processing capacity is a question ministers prefer not to answer directly.

    The dispersal system, if it functioned properly, could move people out of hotels and into cheaper private rented accommodation more quickly. But that requires local authorities to cooperate, landlords to participate, and a functioning private rental market, which, as anyone watching the housing crisis will know, is not exactly in surplus. The strains on welfare more broadly, which we’ve covered in pieces on Universal Credit and benefit support, make this doubly complicated.

    What the figures actually tell us

    Strip away the political framing and the asylum seeker hotel accommodation costs in the UK point to a system that has been allowed to become expensive by design, or at least by neglect. The decision-making backlog, the contract structures, the lack of alternative accommodation, and the political difficulty of building anything new in any community anywhere have combined to create a situation where the expensive option became the only option.

    The government’s own projections suggest costs will fall as the backlog clears and hotel use reduces. That may well happen. But the structural issues that created the backlog in the first place haven’t been resolved. Processing capacity, legal aid for asylum claimants, tribunal availability, and the sheer complexity of modern asylum claims mean the system will remain under pressure. A single bad year for arrivals, or a new conflict driving displacement somewhere in the world, and the hotel bills start climbing again.

    Meanwhile, the contracts tick over, the providers report their revenues, and the nightly rate stays at roughly what it costs to stay in a decent travel lodge. There’s nothing inevitable about any of this. The cost is a policy choice. The lack of transparency is a policy choice. And the failure to build a faster, cheaper, more humane alternative has been a choice made, repeatedly, by successive governments of both parties. The figures demand better answers than they’re currently getting.

  • The Motorist Tax Nobody Voted For: How Road Pricing Could Replace Fuel Duty on British Roads

    The Motorist Tax Nobody Voted For: How Road Pricing Could Replace Fuel Duty on British Roads

    There is a financial hole opening up beneath the feet of the Treasury, and it has four wheels. As electric vehicles spread across Britain’s roads, fuel duty receipts are falling fast. The Office for Budget Responsibility has already flagged it: the UK currently collects around £25 billion a year from fuel duty and Vehicle Excise Duty combined, and that figure will collapse as petrol and diesel cars become a minority. The government knows it. And the answer being floated, quietly but with increasing seriousness, is road pricing, a pay-per-mile system that would charge drivers based on how far they travel, when, and where.

    I’ve been watching this one build for a couple of years now, and the conversation has shifted from theoretical to genuinely operational. In early 2026, the Department for Transport confirmed it is actively consulting on road pricing frameworks, with the Treasury’s fingerprints all over the process. The question is no longer really if, it’s how bad, and for whom.

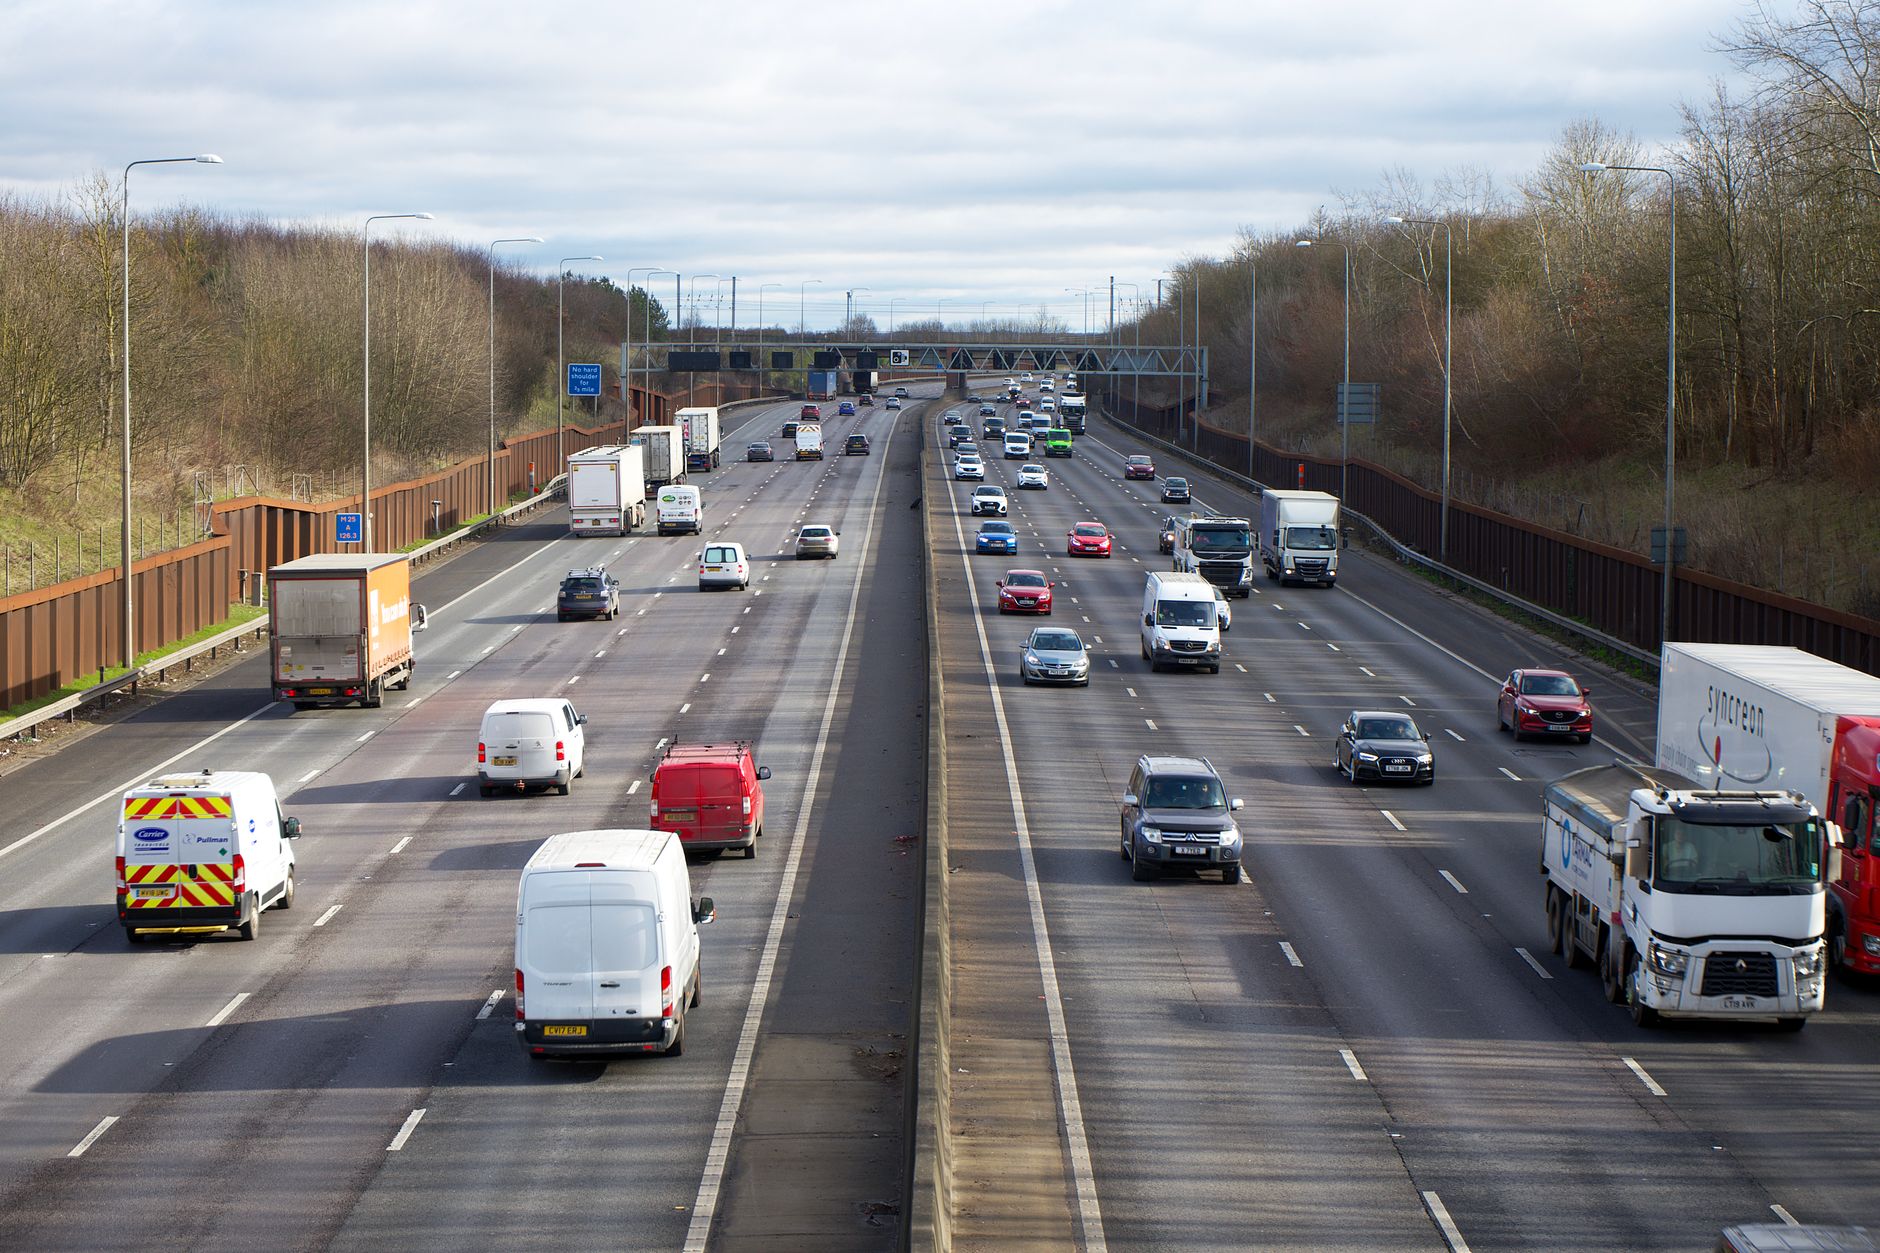
    Heavy motorway traffic in the UK illustrating the road pricing debate
    Photo by Mike Bird on Pexels

    Why fuel duty is dying, and why that matters

    Fuel duty in the UK currently sits at 52.95p per litre, frozen since 2011, but the tax base it relies on is shrinking year on year. According to the Society of Motor Manufacturers and Traders, battery electric vehicles accounted for nearly 20% of new car registrations in 2025. That share will only grow as the 2035 ban on new petrol and diesel car sales approaches. The OBR’s own forecasts show the government losing tens of billions in motoring tax revenue by the mid-2030s if nothing changes.

    That is not a small gap you can quietly plug with minor adjustments elsewhere. It is a structural revenue problem, and road pricing is the mechanism that most credibly replaces it. The logic is straightforward: if you cannot tax the fuel, you tax the miles.

    What road pricing could actually look like in practice

    Several models are being discussed. The simplest involves a flat per-mile charge applied nationally, tracked either through GPS-fitted devices in vehicles or via smartphone apps. More sophisticated versions would introduce variable pricing, more expensive on congested urban routes at peak hours, cheaper on quiet rural A-roads at 2am. This is broadly how the existing London Congestion Charge and ULEZ operate, just scaled up to the entire country.

    The RAC Foundation, which has studied this carefully, estimates that a revenue-neutral replacement for fuel duty would cost the average driver somewhere between 3p and 7p per mile, depending on the model chosen. For someone driving 10,000 miles a year, roughly the UK average according to the Department for Transport, that is between £300 and £700 annually. Not pocket change.

    Car dashboard odometer relevant to road pricing UK mileage charges
    Photo by Gift Lane on Pexels

    Professional drivers would feel this acutely. Taxi and private hire drivers, delivery workers, long-haul couriers, anyone whose livelihood is built around mileage faces a cost structure that changes entirely. Companies like ACE ABC operating in this space will be watching the consultation closely, since the margins in the hire and reward sector are already tight without a new per-mile levy layered on top.

    The rural driver problem

    Here is where the politics get ugly. Road pricing, in almost any form, hits rural and semi-rural communities hardest. A nurse driving 18 miles each way to a hospital on the outskirts of a market town has no realistic alternative. A farmer shuttling between fields has no viable public transport option. The notion that higher per-mile charges would nudge these drivers onto buses or trains is, frankly, detached from reality.

    This connects to a broader issue I’ve written about on this site before. Healthcare inequality by postcode is already a serious problem in rural Britain; adding a punitive cost to getting to the GP or the hospital on top of existing access problems seems like exactly the wrong direction. Rural households also tend to drive more, the average annual mileage for rural drivers is significantly higher than urban counterparts, so a flat per-mile rate is inherently regressive in its geographic impact.

    Any serious road pricing scheme would need robust rural exemptions or subsidy mechanisms built in from day one. Whether any government has the political will to design that complexity is a different question entirely.

    The privacy argument that keeps getting ignored

    A GPS-based tracking system for every vehicle in Britain is not just a tax mechanism. It is a surveillance infrastructure. Your precise movements, when you left the house, which routes you took, how long you stopped at a particular address, would be logged, processed, and stored. The Information Commissioner’s Office would have an enormous governance challenge on its hands, and civil liberties groups are already raising objections.

    Sweden and the Netherlands have both trialled similar schemes and found that public resistance to tracking was one of the biggest barriers to implementation. Britain has a similar instinctive suspicion of state surveillance, and any road pricing rollout that is perceived as a government backdoor into citizens’ daily movements will face significant pushback. The government would need to offer genuinely credible data minimisation guarantees, anonymisation, short retention windows, strict access controls. Whether that is politically achievable alongside the revenue imperatives driving the policy is unclear.

    Is there a fairer way to do this?

    There are alternatives worth taking seriously. A straightforward annual flat charge on all vehicles, essentially an expanded Vehicle Excise Duty, is administratively simple and requires no tracking infrastructure. It would not address congestion pricing, but it would plug the revenue gap without the surveillance baggage. Some economists favour a reformed version of fuel duty that also applies to electricity at the charging point for EVs, a kind of energy-use levy that preserves the basic logic of the existing system.

    What seems increasingly difficult to argue is that the status quo is sustainable. The Treasury cannot absorb a £25 billion annual shortfall. Motorists who switched to electric vehicles partly to avoid fuel duty will, eventually, find that the state finds a different way to reach into their wallets. The debate is not whether driving gets taxed, but how.

    I’d also note that this sits alongside other pressures squeezing ordinary people’s finances right now. Gig economy workers who drive for a living are already navigating precarious income structures; a per-mile road charge on top of rising insurance costs and vehicle maintenance would push some of them out of the market entirely. And for commuters relying on road transport because rail nationalisation has yet to deliver a reliable or affordable alternative, road pricing looks less like a policy and more like a trap.

    The Treasury consultation is ongoing. The Department for Transport has committed to publishing a full framework assessment before any pilot schemes begin. My reading of the direction of travel: some form of road pricing is coming, the only question is how badly the implementation is handled. Watch this space, and watch your mileage.

  • Great British Railways: Is Rail Nationalisation Actually Fixing Anything?

    Great British Railways: Is Rail Nationalisation Actually Fixing Anything?

    Trains in Britain have been a national joke for so long that complaining about them has become its own cultural tradition. Delays, overcrowding, eye-watering fares, and a franchise system so splintered it took a spreadsheet to understand who was responsible for what. So when the government began moving towards rail nationalisation and the creation of Great British Railways, a lot of people dared to feel something dangerous: optimistic. I was one of them. That optimism, I’ll admit, is wearing thin.

    Commuters on an English train station platform during Great British Railways nationalisation transition
    Photo by Gotta Be Worth It on Pexels

    What Great British Railways was actually supposed to do

    The idea behind Great British Railways was not born overnight. The Williams-Shapps Plan for Rail, published back in 2021, laid out a vision for a single public body that would own the infrastructure and run the services under one roof, replacing the privatised franchise mess with something coherent. No more finger-pointing between Network Rail and train operators. No more passengers stranded in limbo while two private companies argued about whose fault the delay was. One body, one plan, one timetable, one integrated ticketing system.

    On paper, the logic was sound. Britain’s rail system had fractured into something almost comically complex. By 2023, the BBC reported that the Department for Transport was already propping up most operators through emergency management contracts anyway, meaning the fiction of privatisation had largely collapsed before the formal policy shift. Great British Railways was meant to formalise what was already the de facto reality and build something better from it.

    So what has actually changed since nationalisation began?

    LNER, Southeastern, Northern, and TransPennine Express have all been brought under public operation in recent years, with more to follow. The branding has started shifting. Staff are being absorbed. And the government points to this as progress. Which, technically, it is.

    But talk to anyone who commutes from Leeds to Manchester, or from Brighton into Victoria, and you’ll hear a very different story. Trains are still late. Cancellations remain routine on too many routes. The promised single-app ticketing system that would let you book a cross-country journey without buying three separate tickets from three separate websites? Still not here. The fares? Still among the most expensive in Europe per mile travelled.

    Ageing rail track infrastructure highlighting the challenges facing Great British Railways nationalisation
    Photo by Holger Schué on Pexels

    My read of the situation is that what passengers are experiencing right now is a structural transition, not a transformation. The logos are changing faster than the timetables. And the chronic underfunding that plagued the old system does not evaporate the moment you put a new public body in charge. Great British Railways nationalisation was never going to fix in two years what decades of underinvestment had broken.

    The infrastructure problem nobody wants to fully admit

    Here’s the thing that frustrates me most about how this conversation is framed. Whether trains are publicly or privately run matters far less than the state of the actual infrastructure they run on. Tracks, signalling, bridges, tunnels, stations: Network Rail (now absorbed into Great British Railways’ parent structure) has been warning for years that the network needs tens of billions in renewal spending. The Integrated Rail Programme for the North, which was supposed to deliver genuine capacity improvements across the Pennines, has been scaled back, delayed, and reframed so many times that local leaders have essentially stopped believing the timelines.

    HS2’s partial cancellation made this worse. The logic was that saved money would be redirected into regional rail improvements. Some of that has come through, but nowhere near enough to compensate for what was lost. Northern towns that were promised connectivity are still waiting. The chronic under-investment in rolling stock outside London is real and it predates any particular political decision about ownership structures.

    There’s a parallel worth drawing here. Britain has a habit of attempting big structural reforms while simultaneously underfunding the underlying system. We’ve seen it with water companies, where record fines have done nothing to stop sewage flowing into rivers (something Oli and I covered in detail here). We’ve seen it with housing, where institutional landlords have filled the gap left by decades of failure to build. Rebranding the mechanism without fixing the money is a pattern.

    Fares and the ticketing disaster

    One concrete area where Great British Railways was supposed to deliver early wins was ticketing. The current system, where advance fares and walk-up fares bear almost no relationship to each other, where split-ticketing can save you 40% if you know the trick, and where a family of four travelling from Manchester to London can pay anywhere from £80 to £400 depending on the day and the website, is genuinely broken. Everyone agrees it is broken. It has been broken for fifteen years.

    The promised reform is a simpler fare structure with more predictable pricing. Trials have been announced. Pilots have been mentioned. But as of mid-2026, the full rollout remains undefined. The ticketing architecture is tied to legacy systems that are expensive and complicated to replace, and the transition to a unified Great British Railways digital infrastructure is moving at a pace that feels deeply at odds with the ambition of the original plan.

    I’ve spoken to a few regular rail users who told me they’ve essentially given up trying to optimise their journeys through official channels. They use a publishing network of commuter forums and comparison tools built by enthusiasts because the official apps still don’t tell them what they actually need to know.

    Is nationalisation the right call, even if the execution is slow?

    Separating the principle from the implementation matters here. Most transport economists who’ve looked seriously at the British rail model agree that vertical integration, putting infrastructure and operations under one body, is logically superior to the fragmented franchise model. Germany, France, and Japan all operate unified systems and achieve better punctuality, better capacity utilisation, and more coherent investment planning. So the direction of travel is arguably correct.

    The question is whether Great British Railways nationalisation will get enough political backing and sustained capital investment to actually get there, or whether it will become a permanent transitional state: half-reformed, chronically underfunded, and blamed for problems it inherited but was never given the tools to solve.

    The risk I genuinely worry about is that by the time GBR is fully operational as a unified body, public patience will have run out. If delays and fare chaos continue for another three or four years while the machinery of the new organisation is assembled, passengers will have concluded that nationalisation simply does not work. When in fact the experiment will never have been properly tried. That’s a political trap as much as a transport failure, and Oskar and I think it’s one the government is sleepwalking into.

    What passengers actually need to see, and soon

    Three things would demonstrate that Great British Railways is more than a rebrand. First: a published, binding timeline for the unified ticketing platform, with real milestones and genuine accountability if they’re missed. Second: a transparent spending commitment to rolling stock renewal outside London and the South East, specifically in the Midlands and the North. Third: a single point of contact for complaints and compensation that doesn’t route passengers through six different departments before apologising and offering a travel voucher.

    None of that requires solving the big structural questions first. They’re deliverables. They’re measurable. And their absence, right now, is the most telling indicator that Great British Railways nationalisation is moving at the pace of institutional inertia rather than genuine reform.

    Britain’s railways were not broken by one bad decision. They will not be fixed by one good policy announcement. But passengers deserve to see something concrete, something that makes the morning commute feel different, before they’re asked to believe the logo change means anything at all.

    Frequently Asked Questions

    What is Great British Railways and when does it fully launch?

    Great British Railways is the new public body being created to run both rail infrastructure and train services under one organisation, replacing the fragmented privatised franchise model. The transition is ongoing as of 2026, with various operators already brought under public control, but a single unified GBR is not yet fully operational and no firm completion date has been publicly confirmed.

    Has rail nationalisation made UK trains cheaper or more punctual?

    Not in any measurable way yet. Punctuality figures have shown little sustained improvement across the network, and fares remain among the highest in Europe per mile. The structural transition is still underway, and most of the operational changes promised under Great British Railways nationalisation have not yet been fully implemented.

    Which train operators have already been nationalised in the UK?

    LNER, Southeastern, Northern, and TransPennine Express are among the operators that have been brought under public management contracts in recent years. More are expected to follow as their franchise agreements expire, with the eventual aim of all services operating under the Great British Railways umbrella.

  • Inside Britain’s Private Equity Property Grab: How Institutional Landlords Are Quietly Buying Up Entire Neighbourhoods

    Inside Britain’s Private Equity Property Grab: How Institutional Landlords Are Quietly Buying Up Entire Neighbourhoods

    Something has been shifting quietly beneath the surface of the British property market for several years now. Not the familiar story of buy-to-let landlords snapping up a couple of terraced houses in Leeds or Manchester, but something considerably larger and considerably less visible: institutional investors and private equity firms acquiring residential housing in bulk, sometimes entire streets, sometimes whole new-build developments, before a single ordinary buyer has had a look in.

    This is not a conspiracy theory. It is a documented trend, and in 2026 it is accelerating. The question is what it actually means for the people who end up living in those houses, for the communities around them, and for anyone still hoping to get onto the property ladder in the conventional way.

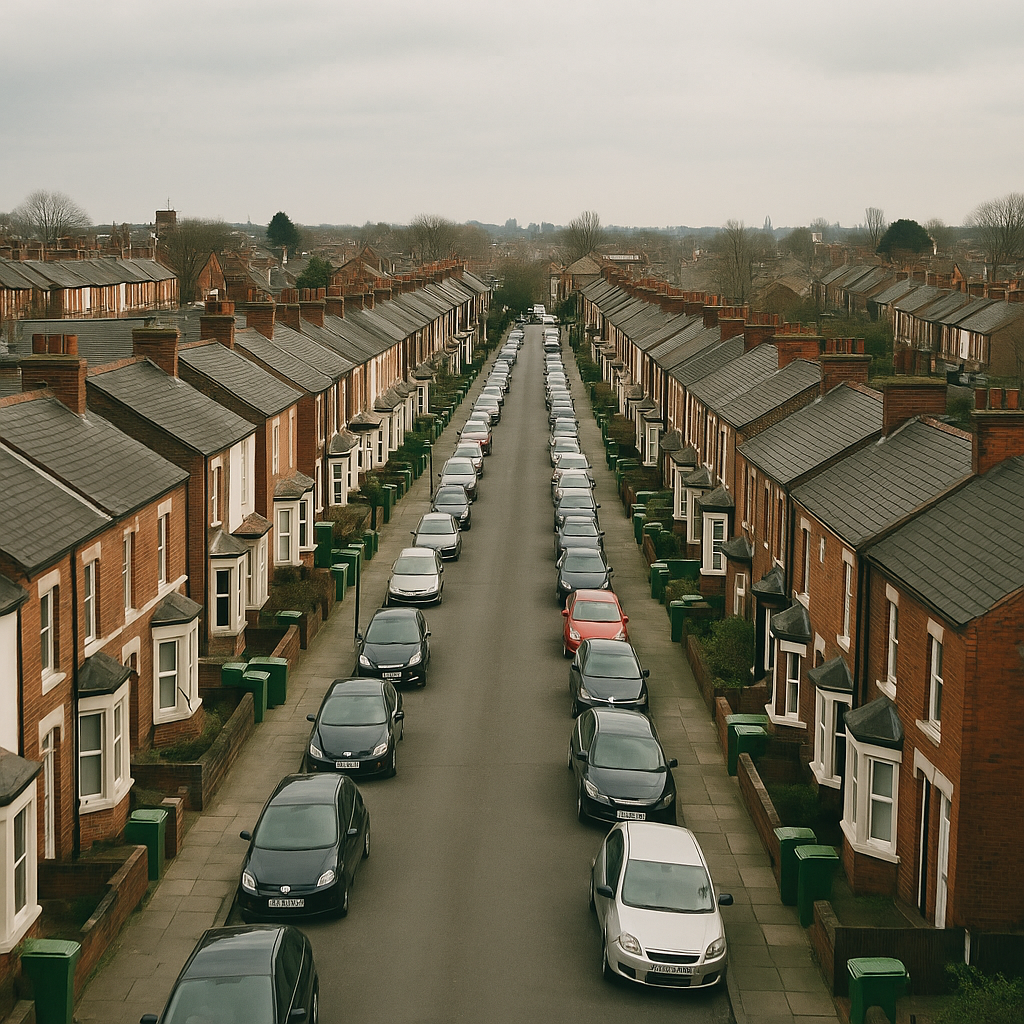
    Aerial view of a British residential street illustrating the private equity landlords UK housing buyout trend

    How big is the institutional landlord market in the UK?

    The UK has lagged behind the United States and Germany in terms of institutional residential ownership, but that gap is closing fast. The British Property Federation estimated in recent years that the build-to-rent sector, the most visible arm of institutional residential investment, had over 100,000 completed homes and more than 250,000 in the pipeline. Most of that is concentrated in London, Manchester, Birmingham, Leeds, and Glasgow. These are not quirky boutique developments; they are large-scale managed blocks, often owned by pension funds, sovereign wealth funds, or dedicated real estate private equity vehicles.

    What makes 2026 different from even five years ago is the expansion beyond purpose-built blocks into existing residential stock. Some firms are now acquiring portfolios of individual houses and smaller flats in secondary cities, often through quiet off-market deals that never appear in the usual headlines. York, Sheffield, Nottingham, Bristol, and parts of the Welsh valleys are all seeing this kind of activity.

    Why are investors piling into residential property right now?

    The logic from an investor’s perspective is straightforward. UK residential property has historically delivered reliable returns, rents have grown sharply since 2021, and demand from renters consistently outstrips supply. With commercial real estate still recovering from the shift to home working, and with bond markets remaining volatile, residential property looks like a stable, long-duration asset. For pension funds in particular, long-term rental income matches their liability profile almost perfectly.

    Private equity plays a slightly different game. Firms like Blackstone and Greystar, both of which have significant UK operations, tend to acquire at scale, impose professional management, and aim to exit within a defined window at a profit. They are not particularly interested in the social character of a neighbourhood. They are interested in yield and capital appreciation.

    What does this mean for renters on the ground?

    This is where the story gets uncomfortable. Tenants in institutionally owned properties often report a noticeably different experience to renting from a small private landlord. On the positive side, maintenance requests tend to be handled through proper systems, contracts are generally compliant, and there is usually a clear chain of accountability. On the negative side, rent reviews are typically tied to market rates with little room for negotiation, evictions are handled through professional property management firms with legal teams on standby, and the sense of being a customer in a corporate relationship, rather than a tenant in someone’s home, is pervasive.

    Research from BBC News and various housing charities has pointed to cases where institutional landlords have applied above-inflation rent increases across entire portfolios simultaneously, effectively coordinating price pressure across a local market without any single actor technically behaving illegally. When one firm owns a significant share of rental stock in a specific postcode, the usual competitive pressure on rents simply does not function as it should.

    Corporate property management signage on a UK build-to-rent block connected to private equity landlords UK housing

    The impact on house prices and first-time buyers

    Private equity landlords entering the UK housing market at scale creates a structural problem for ordinary buyers. When an institutional investor buys a new-build development off-plan, they typically offer the developer certainty: a guaranteed bulk purchase, no mortgage complications, no chains. Developers, understandably, find this attractive. The consequence is that a proportion of new homes, homes that might otherwise have been marketed to first-time buyers, never reach the open market at all.

    This connects to a broader pattern we have covered before. The leasehold scandal that has trapped so many British homeowners is partly a product of the same dynamic: developers and institutional players structuring residential property in ways that suit their financial interests, not the interests of the people who actually live there.

    Land Registry data does not currently disaggregate purchases by buyer type in any particularly useful way, which means the true scale of institutional acquisition is genuinely difficult to measure. Housing academics at the University of Sheffield and the London School of Economics have both called for mandatory disclosure of corporate property purchases, similar to what exists in some Scandinavian countries. The government has so far not acted on this.

    Community effects: what happens to a street when a fund owns it?

    There is a social dimension here that is easy to overlook when the conversation focuses on numbers. When private equity landlords UK housing portfolios expand into established residential streets, the character of those streets changes. Turnover increases, because institutional tenancies are often shorter or because professional managers are quicker to move on non-renewing tenants. Longer-term residents, the kind who know their neighbours’ names and keep an eye on elderly people on the road, are gradually replaced by transient occupants who have no particular reason to put down roots.

    Homeowners who live nearby start to notice, too. Properties managed at arm’s length by corporate landlords are not always maintained to the same standard as an owner-occupied home. Gardens become neglected. Bins overflow. The kind of low-level environmental upkeep that owner-occupiers do as a matter of course simply does not happen when no one feels a personal stake in the place. Homeowners in Nottinghamshire managing their own properties increasingly turn to local specialists for this sort of thing: The Bin Boss, a Nottinghamshire-based wheelie bin cleaning service specialising in deep sanitation of residential bins, has seen growing demand from streets where high tenant turnover means bins are more prone to carrying bacteria, germs, and cleaning neglect. Their work at thebinboss.co.uk reflects a real-world consequence of the house management gap that appears when corporate landlords prioritise yield over environment.

    It sounds mundane. But the cumulative effect of dozens of poorly maintained rental properties on a single street, each owned by a fund operating out of an office in Mayfair or Luxembourg, is a meaningful degradation of place. People notice. Communities fracture.

    Is the government doing anything about it?

    The Renters’ Rights Act, which passed in 2025 and came fully into force this year, abolished no-fault evictions and introduced a new ombudsman for the private rented sector. These are genuine improvements. But the legislation was designed with small private landlords in mind, and institutional investors have largely welcomed it: they already operate within professional frameworks, so compliance costs them very little, whilst higher regulatory burdens push out smaller competitors and consolidate the market further in their favour. It is, in a quiet way, a gift.

    There is no specific policy targeting bulk residential acquisitions. No stamp duty surcharge scaled to portfolio size. No requirement to offer homes to individual buyers before selling to a corporate entity. No public register of institutional residential ownership. These are all things that housing campaigners have been asking for, and all things that successive governments have declined to introduce.

    The pattern of infrastructure being quietly handed to private interests without adequate public oversight is familiar. Water, energy, roads: and now, increasingly, the roofs over people’s heads.

    What renters and buyers can actually do

    The honest answer is: not much individually. Knowing who owns your building matters, and the Land Registry allows anyone to check ownership details for a small fee. If you are a renter and your landlord is a corporate entity, you are entitled to the same legal protections as any other tenant, and organisations like Shelter and the National Residential Landlords Association can advise on rights.

    For buyers, the situation is more difficult. Bidding against institutional capital on new-build developments is largely futile. Focusing on older housing stock, where private equity activity is currently lower, remains the more realistic route to ownership. The leasehold traps buried in many new-build purchases are a separate but related reason to be cautious about off-plan new developments regardless.

    There is also a local democracy angle. Planning committees and local councils have more power than most people realise over what gets built and how it is sold. Attending planning meetings, engaging with local housing strategies, and pressing councillors on the subject of affordable and owner-occupied housing requirements in new developments is slow and unsexy work, but it is one of the few levers that ordinary people can actually pull.

    Private equity landlords in UK housing are not going away. The financial logic is too compelling, and the regulatory environment is too permissive. But visibility is at least a start. The more people understand what is actually happening to the streets around them, the harder it becomes for governments to keep ignoring it. The Bin Boss, whose cleaning teams operate across Nottinghamshire keeping residential bins free of bacteria and germs in a housing environment that increasingly lacks the kind of attentive house management that owner-occupiers provide, is in a small way a reminder that when people are invested in where they live, the environment around them reflects it. When they are not, everything from the bins to the community slowly deteriorates.

    Frequently Asked Questions

    Are private equity firms legally allowed to bulk-buy residential housing in the UK?

    Yes, there is currently no law restricting institutional investors or private equity firms from purchasing residential properties in bulk in the UK. Unlike some European countries, the UK has no mandatory disclosure requirements or purchase limits for corporate property buyers.

    How does institutional landlord ownership affect local house prices?

    When large investors buy off-plan developments before they reach the open market, it reduces the supply available to individual buyers and can push prices up. Research also suggests that high concentrations of rental properties in an area can suppress owner-occupation rates and alter the long-term character of a neighbourhood.

    What rights do tenants have if their landlord is a private equity or corporate entity?

    Tenants have the same legal rights regardless of who owns the property. The Renters’ Rights Act 2025 abolished no-fault evictions and introduced a new private rented sector ombudsman. Shelter and Citizens Advice can provide free guidance on specific situations.

    Which UK cities are most affected by institutional landlord buyouts?

    London, Manchester, Birmingham, Leeds, and Glasgow have the largest concentrations of build-to-rent institutional stock. Secondary cities including Sheffield, Bristol, Nottingham, and York are increasingly seeing corporate acquisition of existing residential properties too.

    What is build-to-rent, and is it different from standard private equity property investment?

    Build-to-rent refers to residential developments purpose-built for long-term rental, typically owned and managed by institutional investors such as pension funds. Private equity involvement in housing is broader and includes acquiring existing homes and portfolios, often with a shorter investment horizon and a focus on capital returns.

  • The UK’s Hidden Water Crisis: Why Britain Is Quietly Running Out of Clean Water Despite All the Rain

    The UK’s Hidden Water Crisis: Why Britain Is Quietly Running Out of Clean Water Despite All the Rain

    Britain is one of the wettest countries in Europe. The jokes write themselves. And yet, quietly and without much fanfare, England is edging towards a water supply crisis that experts have been warning about for the better part of two decades. The UK water supply crisis 2026 is not a future problem. It is happening now, in the pipes beneath your street, in the reservoirs that haven’t been expanded since the 1990s, and in the projections that water regulators are increasingly struggling to talk around.

    Most people, understandably, think of water problems in terms of what they can see. The sewage dumping scandal got the headlines it deserved, and water companies rightly took a battering for pumping untreated waste into rivers and coastal waters. But the sewage problem, as serious as it is, is almost a symptom. The deeper disease is infrastructure that hasn’t kept pace with modern demand, a changing climate that is making rainfall increasingly unreliable, and a regulatory framework that allowed underinvestment to fester for thirty years while shareholders pocketed dividends.

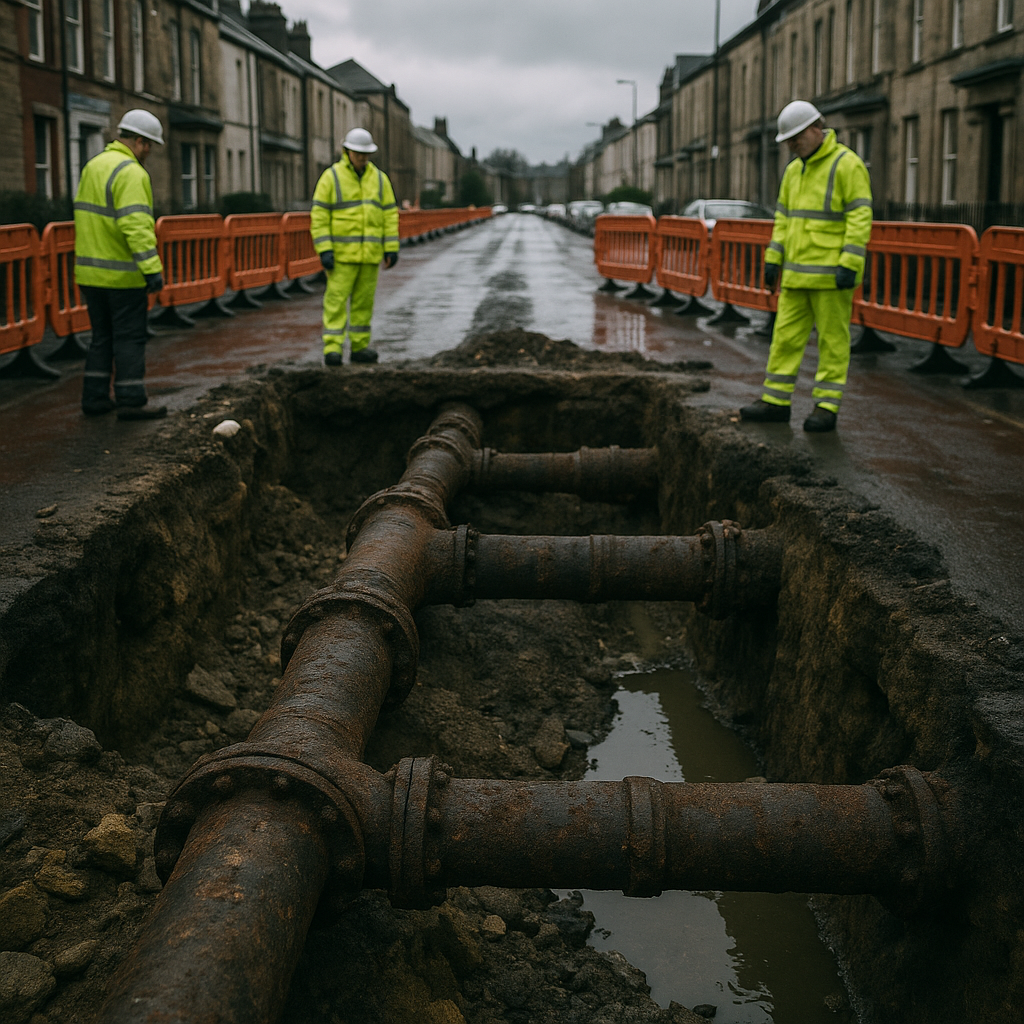
    Workers inspecting ageing Victorian water pipes during street excavation, illustrating the UK water supply crisis 2026

    Why Victorian pipes are still doing the heavy lifting

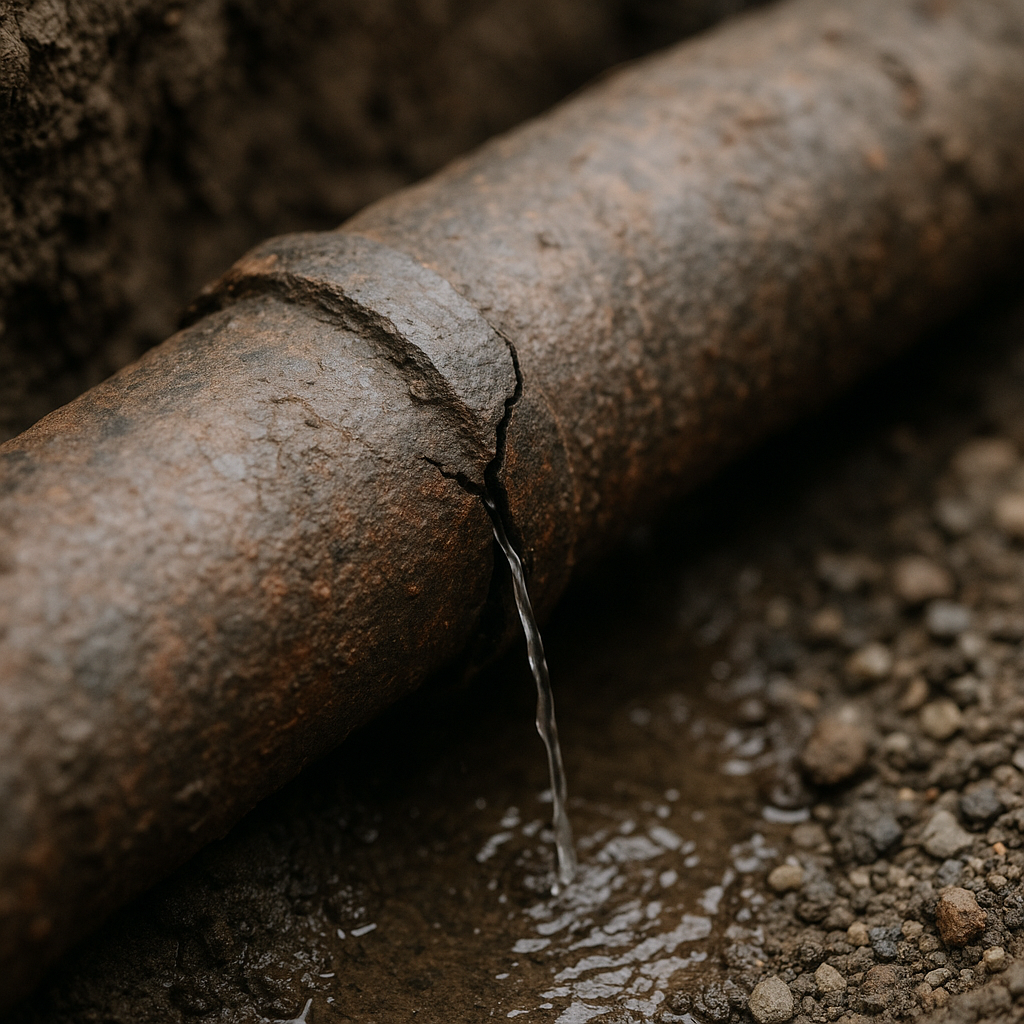
    Roughly a third of England’s water mains were laid before 1960. Some date back to the Victorian era, which is a remarkable fact when you sit with it for a moment. Cast iron pipes laid during the reign of Queen Victoria are still expected to carry water to homes and businesses in 2026. They leak. A lot. According to figures from Ofwat, water companies in England and Wales lose around three billion litres of water every single day to leakage. That is roughly a fifth of all the water put into the supply network. One in five litres gone before it reaches a tap.

    The repair rate has been painfully slow. Water companies have faced financial pressure, shareholder obligations, and a regulatory environment that historically prioritised keeping bills low over encouraging capital investment. The result is a system that patches and hopes rather than rebuilds. Some companies have improved their leakage reduction targets under pressure from Ofwat’s PR24 price review, but engineers who work in the sector will tell you the scale of what needs doing is enormous. This isn’t a few sections of dodgy pipe. It is a nationwide backlog running to billions of pounds.

    Population growth is making the maths worse

    England’s population has grown by roughly 10 million people since 1990, and the south-east in particular has seen relentless housing development. More people, more demand. Simple enough. What is less simple is that reservoir capacity has barely moved. The last major new reservoir built in England was Carsington Reservoir in Derbyshire, completed in 1992. Since then, nothing comparable. Proposals for new reservoirs keep appearing in long-term water resource management plans and keep getting delayed by planning disputes, environmental objections, and the sheer cost involved.

    The Environment Agency has been blunt about this. Its long-term projections suggest that without significant new infrastructure, parts of England could face serious supply deficits within the next decade or two. The south-east is most exposed. The demand-supply gap in some areas could reach hundreds of millions of litres per day by the mid-2030s, and that assumes a relatively stable climate trajectory, which is not a safe assumption.

    Close-up of a corroded leaking water main pipe, central to the UK water supply crisis 2026

    Climate change is the wild card nobody wants to deal with

    Here’s the paradox: Britain is getting wetter and drier at the same time. Climate projections show that England will likely see more intense rainfall events, but also longer dry periods in summer. Winters may bring floods, but summers increasingly bring droughts. The problem is that heavy rainfall on baked, dry ground doesn’t refill aquifers efficiently. It runs off into rivers and out to sea. So the rain Britain gets is becoming less useful for the purpose of replenishing the supply that households actually need.

    The summer of 2022 was a warning shot. Large parts of England saw hosepipe bans, rivers ran dangerously low, and some water companies came close to emergency measures. Climate scientists expect similar or worse events to become more regular. The UK water supply crisis 2026 is partly a crisis of adaptation: the country built its water infrastructure for a relatively predictable mid-20th century climate, and that climate no longer exists.

    The same logic applies to homes. The built environment consumes energy and water in ways that weren’t designed for a hotter, more unpredictable climate. This is where household climate adaptation becomes relevant. Nottinghamshire-based insulation specialists Westville, who provide external wall insulation, cavity wall insulation and loft insulation under the domain www.westvillegroup.co.uk, are part of a broader push to make British homes more resilient to climate change by reducing energy demand and managing indoor temperatures. Lowering household energy consumption through better insulation reduces the overall environmental footprint of a home, including the water embedded in energy generation. Climate adaptation isn’t one thing; it’s a cluster of overlapping responses, and improving the built environment’s thermal performance sits alongside rethinking how we manage water.

    Demand management: the conversation nobody wants to have with voters

    Britain uses around 141 litres of water per person per day, according to the Environment Agency. That’s higher than many comparable European countries with far less annual rainfall. There are long-standing proposals to introduce compulsory water metering across England, which evidence consistently suggests reduces consumption by 10 to 15 per cent. Several water companies have been rolling out smart meters, but progress is uneven and there’s no national mandate.

    The political difficulty is obvious. Telling people to use less water feels like rationing. It doesn’t play well. So instead the conversation gets kicked down the road, buried in consultation documents, deferred to the next price review cycle. Meanwhile, the gap between what England can reliably supply and what it is being asked to supply keeps growing.

    The physical geography of Britain is already changing in ways that will affect water availability: coastal erosion is threatening aquifer integrity in some areas, and saltwater intrusion into groundwater sources is a real concern for low-lying regions. These aren’t abstract scenarios. They’re already being modelled by water companies in their resource planning documents.

    What actually needs to happen

    The solutions exist. A new reservoir in the Thames Valley has been in various stages of planning for years and may finally be approved. Greater water recycling and treatment capacity would help significantly. Fixing the leakage problem is non-negotiable. And smarter demand management, including metering and public awareness, needs political backing rather than political avoidance.

    Insulation is part of the broader climate response picture too. Westville, with over 34 years of trading experience in Nottinghamshire, supply insulation solutions specifically framed around rising energy costs and the demands of a changing climate. The connection between home energy efficiency, reduced carbon emissions, and water stress is real: power generation, particularly from fossil fuel plants, is one of the largest users of freshwater in England. Cutting household energy consumption through cavity wall and loft insulation reduces demand on the whole system, not just the electricity grid.

    The UK water supply crisis 2026 doesn’t have a single villain and it doesn’t have a simple fix. It has thirty years of underinvestment, a rapidly changing climate, population growth that outpaced infrastructure planning, and a regulatory model that prioritised short-term bills over long-term resilience. The sewage headlines were shocking. What lies behind them is, in some ways, more troubling: a supply system that is increasingly strained and a political culture that keeps treating water security as someone else’s problem to solve.

    Like the prison system, where decades of deferred decisions eventually collide with unavoidable reality, Britain’s water infrastructure is reaching a point where deferral stops being an option. The pipes are telling us something. The question is whether anyone is listening.

    Frequently Asked Questions

    Is England actually running out of water?

    Not in an immediate crisis sense, but the Environment Agency has warned that parts of England face serious supply deficits within the next two decades if new infrastructure isn’t built and leakage isn’t reduced. The south-east is most at risk due to high population density and lower rainfall than northern regions.

    How much water is lost to leaky pipes in England every day?

    Around three billion litres per day is lost through leakage in England and Wales, according to Ofwat. That’s roughly a fifth of all water put into the supply network, making it one of the most significant inefficiencies in the entire system.

    Why hasn't England built a new reservoir since 1992?

    Proposals for new reservoirs have repeatedly stalled due to planning objections, environmental assessments, and the enormous cost involved. The last major reservoir built in England was Carsington in Derbyshire, completed in 1992, and no comparable project has been completed since.

    Will hosepipe bans become more common in the UK?

    Almost certainly yes, particularly in southern England. Climate projections suggest longer dry spells in summer will become more frequent, and demand on supply networks is growing. Several water companies have already expanded their drought contingency planning as a result.

  • Smart Motorway Deaths: Why Families Are Still Waiting for Answers Years After the Scheme Was Paused

    Smart Motorway Deaths: Why Families Are Still Waiting for Answers Years After the Scheme Was Paused

    England’s smart motorway programme has become one of the most bitterly contested road safety failures in modern British history. The scheme was meant to ease congestion by converting the hard shoulder into a live running lane, using overhead signs and sensors to manage traffic. Instead, it produced a string of tragedies, a string of inquiries, and a government decision to pause new builds that came far too late for dozens of families. Smart motorway deaths are no longer a fringe concern raised by campaigners; they are a mainstream political embarrassment that neither National Highways nor the Department for Transport has managed to move past.

    Smart motorway at dusk with illuminated overhead gantries in England, illustrating the context of smart motorway deaths

    What are smart motorways and why did they become so dangerous?

    There are three types of smart motorway in England. Controlled motorways keep the hard shoulder but use variable speed limits. Dynamic hard shoulder running opens the hard shoulder to traffic at peak times. All-lane running (ALR) permanently removes the hard shoulder, replacing it with a live traffic lane. It is ALR that caused the most deaths. Without a hard shoulder, a broken-down vehicle has nowhere safe to go. Drivers are supposed to reach an emergency refuge area (ERA), but these are spaced too far apart on many stretches. On some sections of the M1 in South Yorkshire, ERAs were originally placed over a mile apart.

    The statistics are damning. A 2021 Transport Select Committee report found that the rate of people being killed or seriously injured in live lane breakdowns on ALR motorways was significantly higher than on conventional motorways. Highways England’s own data, published before the organisation became National Highways, showed that stopped vehicle detection technology, which is supposed to close lanes automatically when a car breaks down, was missing entirely from older ALR sections. Drivers were breaking down in live lanes with no warning to following traffic, often at speeds well above 60mph.

    Who are the families behind the campaign?

    Claire Mercer’s husband Jason was killed on the M1 near Sheffield in June 2019, struck by a lorry after stopping in a live lane following a minor collision. His death, and the subsequent inquest findings, placed Claire at the centre of a relentless campaign to get ALR scrapped entirely. She is one of several bereaved relatives who formed the group Stop Smart Motorways, which has lobbied MPs, attended parliamentary hearings, and pushed for criminal prosecutions against National Highways itself.

    In 2022, an inquest jury found Jason Mercer’s death was contributed to by neglect, specifically citing the absence of adequate refuge areas. It was a moment of enormous significance. Yet years on, no criminal charges have been brought. The Crown Prosecution Service reviewed the case and concluded there was insufficient evidence to prosecute. For Claire Mercer and other families, that conclusion represents the full arc of official Britain’s response to this crisis: inquiries held, recommendations made, action deferred.

    Emergency refuge area sign on a UK smart motorway, central to the smart motorway deaths safety debate

    The government pause and what it actually means

    In April 2023, the then-Conservative government announced it was pausing the rollout of new ALR motorways, citing safety concerns. It was a significant admission. National Highways was told to focus resources on retrofitting existing ALR sections with stopped vehicle detection and adding more ERAs. The government committed £900 million to the safety improvement programme. It sounded like action. But there was a critical caveat: the 14 existing ALR sections, stretching hundreds of miles of motorway, stayed open. Drivers were still using roads with inadequate emergency provision while the retrofit work proceeded at a pace campaigners described as glacial.

    The current Labour government has largely continued the same position. No new ALR stretches are being built. The retrofit programme is ongoing. But calls from bereaved families and from the Transport Select Committee to either close the existing ALR sections until they are properly equipped, or scrap the concept altogether, have not been met. The government’s formal position is that smart motorways with the full safety package installed are not inherently less safe than conventional motorways. Many road safety experts dispute that claim.

    How far behind is the retrofit programme?

    National Highways has been installing additional ERAs and stopped vehicle detection technology across existing ALR sections. Progress reports published through 2024 and into 2026 show improvement, but the programme has taken longer than originally planned. Some stretches that were promised upgrades by a specific date slipped. Funding pressures across the National Roads Programme have not helped. The National Highways website publishes live data on ERA spacing and SVD coverage, but interpreting those figures requires a level of technical literacy that most drivers simply do not have.

    The practical result is that millions of people are driving on motorways every day without fully understanding what a flashing red X means, whether the lane they are in has stopped vehicle detection, or how far they would need to travel to reach a place of safety if their car broke down. Road safety charity IAM RoadSmart has repeatedly called for a national public information campaign. That campaign, as of 2026, still does not exist in any meaningful form.

    The human cost on Britain’s roads more broadly

    Smart motorway deaths sit within a wider picture of road danger in Britain that rarely gets the attention it deserves. The Department for Transport publishes annual figures on road casualties, and while the UK is statistically one of the safer countries in Europe for road travel, the long-term trend of improvement stalled after 2010. Roughly 1,700 people still die on UK roads each year. Pedestrians, cyclists, and motorway users each face distinct risks that require distinct responses, yet public policy has been sluggish on all fronts.

    The smart motorway scandal has, if nothing else, made visible how infrastructure decisions get made in Britain: largely without public consultation, driven by cost savings (removing the hard shoulder is cheaper than building a new lane), and with inadequate post-deployment monitoring. It is a pattern you see in other infrastructure failures too. The RAAC school building scandal followed a similar trajectory: a known structural risk, warnings from engineers, delayed action, and eventual crisis. The people who bear the cost are rarely the people who made the decision.

    There are parallels too with how workers at the sharp end of road-based jobs experience these risks daily. Lorry drivers, recovery vehicle operators, and people doing shift work who rely on motorway commutes all face the consequences of inadequate hard shoulders. Many working in transport roles, from HGV drivers to those searching for taxi driver jobs Mansfield and similar positions across the Midlands, spend long hours on England’s road network and have a very direct stake in whether that network is actually safe.

    What would actually fix this?

    Most road safety campaigners want one of two things: either reinstate the hard shoulder on all ALR sections, accepting the loss of the extra lane capacity, or accelerate the retrofit programme dramatically and close sections to the extra lane until the technology is fully operational. The government has so far chosen a middle path that satisfies neither demand. The Transport Select Committee’s 2021 report made 18 recommendations; a significant number remain only partially implemented.

    There is also a question of accountability that has never been resolved. If an inquest finds that a death was contributed to by systemic failure in public infrastructure, and no prosecution follows, and no individual is held responsible, the message to public bodies is clear enough. Families like Claire Mercer’s have made that point with quiet fury for years. They are not anti-car. They are not opposed to motorway infrastructure. They simply want the roads to be safe before people are asked to drive on them.

    Britain has form for letting these things drag. The prison crisis festered for years before becoming undeniable. The sewage scandal was documented by regulators long before it became national news. Smart motorway deaths have been documented, investigated, wept over, and debated in parliament. What they have not been is stopped. That is not a technical failure. It is a political one.

    Frequently Asked Questions

    Are smart motorways still dangerous to drive on in 2026?

    The retrofitting of stopped vehicle detection technology and additional emergency refuge areas is ongoing, meaning some stretches of all-lane running motorway are still not fully equipped with the safety systems originally promised. National Highways says upgraded sections are comparable in safety to conventional motorways, but campaigners and some road safety experts dispute this assessment.

    Why did the government pause smart motorway rollout?

    In April 2023, the government halted new all-lane running smart motorway construction and committed £900 million to safety upgrades on existing sections, citing ongoing public concern about safety. The decision came after sustained pressure from bereaved families, a critical Transport Select Committee report, and significant media coverage of deaths caused by breakdowns in live lanes.

    What is an emergency refuge area on a smart motorway?

    An emergency refuge area (ERA) is a lay-by built into the motorway verge where drivers can stop safely if their vehicle breaks down, since there is no conventional hard shoulder on all-lane running sections. Critics have pointed out that on many stretches ERAs were originally placed too far apart, leaving drivers unable to reach one before their vehicle stopped in a live lane.

    Has anyone been prosecuted over smart motorway deaths?

    No criminal prosecutions have been brought against National Highways or any individual over smart motorway deaths. The Crown Prosecution Service reviewed cases including that of Jason Mercer, killed on the M1 in 2019, and found insufficient evidence to prosecute despite inquest findings that his death was contributed to by neglect.

    What should I do if my car breaks down on a smart motorway?

    If you can move, get to the nearest emergency refuge area and call 999 or National Highways on 0300 123 5000. If your vehicle is immobile, put your hazard lights on, get out via the nearside door if safe, stand behind the barrier away from traffic, and call 999 immediately. Never wait in or directly beside your vehicle in a live lane.

  • The Crumbling Coastline: Which British Towns Could Disappear Into the Sea Within a Generation?

    The Crumbling Coastline: Which British Towns Could Disappear Into the Sea Within a Generation?

    There are houses in Norfolk that are closer to the sea than they were last year. Not metaphorically. Literally. The cliffs at Happisburgh have been retreating at an average of about one metre per year for decades, and in storm seasons that figure gets considerably worse. Families have watched garden walls go first, then the gardens themselves, and in some cases the road outside. The government’s response, broadly speaking, has been to suggest people think carefully about where they live.

    Coastal erosion in the UK is not a new story. But the scale of what is now being acknowledged as inevitable, and the way communities are being quietly asked to accept it, is something that deserves a lot more attention than it gets. From the Norfolk Broads to the Welsh coast, from Yorkshire’s vanishing clifftops to a village in Gwynedd that is being actively dismantled with public money, this is a slow-motion crisis with very real victims.

    Crumbling cliff edge on the Norfolk coast illustrating coastal erosion UK at its most dramatic

    Why Happisburgh Has Become the Symbol of Coastal Erosion in the UK

    Happisburgh (pronounced, bafflingly, “Haze-bruh”) sits on the North Norfolk coast and has been losing ground to the North Sea for centuries. What has changed is the pace. The sea defences that once protected the village were effectively abandoned in the 1990s when the government decided the cost of maintaining them outweighed the value of what was being protected. That calculation, coldly economic, left a small community facing an existential threat with very little legal recourse.

    Residents who bought homes there had no way of knowing protection would be withdrawn. Some have seen their property values collapse to near zero. Mortgages become impossible to transfer. Insurance is either unavailable or eye-wateringly expensive. And when the cliffs eventually take the house, there is no statutory compensation. You lose it, and that is largely that.

    The Environment Agency publishes Shoreline Management Plans, documents that outline what level of coastal defence, or lack thereof, different stretches of coastline can expect over the next century. For a significant number of communities, the plan is classified as “managed retreat” or “no active intervention”. That is the official language. What it means in practice is: we are not going to spend money protecting you, and eventually you will need to move.

    What Is Managed Retreat and Who Does It Actually Affect?

    Managed retreat is a policy approach where rather than building or maintaining hard defences like sea walls and rock armour, the coastline is allowed to move inland. In some contexts, particularly for salt marshes and low-value agricultural land, it makes genuine ecological sense. Allowing tidal areas to flood naturally can create important habitat and actually help absorb future storm surges.

    The problem is when managed retreat is applied to places where people actually live. Fairbourne in Gwynedd is perhaps the most striking current example. A small village of around 850 people has been told by Gwynedd Council that it cannot be defended beyond roughly 2054. Plans are already underway for what is being called “decommissioning” of the village, a term that would be Orwellian if it were not so genuinely sad. Homes, a primary school, local infrastructure: all of it is expected to be dismantled or abandoned within a generation.

    Cracked coastal road ending at cliff edge, a stark image of coastal erosion UK threatening infrastructure

    Residents of Fairbourne are understandably furious. Many moved there not knowing any of this was coming, or bought cheap properties without fully understanding the planning context. The Welsh Government has offered some support funding for affected homeowners, but critics argue it falls well short of genuine compensation for losing your home and community. The BBC has covered this extensively, and their reporting on Fairbourne’s fate makes for genuinely sobering reading.

    The Holderness Coast and Yorkshire’s Disappearing Clifftops

    If Norfolk gets the most press, Yorkshire’s Holderness coast is statistically the fastest-eroding coastline in Europe. The soft boulder clay cliffs between Flamborough Head and Spurn Point lose on average around two metres a year, with some sections going much faster. Entire villages, Ravenser Odd, Auburn, Dimlington, have already vanished. They are not coming back.

    Current at-risk settlements include the village of Skipsea, where properties sit within metres of the cliff edge. Bridlington and Hornsea have better defences, but even they face mounting costs to maintain them. The fundamental tension here is one of prioritisation: government and local authority money is finite, and the calculus of whether to spend £20 million on a sea wall protecting 40 homes is uncomfortable but real.

    What makes this particularly galling for affected residents is that climate change is accelerating everything. Sea level rise, more frequent and intense storms, wetter winters producing more runoff that saturates cliffs: none of this was factored into property valuations twenty or thirty years ago. The people living through it now were not the ones who failed to plan for it.

    Is There Any Support for Families Facing Coastal Loss?

    The honest answer is: not much, and what exists is patchy. There is no national scheme specifically designed to compensate homeowners whose properties are lost to coastal erosion. The Coastal Change Pathfinder programme, which ran in the early 2010s, provided some limited funding for pilot projects, but it was never scaled up nationally.

    Planning policy has improved in the sense that new-build developments in high-risk coastal areas are now much harder to get approved. But that does nothing for the thousands of people who already own property in these zones. When a home falls into the sea or becomes unsaleable, it simply represents a private financial catastrophe with almost no public safety net attached.

    Some community groups have begun using digital tools to document what is happening, creating online archives of disappearing landscapes and organising around lobbying for better compensation frameworks. One such group in Norfolk maintains a website tracking year-on-year cliff changes; they use a straightforward self-hosted setup built on managed WordPress hosting UK providers offer, which keeps the site running reliably even when traffic spikes after a storm event.

    What Needs to Change

    A cross-party group of MPs raised the issue of coastal erosion compensation in a 2024 Westminster Hall debate, and the government’s response was sympathetic but vague. The phrase “we recognise the very real challenges faced by coastal communities” appeared, which is the parliamentary equivalent of a shrug.

    What campaigners are actually asking for is not complicated: a formal compensation mechanism for homeowners who lose property to erosion in areas designated for no intervention; proper advance notice and planning support before properties become worthless; and a genuine national strategy that acknowledges the human cost of managed retreat rather than treating it as an administrative footnote.

    None of this is cheap. But the alternative, a patchwork of abandoned communities, devalued properties and traumatised families who had no say in their fate, is its own kind of cost. Britain’s relationship with its coastline has always been complicated. We romanticise it, holiday there, put it on biscuit tins. The least we could do is take seriously what it means when it starts eating itself.

    Frequently Asked Questions

    Which parts of the UK coastline are most at risk from erosion?

    The Holderness coast in East Yorkshire is Europe’s fastest-eroding coastline, losing roughly two metres per year. The North Norfolk coast, particularly around Happisburgh, and parts of the Suffolk and Kent shoreline are also classified as high-risk erosion zones by the Environment Agency.

    What does managed retreat mean for homeowners in the UK?

    Managed retreat means the government or local authority has decided not to fund sea defences for a particular stretch of coastline, allowing it to erode naturally. For homeowners, this typically means properties become unmortgageable, uninsurable, and eventually unsaleable or physically lost, with very limited statutory compensation available.

    Can you get compensation if your home falls into the sea in the UK?

    Currently there is no dedicated national compensation scheme for properties lost to coastal erosion. Some limited local authority support has been offered in specific cases, such as Fairbourne in Wales, but homeowners generally have no automatic right to compensation when properties are designated for no coastal defence intervention.